


EN
How Investors May Respond To Elecnor (BME:ENO) Hazelwood Battery Contract
- Elecnor has been selected as balance-of-plant contractor for the 150MW/300MWh Hazelwood battery energy storage system in Victoria, Australia, working alongside ENGIE and Sungrow on a project scheduled to start commercial operations in 2028.
- This Hazelwood contract highlights Elecnor’s ability to win large international grid-scale storage work, which directly connects to its broader role in energy transition infrastructure and services.
- We will now look at how Elecnor’s Hazelwood battery role could influence the existing investment narrative around its energy transition exposure.
Scan for other grid and energy transition stocks that could respond to similar contract wins by reviewing our curated 44 power grid technology and infrastructure stocks alongside Elecnor’s Hazelwood battery role.
Elecnor Investment Narrative Recap
To own Elecnor, you need to believe its mix of services, projects and concessions can keep turning the long term energy transition story into a steady backlog and solid cash generation. The Hazelwood battery role supports that idea, but the more immediate focus sits on how consistently the group converts its project pipeline into earnings and cash.
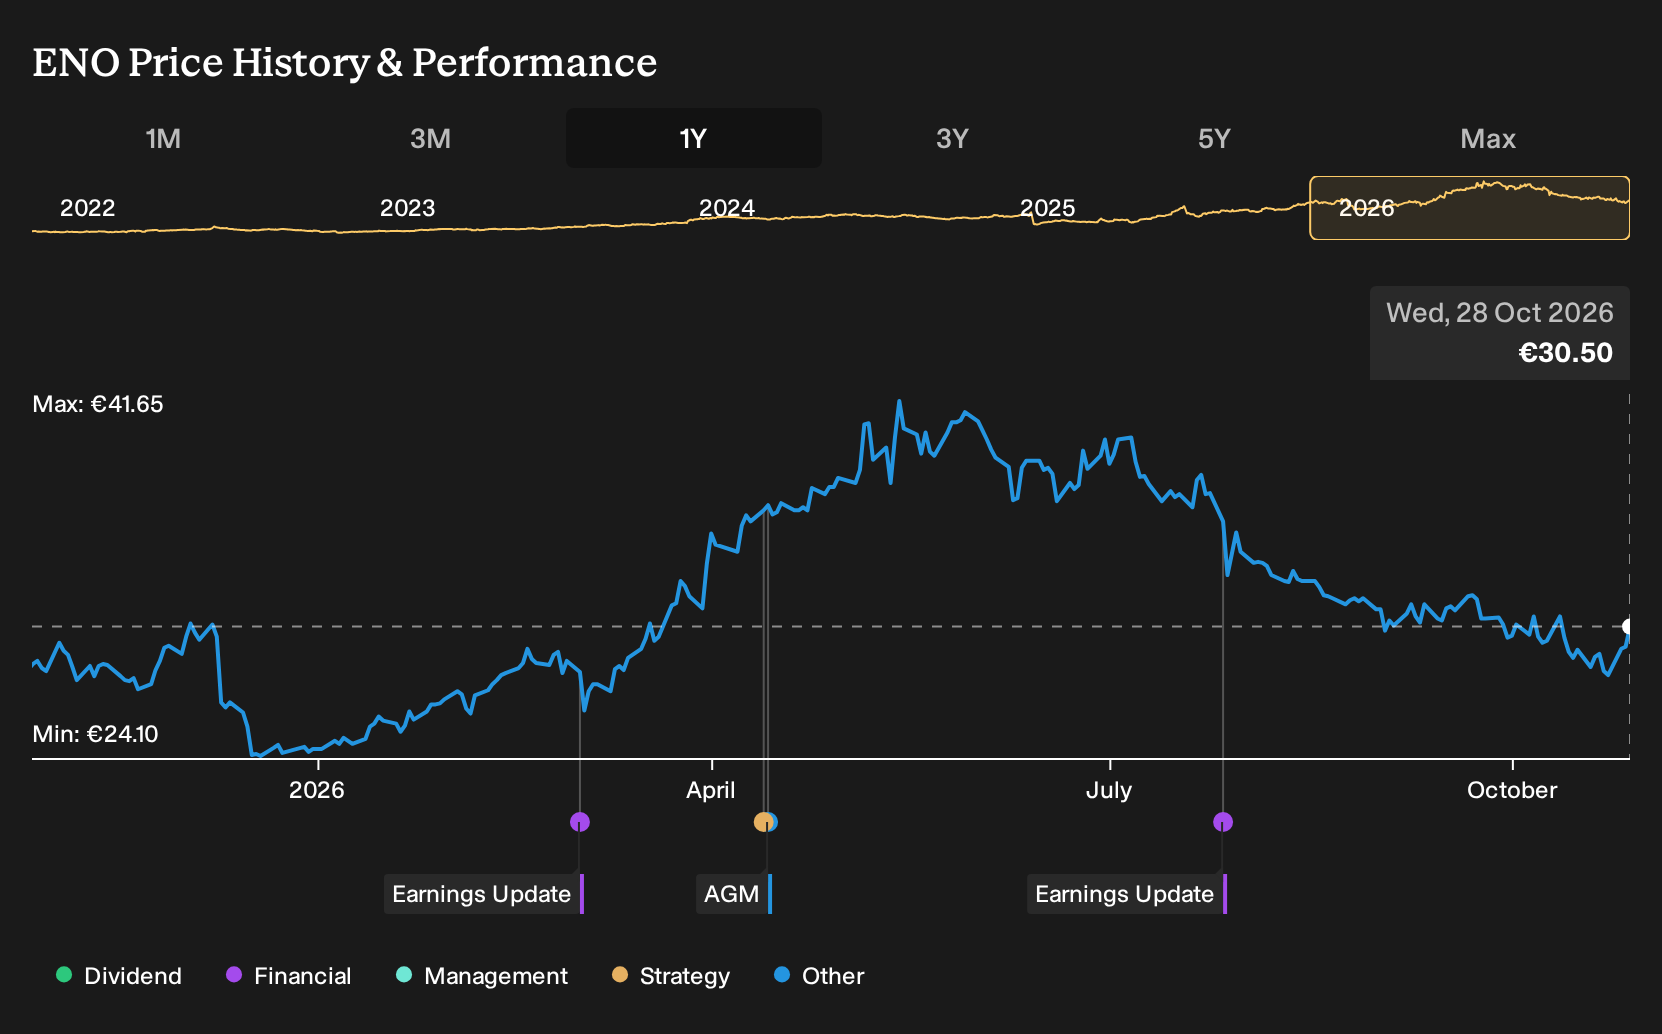
The near term catalyst is the Q3 2026 earnings release and call on 29 October 2026, where investors will look for confirmation that profitability, margins around 6% to 6.8% and cash flow remain on track. The biggest risk is any slowdown or pricing pressure in key geographies that dents backlog quality or returns.
The most relevant upcoming announcement is Elecnor’s Q3 2026 earnings and call. Hazelwood gives investors a concrete example of how the projects arm can win complex grid scale work that fits the long term electrification theme. The call is where management can spell out how this type of contract fits into the current executable backlog and capital needs.
Attention is likely to fall on how this project mix interacts with rising capital allocation to concessions through Celeo and with the plan to distribute more than €220 million in dividends between 2025 and 2027. Execution discipline, funding structure and any comments on tender conditions in markets like Australia will be important markers for assessing future risk and reward.
Elecnor Forecasts Behind the Hazelwood Story
Elecnor's Hazelwood battery work drops into a wider analyst framework that already assumes the group can keep lifting both revenue and profit over the next few years. Forecasts sketch out a business that leans on long term electrification spending and then translates a growing order book into sturdier earnings rather than dramatic headline expansion.
Consensus expectations point to revenue growth of 5.8% a year over the next three years, with current earnings of €110.7 million projected to reach €178.0 million by 2029. That implies an earnings increase of about €67 million versus today and is anchored to a forecast year of 2029 for both revenue and profit estimates.
Elecnor's narrative projects €5.2 billion in revenue and €178.0 million in earnings by 2029. This setup assumes yearly revenue growth of 5.8% and an earnings increase of about €67 million from €110.7 million today.
Discover why Elecnor's fair value suggests a 38% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view treats Elecnor’s concessions push as the real catalyst, not single contracts like Hazelwood. Bullish analysts were already modelling revenue of €6.0b and earnings of €235.5m by 2029, far above consensus. Those forecasts came before this battery award, so opinions may shift as you compare different narratives.
Explore 3 other Elecnor fair value estimates, including one that suggests as much as 190% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Elecnor research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Elecnor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Elecnor's overall financial health at a glance.
Looking For More Ideas Beyond Elecnor?
Once you have a view on Elecnor, it can help to cross check that thesis against other companies with different risk and income profiles using the Simply Wall St Screener.
- If you want potential value on your side, scan through our 191 high quality undervalued stocks that currently combine quality fundamentals with discounted prices.
- For income focused portfolios, filter for dependable payers using the 226 dividend fortresses and see which businesses offer higher yields with supporting cash flows.
- To keep downside risk in check, start with the 228 resilient stocks with low risk scores and see which companies pair more resilient balance sheets with calmer share price moves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com