


EN
Missed Mitsui's Run? What Holders Had To Believe
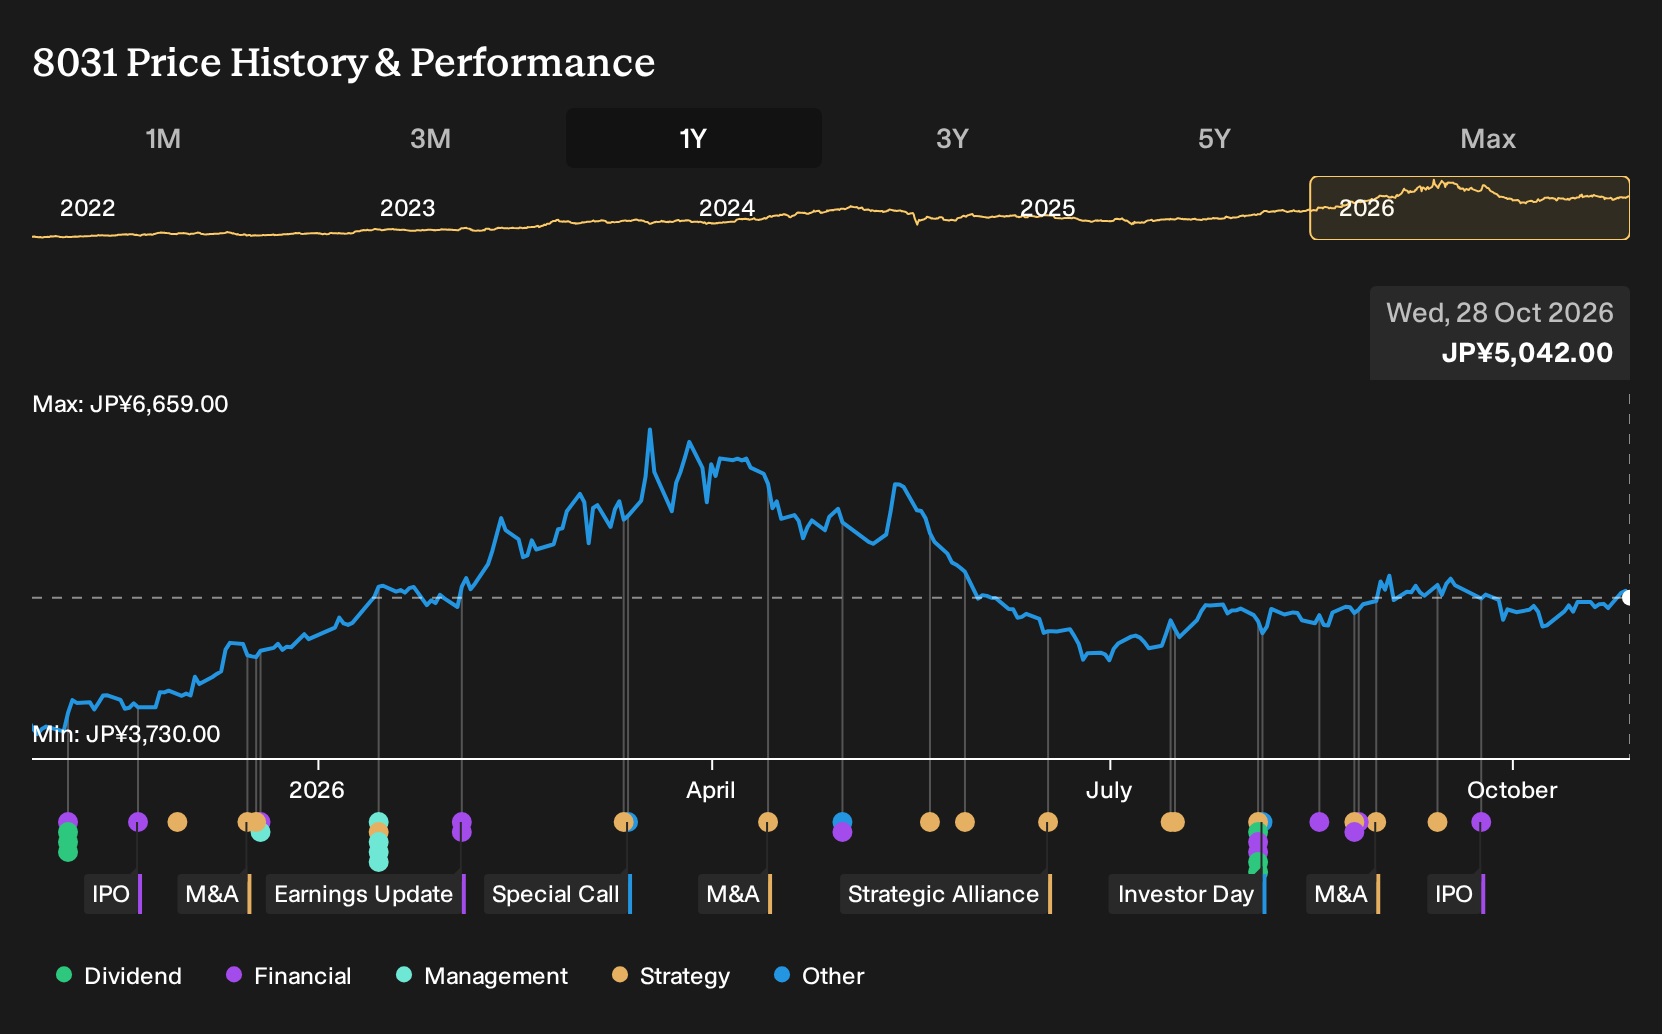
If you only glanced at the noisy debate around Mitsui in late 2025, with one camp arguing for prosperity from energy transition and Asia Pacific growth and another warning that fossil fuel exposure would cap returns, the outcome might surprise you. For Mitsui shareholders, the return over the past year was 38.4%, including dividends. If you had been deciding whether to buy or avoid the stock then, what exactly in the record could have guided that call?
If the move has made Mitsui harder to judge, start where the gap is still open and scan 14 high quality undervalued stocks.
The Two Mitsui Narratives Investors Had To Weigh
The shares cost ¥3,788 at the start of the period, and anyone looking at Mitsui then had to choose between two very different futures.
The bullish story put Fair Value at ¥4,700, a price that would only make sense if its growth assumptions played out. This view leaned on aggressive expansion into LNG, hydrogen, renewables, and digital logistics, with analysts assuming revenue would rise 6.8% a year and earnings reach ¥991.7b by 2028.
The bearish view saw Fair Value at ¥2,860, reflecting a more cautious set of expectations. That side focused on heavy fossil fuel exposure, pressure from ESG rules, and execution risk in new sectors, even while assuming earnings would still reach ¥834.8b by 2028 with margins at 6.2%.
What The Evidence Around Mitsui Actually Tested
The clearest new fact was Mitsui’s Q1 2027 report. Revenue reached ¥4,347,565m and net income was ¥294,052m, with net margin at 6.8% versus 5.8% in Q1 2026. That supported the optimistic view on profitability more than the cautious case on margin pressure. The period still left long term fossil fuel risk unresolved, so the evidence cut both ways.
The hinge assumption here was not sentiment but profit quality. For another company, it is worth checking whether rising margins and absolute earnings show up in filings alongside any energy transition story before placing too much weight on the upbeat case.
What Mitsui’s Price Already Assumes After A 38% Run
Mitsui now trades at ¥5,042, with this selected Narrative viewing Fair Value as below that level. The focus has shifted from broad growth hopes to whether cash generation can keep pace with higher expectations after the 38.4% gain over the past year.
For today’s price to hold up, a buyer would need to assume Mitsui turns its energy transition projects and capital allocation plan into steady cash flows, despite fossil fuel exposure and LNG linked volatility.
"While Mitsui is presenting disciplined capital allocation around MTMP2029 and committing over 50% of COCF to shareholder returns, the prior JPY 101.4 billion fall in Energy segment COCF linked to non recurring LNG dividends shows that if new projects do not generate steadier operating cash, the combination of high payout and volatile resource cash flows could strain reinvestment capacity and pressure future COCF sustainability."
The price and this Narrative do not agree. → Uncover what this Narrative says Mitsui is actually worth
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 18% below our estimate - targets long tail elevator fleets with retrofit contracts bundling monitoring, maintenance and media services.
- Company 2 - 38% below our estimate - focuses on specialist and mid management recruitment as clients shift hiring to external advisers.
- Company 3 - 34% below our estimate - supplies outsourced engineers and cloud tools as clients modernise mobility, insurance and banking platforms.
That is three of the list. See the full list of 23 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com