


EN
Can Fanuc (TSE:6954) Justify Its Valuation Following Buybacks Dividend And New Guidance?
Fanuc (TSE:6954) has put capital returns front and center, unveiling a new share repurchase program, a higher interim dividend, and fresh full year earnings guidance that together sharpen the stock’s investor appeal.
Fanuc’s new capital return package arrives after a mixed run in the share price, with the stock down 10.8% over the past 90 days yet still delivering a 25.2% total shareholder return over one year and 65.9% on a three year basis. This suggests earlier optimism has cooled recently as investors reassess growth prospects and risk around the ¥5,908 share price.
Capitalize on Fanuc's focus on capital returns by scanning a curated set of automation peers through our 96 robotics and automation stocks, which may be setting up for their next move.Fanuc has reset the narrative around its stock with richer capital returns and fresh guidance, yet the price is still well below its recent highs. Does that shift the decision toward buying now or waiting for a cheaper entry?
Preferred P/E of 27.4x for Fanuc: Is it justified?
On valuation, Fanuc trades on a P/E of 27.4x, which sits well above several reference points and raises questions about how much optimism is already reflected in the ¥5,908 share price.
The P/E ratio compares what investors are paying today for each unit of current earnings. For an automation specialist like Fanuc, this usually captures expectations around long product cycles, demand for factory robots, and the quality of profits that come from high margin equipment and services rather than short term trading gains.
Here the gap is clear. Fanuc’s P/E of 27.4x is described as expensive versus the peer group average of 21.6x and also higher than an estimated fair P/E of 23.6x that the regression based fair ratio suggests the market could lean toward. That points to investors paying a premium relative to both similar companies and the level the data driven model flags as more balanced.
The comparison with the broader JP Machinery industry is even starker. The sector average P/E sits at 12.5x, less than half Fanuc’s 27.4x valuation multiple, which signals the stock is priced much richer than the typical machinery listing in Japan.
Explore the SWS fair ratio for Fanuc.
Result: Price-to-Earnings of 27.4x (OVERVALUED)
Still, the premium P/E leaves Fanuc exposed if automation demand softens or if earnings growth lags behind the richer capital return story that investors are now focused on.
Find out about the key risks to this Fanuc narrative.
Another View On Fanuc’s Value
The P/E premium is only one lens. Our DCF model points to a future cash flow value of ¥4,530.88 per share, which sits below the current ¥5,908 price and frames Fanuc as overvalued on this method. Which signal would you lean on when the two do not line up?
Look into how the SWS DCF model arrives at its fair value.
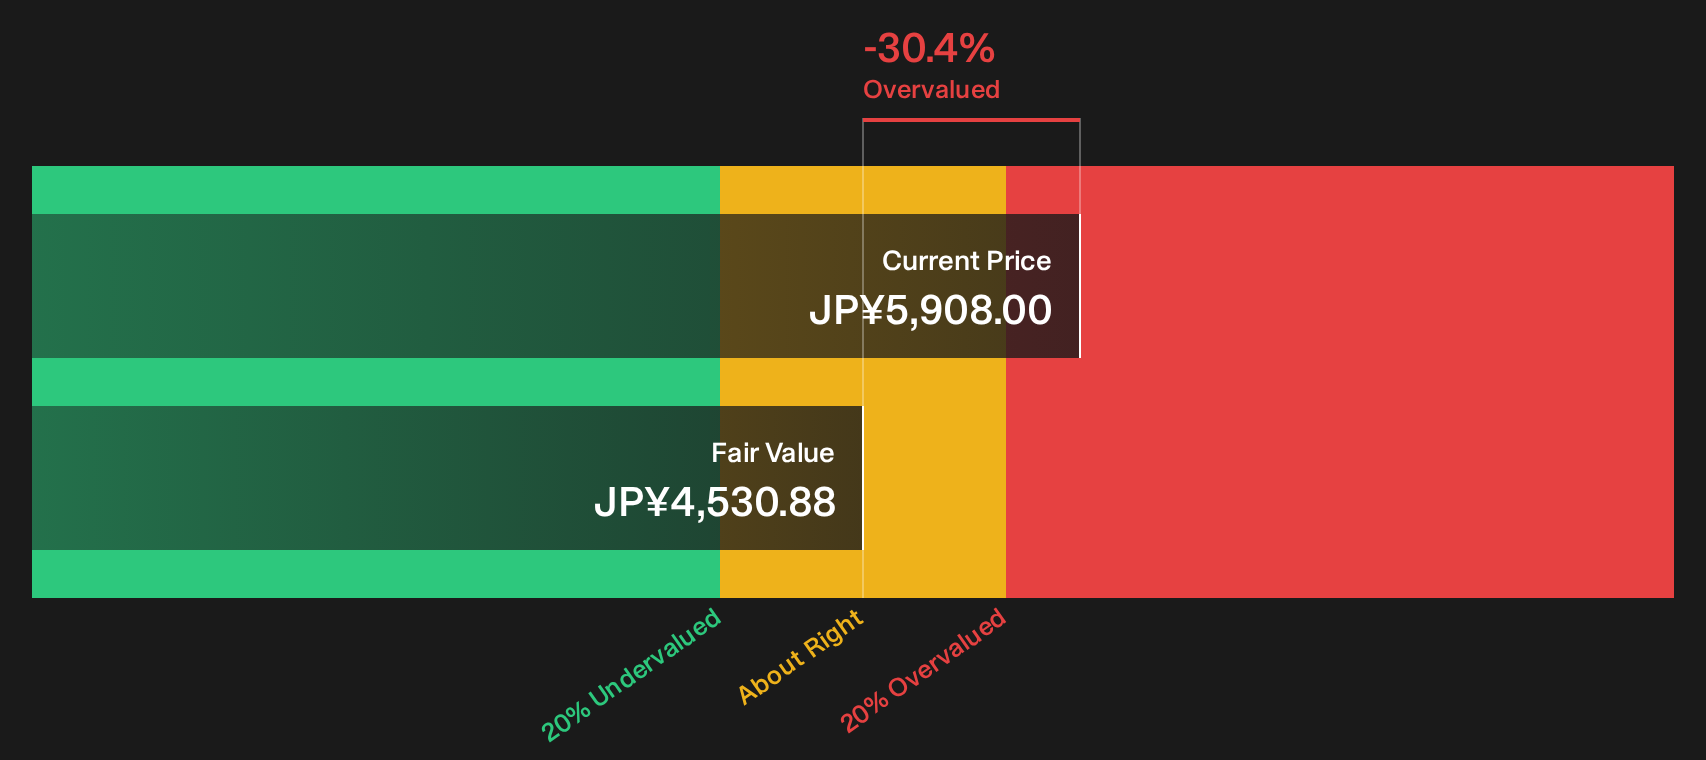
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Fanuc for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear message for Fanuc investors? If you want to move fast and base your call on the underlying data, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Fanuc?
If Fanuc has sharpened your focus on quality and price, do not stop here. Use focused screeners to surface other opportunities that match your investing style.
- Spot potential bargains early and scan a curated 72 high quality undiscovered gems that the wider market may not be paying close attention to yet.
- Prioritize resilience first and sift through a 24 resilient stocks with low risk scores that filters for businesses with steadier profiles and lower overall risk scores.
- Hunt for quality at a discount and review a list of solid balance sheet and fundamentals (23 results) that can help you focus on financially stronger companies instead of chasing every short term move.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com