


EN
Can Earnings Strength Change The Bull Case For AMETEK (AME)
- AMETEK recently drew attention after reports that the company is expected to post higher earnings and revenue for the September 2026 quarter compared with a year earlier, with the upcoming results closely watched by investors.
- The more interesting angle is how this anticipated earnings strength links back to AMETEK’s exposure to higher value instrumentation, secular demand areas and acquisitive growth platforms that are already central to its business story.
- We will now look at how AMETEK’s expected earnings strength, supported by recent upward analyst revisions, could influence its broader investment narrative.
Scan beyond AMETEK and line up other potential earnings beat candidates with the hand-picked 19 high quality undiscovered gems that analysts may not be fully focused on yet.
AMETEK Investment Narrative Recap
To own AMETEK, you need to believe its mix of higher value instrumentation, aerospace and defense, power, automation and medical platforms can keep earning attractive returns as demand shifts across these end markets. The near term story hinges on how well it converts its strong backlog and past design wins into steady orders and disciplined margins.
The upcoming September 2026 earnings release, with expectations for higher earnings and revenue, matters mainly as a check on that execution. The biggest short term swing factor is delivery against high expectations at a premium P/E. The key risk is that slower growth or flat margins could expose that valuation and compress the multiple.
The most relevant recent development is the cluster of upward earnings revisions and the expectation that AMETEK could again post results ahead of consensus for the September 2026 quarter. This directly ties into the investment case, since consistent outperformance helps support a richer valuation in a sector where investors already pay up for perceived quality.
If the company reports higher earnings and revenue as anticipated, attention quickly shifts to the sources. Investors will likely focus on contributions from AI related data center exposure, defense and aerospace programs, power infrastructure, and the integration progress on acquired platforms such as Indicor. Any sign that less discussed legacy areas dilute this performance would remain a core watchpoint.
What The Current AMETEK Forecasts Are Asking You To Believe
AMETEK's narrative projects US$11.3b revenue and US$2.3b earnings by 2029. Analysts build that view on 12.7% yearly revenue growth and an earnings increase of about US$700m from the current US$1.6b base.
Uncover why AMETEK's fair value indicates a 12% potential upside to its current price that could narrow quickly.
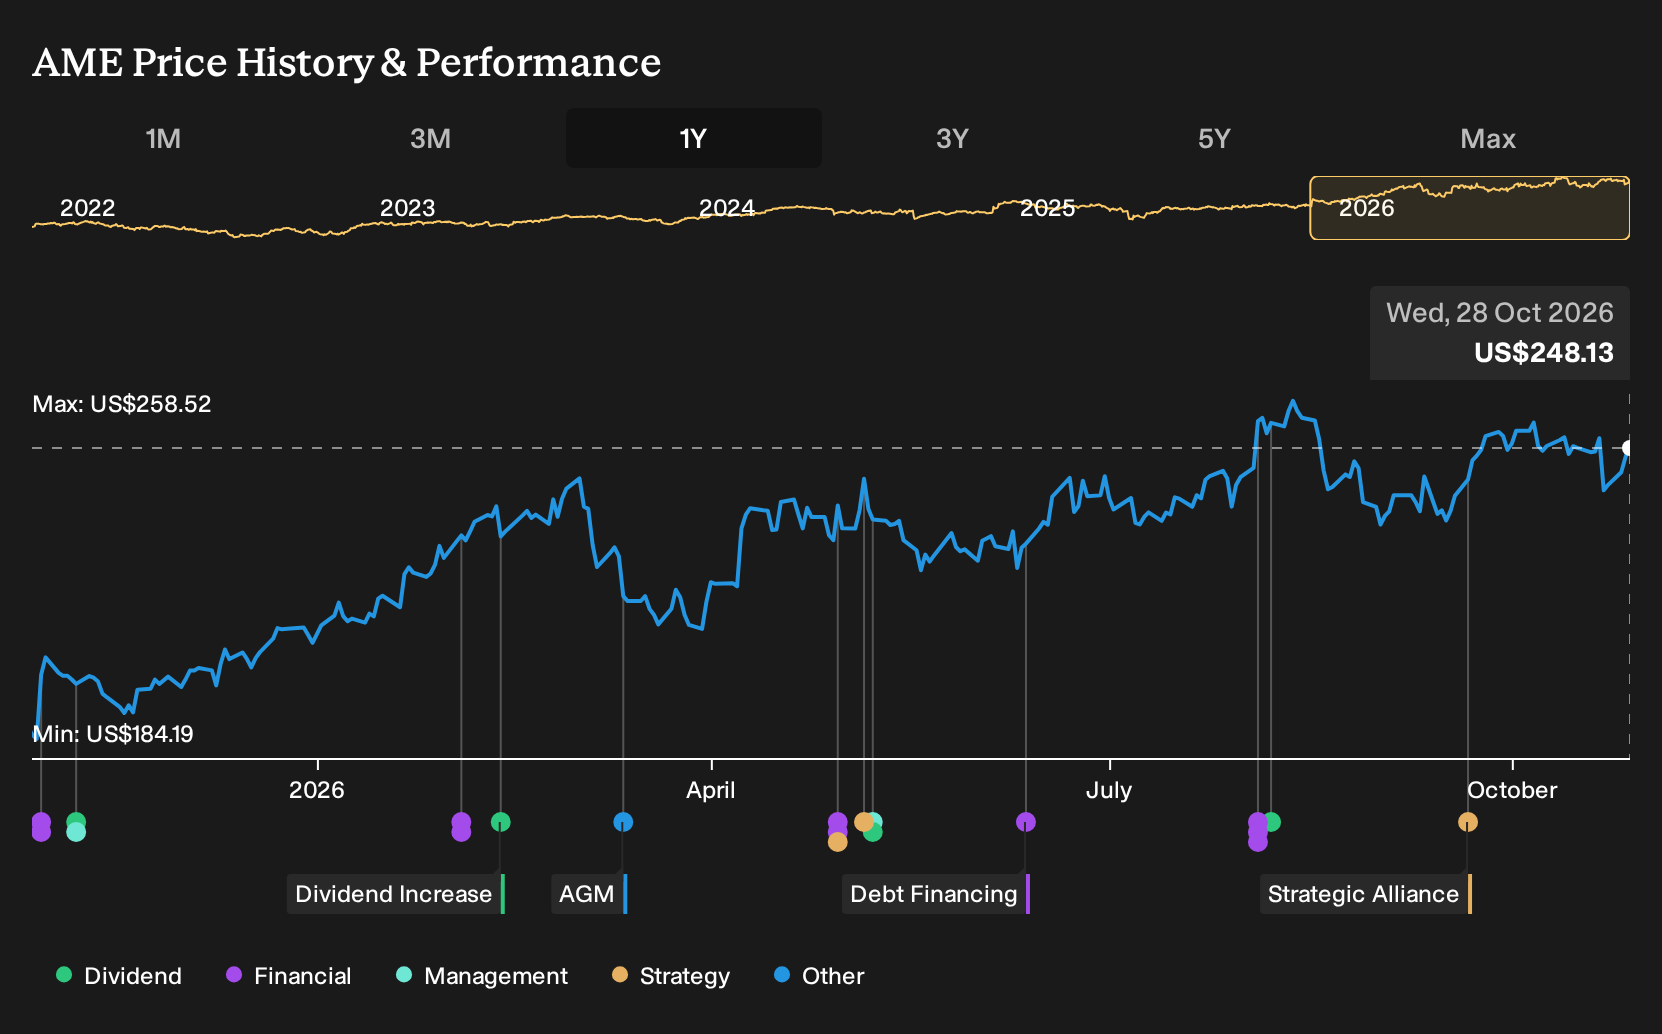
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$157 to US$278, so some investors see AMETEK as heavily undervalued while others price in a rich outlook. You are weighing that spread against premium P/E risk, where any reset in what buyers pay for industrials could matter more than near term earnings beats.
Explore 2 other AMETEK fair value estimates, including one that suggests as much as 37% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AMETEK research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for AMETEK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AMETEK's overall financial health at a glance.
Looking for more investment ideas beyond AMETEK?
Once you have formed a view on AMETEK, it can help to widen the field and compare it with other businesses that fit clear financial profiles using the Simply Wall St Screener.
- For investors who care most about quality at a reasonable price, scan a curated 26 high quality undervalued stocks that combine strong fundamentals with support from valuation checks.
- If dependable income is your focus, zero in on robust payers through a curated set of 6 dividend fortresses with yields that may appeal to dividend oriented portfolios.
- When capital preservation is front of mind, narrow the field to businesses that score well on risk factors using a tailored 32 resilient stocks with low risk scores that emphasizes resilience.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com