


EN
Did Earnings Beat Just Shift PriceSmart's (PSMT) Investment Narrative?
- PriceSmart reported fiscal 2026 fourth quarter revenue of US$1,516.27 million and net income of US$37.64 million, with full-year revenue of US$5,876.32 million and net income of US$166.59 million, alongside continued warehouse club expansion, including a new, sustainability-focused site in Montego Bay, Jamaica.
- Membership engagement, higher digital activity and premium tier uptake supported earnings, while rising technology and data project costs are pressuring operating margins and shaping how investors weigh PriceSmart's execution risk against its warehouse club rollout and market expansion, including its planned entry into Chile.
- This raises the question of how PriceSmart's investment narrative may be influenced by these earnings results and the new Montego Bay warehouse.
PriceSmart Investment Narrative Recap
To own PriceSmart, you need to believe in a membership club model that can keep pulling in steady traffic, renewing members at high rates and scaling into new markets without letting costs run away. The latest quarter delivered higher revenue of US$1,516.27 million and net income of US$37.64 million, which supports that basic idea rather than changing it.
The near term swing factor still sits in execution. Technology and data projects are lifting expenses and squeezing operating margins, while FX and supply chain pressures remain in the background. If these costs settle while new clubs ramp cleanly, the story looks constructive. If they do not, earnings volatility is the main risk.
The clearest operational announcement tied to this earnings beat is PriceSmart opening its third warehouse club in Jamaica on a five acre site in Montego Bay. That new location, with a 42,000 square foot sales floor, pushes more volume into the existing logistics network and leans into the membership density that already exists on the island.
This rollout, together with four additional planned clubs including the first site in Chile, is exactly where your catalyst and risk collide. Successful openings and steady member engagement can support merchandise sales and fee income, yet every added box increases exposure to local FX constraints, imported merchandise costs and the rising SG&A from supply chain and digital projects.
PriceSmart's narrative projects US$7.8b revenue and US$219.7 million earnings by 2029. This implies 11.2% yearly revenue growth and an earnings increase of about US$62.5 million from the US$157.2 million reported today.
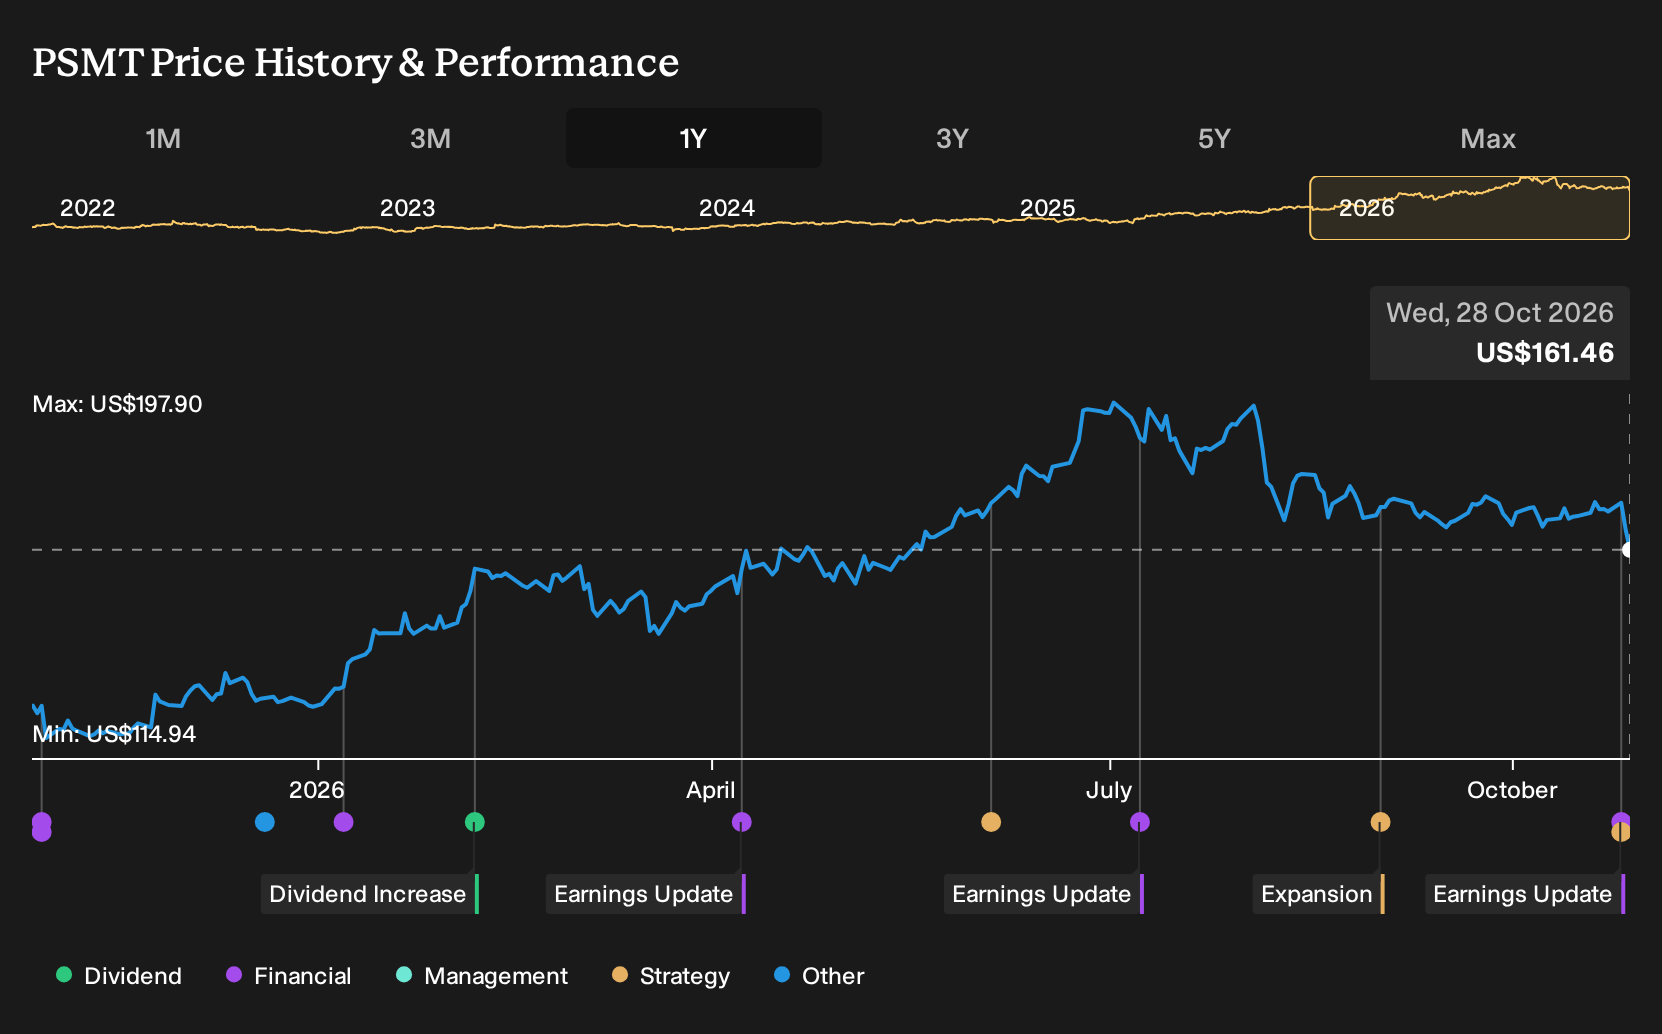
Discover why PriceSmart's fair value indicates a 12% potential upside to its current price, which could materialize sooner than the market expects.
Exploring Other Perspectives
One alternate view puts the Montego Bay opening and broader club build out at the center of the risk. The most cautious analysts worry that heavier fixed costs from Jamaica, Chile and new distribution hubs could strain returns. Before this report, some of them were only pencilling in about US$8.1b of 2029 revenue and roughly US$224.8 million of earnings, even though that still implied faster top line growth than the consensus path. That group saw PriceSmart as already pricing in strong execution, not offering a clear bargain. As you weigh these results, treat both the base case and this more pessimistic stance as moving targets, and explore several viewpoints before deciding how you want your portfolio to line up with PriceSmart’s membership model.
Explore 3 other PriceSmart fair value estimates, including one that suggests as much as 21% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PriceSmart research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PriceSmart. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate PriceSmart's overall financial health at a glance.
Looking For More Ideas Beyond PriceSmart?
If the PriceSmart story has you thinking about how to balance membership driven models with capital discipline, it can help to widen your watchlist and compare businesses with different strengths before committing fresh capital.
- If you want potential mispricing combined with solid fundamentals and cash generation, scan our hand picked 26 high quality undervalued stocks and see which stocks currently look out of sync with their underlying quality.
- For investors who care most about resilience and steady balance sheets, shortlist companies from the list of solid balance sheet and fundamentals (24 results) and focus on those that keep leverage and liquidity risk in check.
- If you prefer to keep risk contained while still hunting for opportunity, filter the market using our 32 resilient stocks with low risk scores and concentrate on businesses with more measured volatility and cleaner financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com