


EN
How Strong Q3 Results At Arcadis (ENXTAM:ARCAD) Have Changed Its Investment Story
- Arcadis reported third quarter 2026 results that included 4.3% organic net revenue growth, a 12.5% operating EBITA margin, and 7.9% organic backlog growth, while reaffirming full year guidance.
- The combination of higher backlog and a stronger margin profile signals that Arcadis is securing work on terms that appear more profitable and predictable than before.
- We will now look at how Arcadis' investment narrative could be influenced by the improved 12.5% operating EBITA margin reported for Q3.
Scan for other infrastructure and engineering stocks that show similar backlog resilience and margin profiles to Arcadis by starting with our hand picked list of solid balance sheet and fundamentals (203 results)
Arcadis Investment Narrative Recap
To own Arcadis, you need to believe the Reset program can keep shifting the mix toward higher margin Mobility and Resilience work while the weaker Places activities are kept under control. The Q3 operating EBITA margin of 12.5% and reaffirmed full year margin guidance suggest the operational playbook is currently tracking to plan rather than changing it.
The short term swing factor remains execution on backlog conversion at acceptable pricing. The current 7.9% organic backlog growth supports workload, but headwinds in real estate focused Places work and the time lag on cost savings still sit on the risk side. Q3 does not remove those issues, but it helps keep them contained.
The reaffirmed 2026 guidance for low single digit organic net revenue growth and an operating EBITA margin range of 11.7% to 12.0% is the announcement that matters most in the context of this Q3 update. It ties the higher 12.5% quarterly margin back to a full year frame and provides a clearer bar for judging execution.
For catalysts, that guidance range anchors how you assess whether backlog in energy transition, water and grid work actually turns into sustained profitability. The main operational risk is that ongoing Reset actions, including divesting lower margin activities and reducing roles, do not offset pressure in Places and real estate focused work, which could limit how much of that margin ambition Arcadis can deliver.
What Arcadis' Long Range Forecasts Assume
Arcadis' narrative projects €4.3 billion in revenue and €417.2 million in earnings by 2029. This aligns with analyst assumptions that revenue will decline by 4.6% per year and that earnings will rise by about €213.2 million from €204.0 million today as profit margins move from 4.2% to 9.8% over roughly three years.
Uncover why Arcadis' fair value indicates a 3% potential upside to its current price that could narrow quickly.
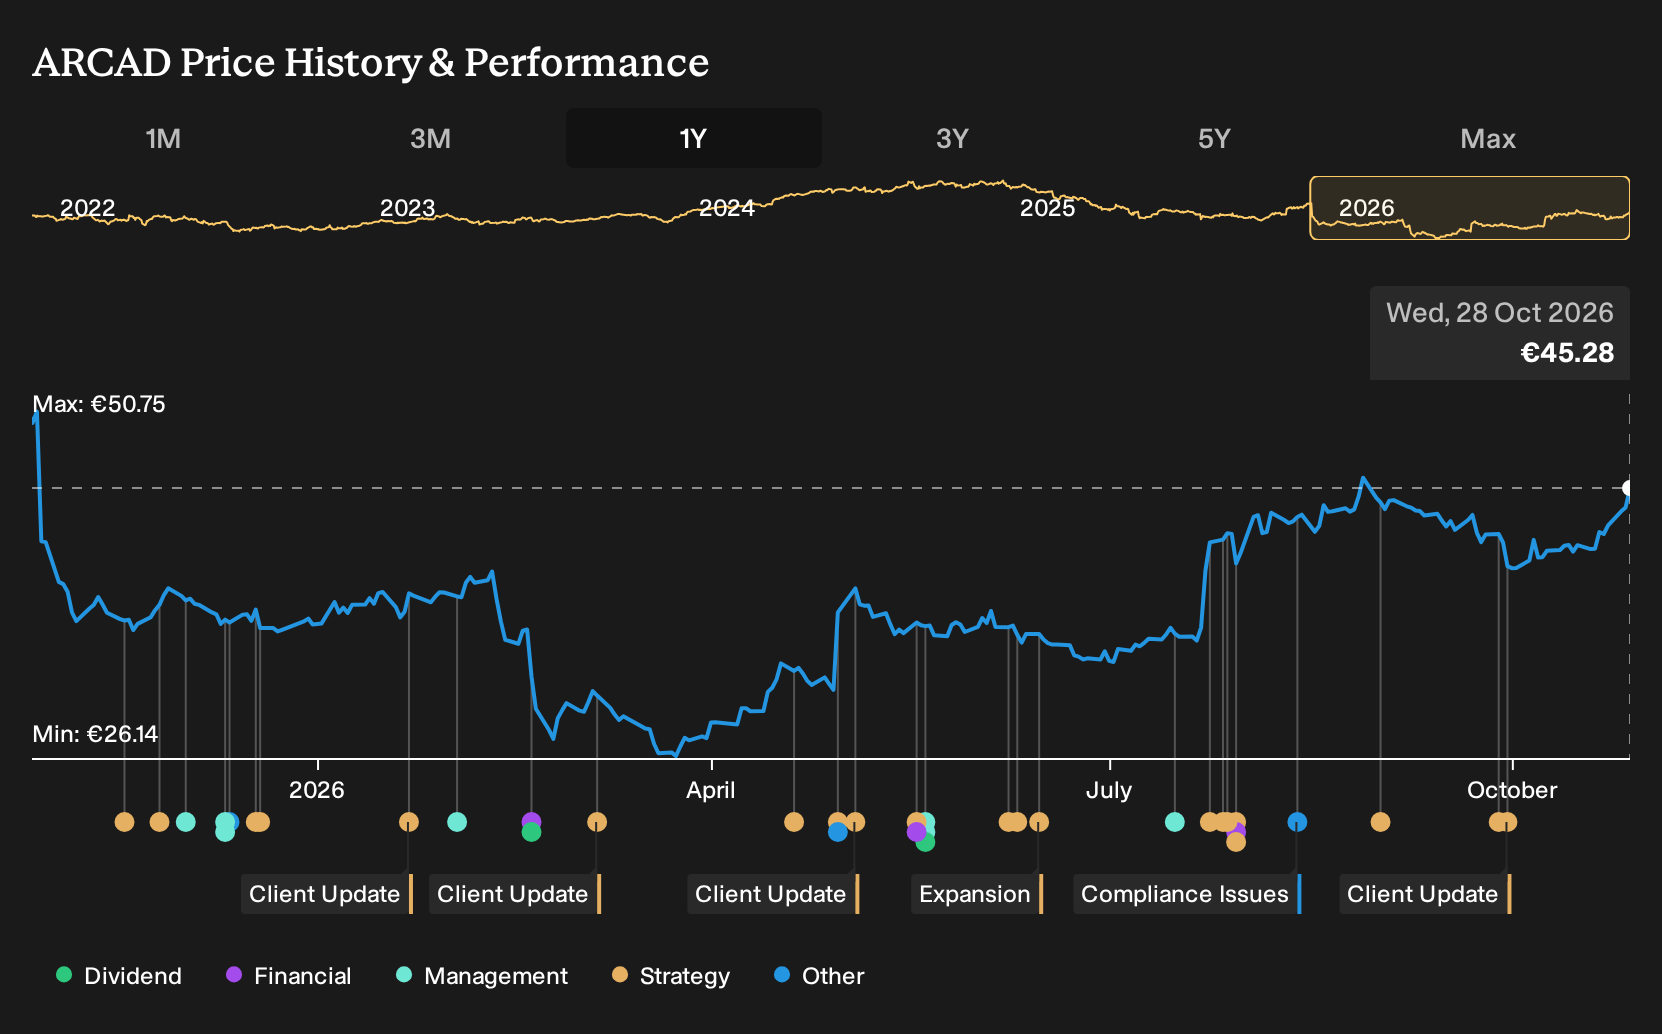
Exploring Other Perspectives
One alternate view on Arcadis focuses on slower revenue progress even if Q3 margins looked strong. The most bearish analysts were working off roughly €4.0b in 2029 revenue and about €325.4m in earnings before this update. That is well below the €4.3b and €417.2m embedded in the baseline story. You can treat this Q3 news as a fresh data point that might push those forecasts closer together or pull them further apart. The useful takeaway for you is that reasonable people can look at the same business and reach very different conclusions, so it is worth exploring several narratives before deciding what feels realistic.
Explore 5 other Arcadis fair value estimates, including one that suggests the potential for as much as 13% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own independent research.
- A great starting point for your Arcadis research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Arcadis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arcadis' overall financial health at a glance.
Looking for more investment ideas beyond Arcadis?
If the Arcadis story has sharpened your thinking, you can use that same lens on a broader watchlist. The Simply Wall St Screener lets you filter for balance sheet strength, valuation quality, and resilience so you can build a set of candidates that fit your own risk and return preferences.
- For investors who want potential upside with a margin of safety, start with a carefully filtered pool of quality companies trading below their assessed worth through the 191 high quality undervalued stocks.
- If income is a priority and you care about stability as much as yield, scan a curated group of higher yielding opportunities described as 226 dividend fortresses.
- When capital preservation matters most and you want businesses that score well on risk metrics, begin with a pre-vetted 228 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com