


EN
Is 3SBio (SEHK:1530) Undervalued As ESMO Data Strengthens Its Lung Cancer Story?
3SBio (SEHK:1530) drew fresh attention after presenting long term Phase II data for its PD-1/VEGF bispecific antibody SSGJ-707 at the 2026 ESMO Congress, highlighting progression-free survival benefits in advanced non-small cell lung cancer.
The fresh ESMO data landed after a tough stretch for 3SBio, with the share price down 21.14% over 90 days and 44.30% year to date, even though the three year total shareholder return of 109.48% and five year total shareholder return of 116.33% point to much stronger longer term momentum.
Spot 130 healthcare AI stocks that, like 3SBio, are pushing hard in oncology and complex biologics while the market focuses on short term share price pressure.3SBio now looks like a robust oncology platform owner caught in a sharp share price reset. The key issue for investors is whether that gap between business quality and current valuation is still wide enough to matter.
Preferred P/E of 3.5x: Is it justified?
On the numbers, 3SBio trades on a P/E of 3.5x, while the Hong Kong Biotechs peer group sits at 12.3x and analyst models and the SWS DCF model both point to a higher implied value than the current HK$13.69 share price.
The P/E ratio compares what you pay for each unit of earnings to what the rest of the sector trades on. For a profitable pharmaceutical group with HK$8,270.56 in net income, a low multiple can mean the market is pricing in weaker future profits, headline risk around trials, or concern about the durability of its portfolio.
Here the gap is wide. The stock is not only at a big discount to the Hong Kong Biotechs average multiple, it also trades below the estimated fair P/E of 8.2x that our regression based fair ratio suggests the market could move towards if sentiment and earnings expectations converged.
Explore the SWS fair ratio for 3SBio.
Result: Price-to-earnings of 3.5x (UNDERVALUED)
Still, the recent 12.7% revenue contraction and 41.9% decline in net income growth, alongside a 50.8% one year total return fall, keep execution and earnings risk front and center.
Find out about the key risks to this 3SBio narrative.
Another View on 3SBio’s Value
The earnings multiple paints one picture. The SWS DCF model offers another, with an estimated future cash flow value of HK$33.67 per share versus the current HK$13.69 price, which implies the stock screens as undervalued on that framework.
This gap suggests investors are pricing in heavy pressure on future cash generation, while the model points to more resilient value. The question is which story you trust when the next round of clinical data or policy news lands.
Look into how the SWS DCF model arrives at its fair value.
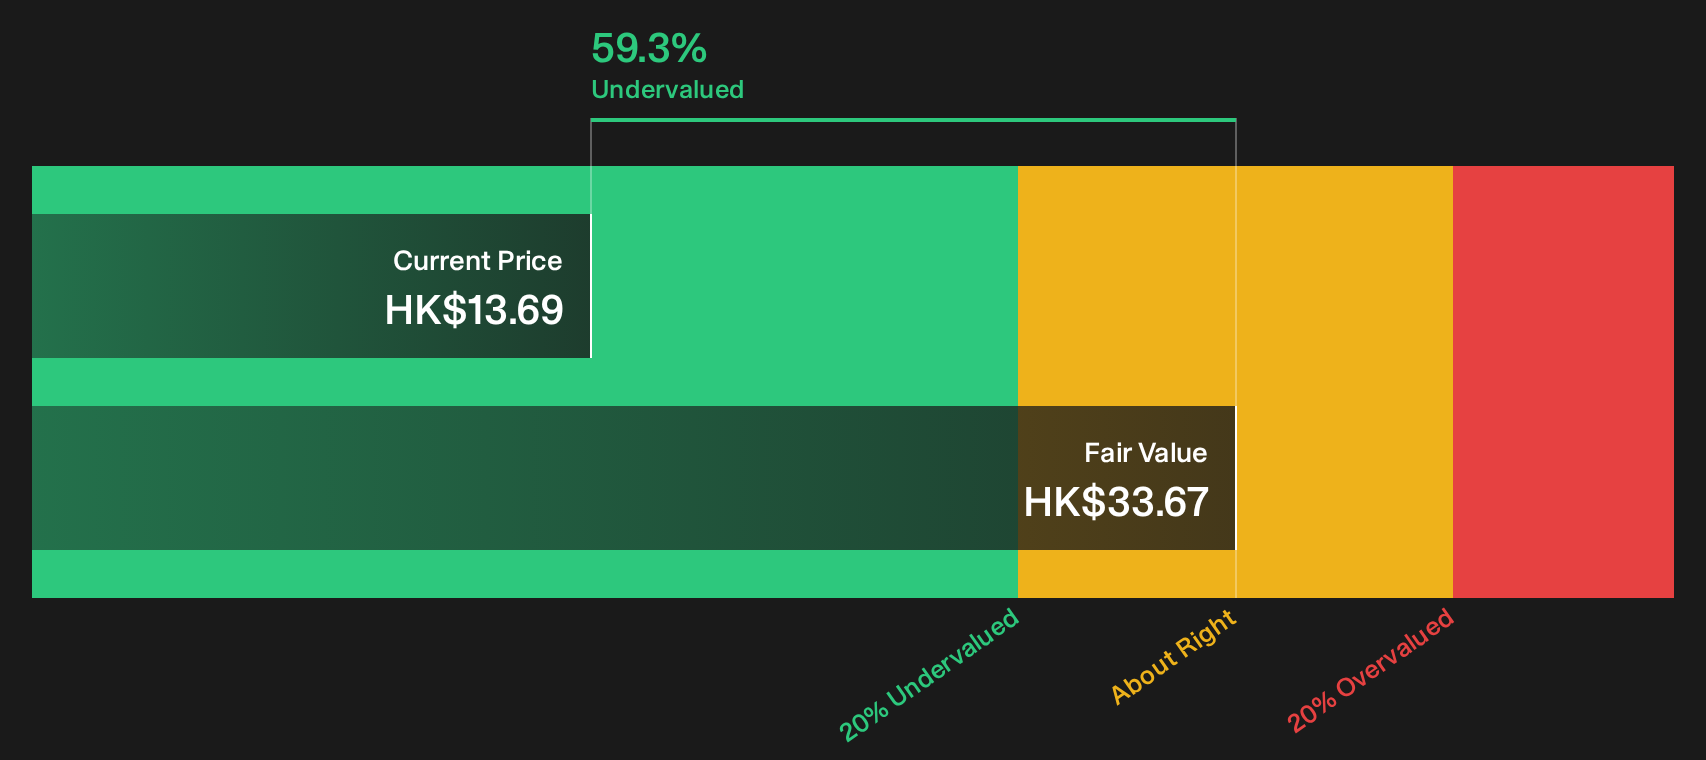
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out 3SBio for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment clearly split on 3SBio, you should move quickly, review the full data set, and weigh both sides through the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond 3SBio?
If 3SBio has sharpened your focus on valuation and resilience, it can pay to widen your watchlist using structured stock ideas built from clear fundamentals.
- Target potential mispricing by reviewing companies that combine solid cash flows with attractive valuations through the 191 high quality undervalued stocks.
- Rebalance toward stability by scanning for resilient businesses with lower risk profiles using the 228 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd notices by screening financially sound small and mid caps inside the 609 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com