


EN
Sezzle (SEZL) Moved, What Is Behind The Latest Attention?
Sezzle (NasdaqCM:SEZL) has moved to expand beyond its core buy now, pay later services by filing applications to charter Sezzle Bank, N.A. and secure FDIC insurance for consumer deposit products.
Recent trading has been choppy for Sezzle, with the share price falling 6.66% over the past week and 15.98% over the past 90 days, even as the 30 day share price return of 20.42% and year to date gain of 99.57% hint at strong upward momentum. This is supported by a one year total shareholder return of 99.78% and a very large three year total shareholder return that is above 80x.
Scan for other fintechs that are trying to turn strong user engagement into full banking relationships by reviewing our hand picked list of solid balance sheet and fundamentals (24 results).
Sezzle now trades at a clear discount to published analyst targets, even as its bank charter push adds fresh regulatory and execution questions. Is the gap mispricing or a fair warning label on the stock?
Most Popular Narrative: 31% Undervalued
On the most followed narrative, Sezzle is framed as worth $187.88 per share versus the last close at $130.02, which presents the current discount as a valuation gap rather than a warning sign.
Using a two-stage model with 10 years of +25.0% growth that then tapers to a 2.5% terminal rate and is discounted at 14.5%, the shares are valued at USD 187.88 compared with a market price of USD 111.38. This implies a 41% discount, or +69% to fair value.
The business reports a 52.4% return on invested capital, supported by a 40.4% operating margin and 74.6% gross margins. Out of USD 531.89M in trailing revenue, 61.6% converts into free cash flow, and the balance sheet shows debt at 0.52 times equity.
See why 3 investors see Sezzle as 31% undervalued.
Result: Fair Value of $187.88 (UNDERVALUED)
Still, any stumble in Sezzle’s bank charter bid, or a sharp shift in credit performance, could quickly challenge the underpricing story supporting this narrative.
Find out about the key risks to this Sezzle narrative.
Another View: Sezzle On Earnings Multiples
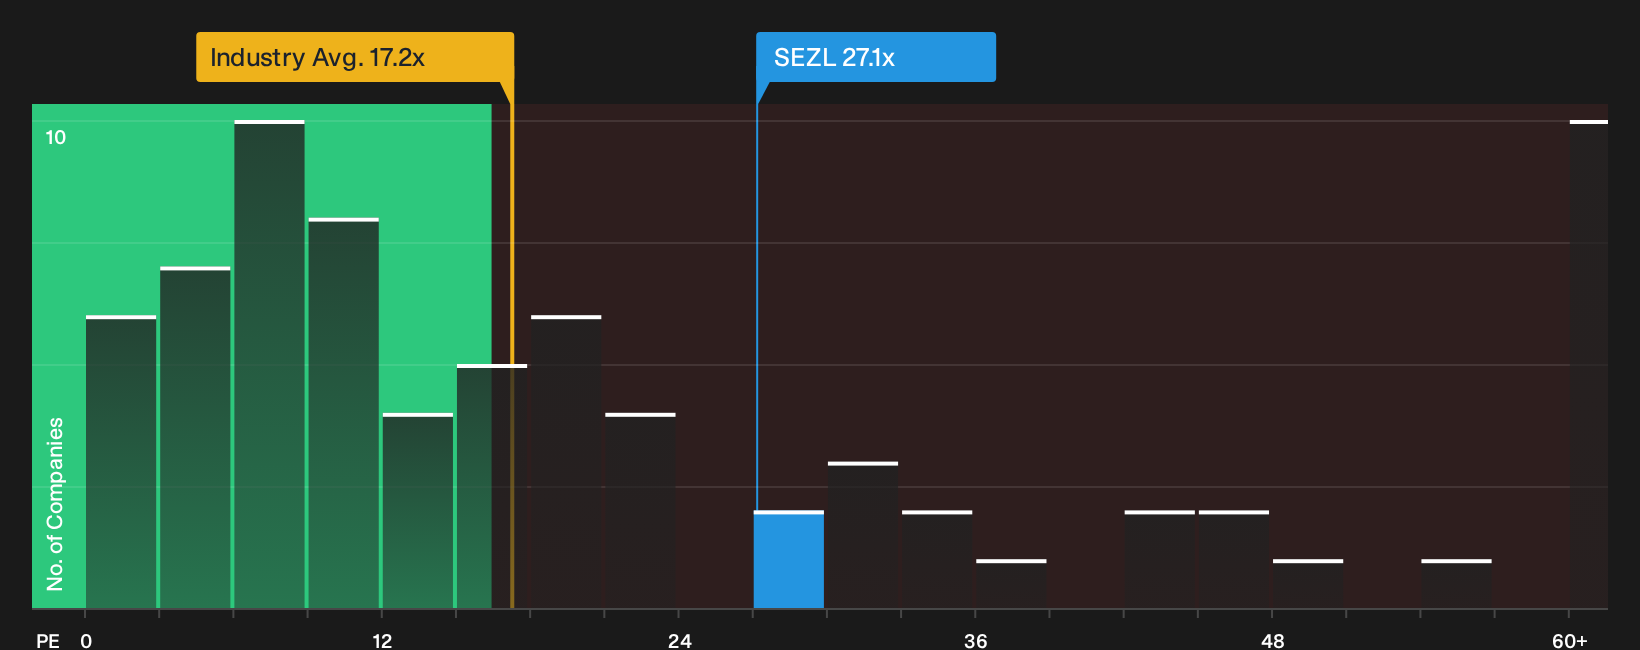
While one Sezzle narrative leans on a discounted cash flow output of $187.88 per share, the market is currently valuing the stock at a P/E of 27.1x. The broader US Diversified Financial industry trades around 17.2x, and a fair ratio for Sezzle is estimated at 22.3x, which points to a valuation premium that investors need to justify.
Peers on average change hands at 37.5x earnings, so Sezzle sits between the sector and that peer group. The gap to the fair ratio suggests less room for error if growth or profitability slow, which raises a simple question for anyone looking at the stock today: Is that extra multiple something you are comfortable paying for?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Sezzle’s valuation and risk profile can pull you in opposite directions, so move quickly, review the full data, and weigh both the 3 key rewards and 2 important warning signs.
Looking for more Sezzle investment ideas next?
If Sezzle has your attention but you want broader context, use the Simply Wall Street screener to explore other opportunities that may suit your approach.
- Identify potential mispricing by scanning companies that combine robust fundamentals with attractive valuations through the 26 high quality undervalued stocks.
- Focus on resilience by reviewing a 32 resilient stocks with low risk scores that may suit a steadier approach when you prefer fewer surprises.
- Look for possible future leaders by checking a 19 high quality undiscovered gems before they appear on more investors' lists.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com