


EN
ICL Stock Draws Heavy Put Options Activity As Traders Brace For A Big Event
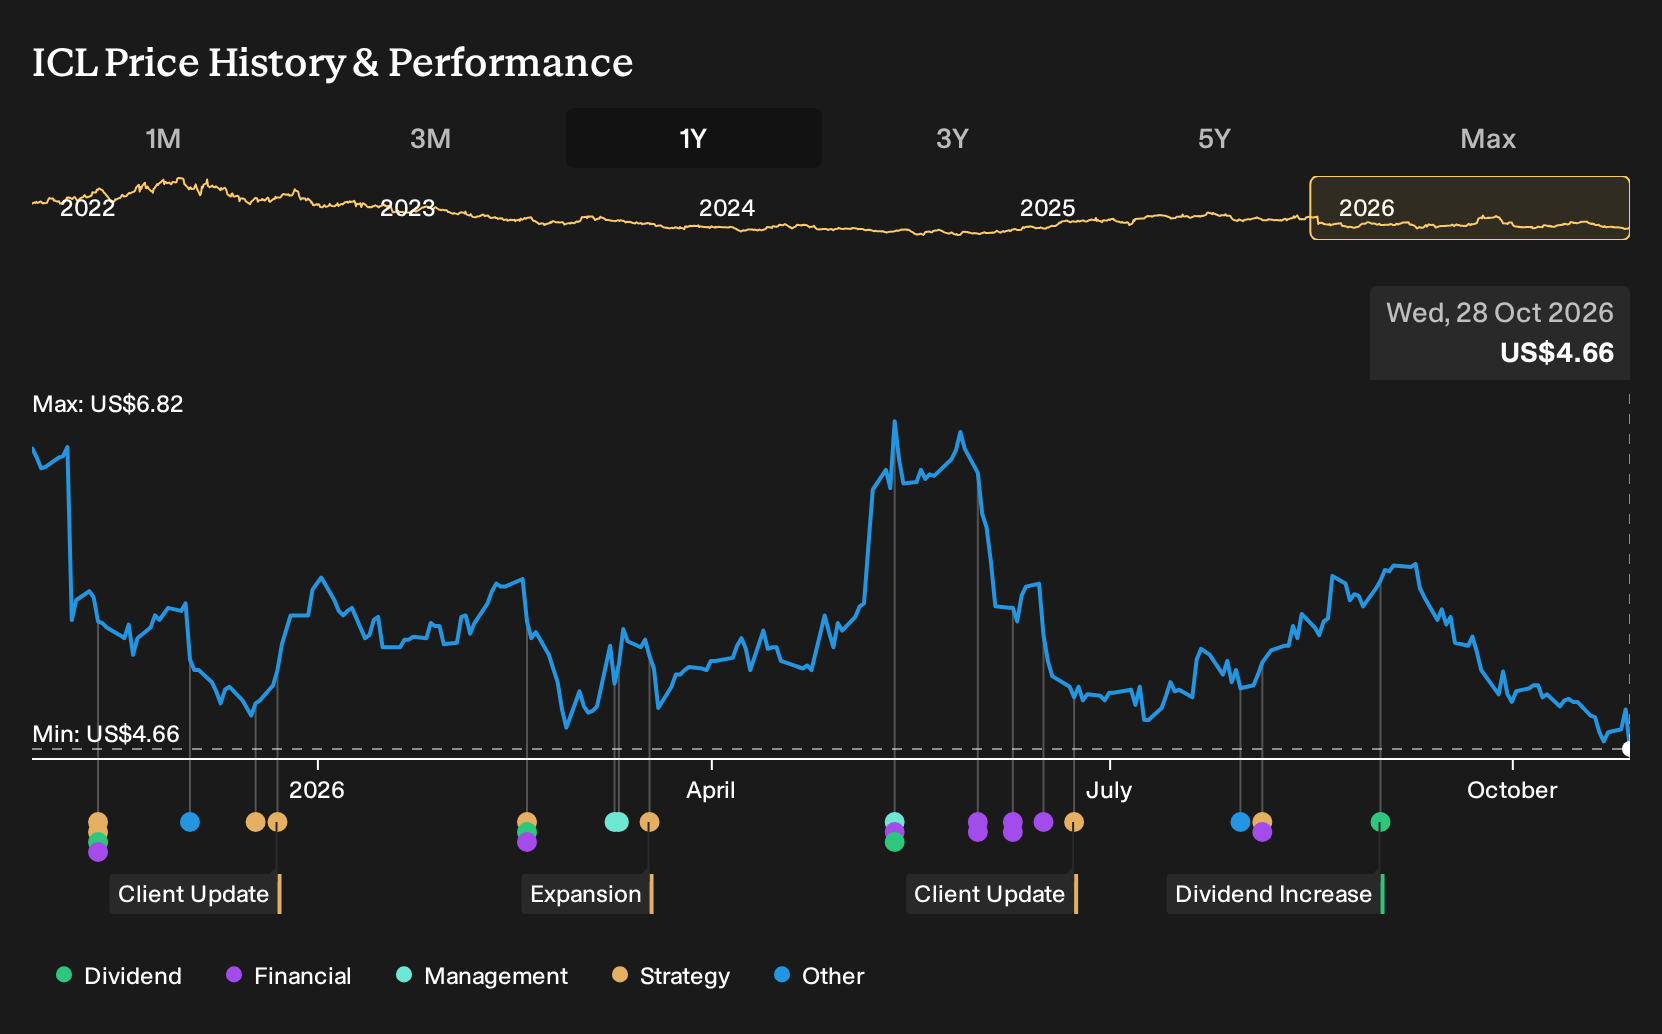
- Options trading in ICL Group recently showed unusually high implied volatility in specific put contracts, indicating traders are bracing for a sharp move in the underlying shares tied to a potential company specific event.
- This options spike suggests that the market is focused less on short term analyst caution and more on a possible change in ICL Group’s operating outlook or risk profile.
- The focus now turns to how ICL Group’s investment narrative could be affected by this surge in implied volatility around its options.
Scan how options traders are positioning around ICL Group and compare it with hand-picked companies facing similar turning points using the 32 resilient stocks with low risk scores.
What Is ICL Group's Investment Narrative?
To own ICL Group, you need to be comfortable with a minerals and specialty chemicals business that is capital intensive and heavily tied to demand and pricing in potash, phosphates and higher value downstream solutions. The investment pitch leans on a diversified segment mix and global end markets, plus a share price that currently trades about 45% below one estimate of fair value and below both US Chemicals industry and peer P/E averages.
The tougher part of the story is execution. Earnings have declined sharply over five years, recent profit margins are thinner than a year ago, and a high debt load and unstable dividend record add financial strain. The recent spike in implied volatility around ICL Group options points to the market bracing for a company specific development, which could reshape near term catalysts around earnings quality, capital spending plans or balance sheet flexibility, rather than leaving the narrative unchanged.
Even so, there is a less obvious pressure point in the ICL Group story that only really jumps out when you look closely at ...
There's only one way to know the right time to buy, sell or hold ICL Group. Head to Simply Wall St's company report for the latest analysis of ICL Group's Fair Value.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community put ICL Group between about $5.74 and $8.47, showing a wide gap between the most cautious and most optimistic retail models. Those assessments predate the recent options volatility, so use them as context and explore several alternative viewpoints before deciding how this setup fits your own thesis.
Explore another ICL Group fair value estimate, including one that suggests it could be worth just $5.74!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ICL Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for ICL Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ICL Group's overall financial health at a glance.
Looking For More Ideas Beyond ICL Group?
If this options activity around ICL Group has you thinking about portfolio upgrades, widen the lens and compare it with other businesses filtered by the factors you care about most using the Simply Wall St Screener.
- For investors hunting for quality at a discount, start with a curated pool of 26 high quality undervalued stocks that combine stronger fundamentals with appealing price tags.
- If resilience matters most to you, focus on balance sheets that look sturdier than average by scanning the list of solid balance sheet and fundamentals (24 results).
- Those who prefer to back quieter opportunities can review a hand-picked mix of 19 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com