


EN
3 UK Property Stocks To Watch If Interest Rates Start To Fall
UK growth forecasts are being nudged down for 2027 just as expectations build that interest rates may need to soften, and that mix is quietly reshuffling the appeal of rate sensitive UK stocks. Some businesses could feel the drag of a cooler economy, while others may benefit if borrowing costs ease. This article walks through three stocks that screens suggest could be positively exposed to this backdrop and explains why their stories matter now.
The stocks highlighted below are only a small sample of what screens are flagging, with the full filter surfacing 33 more UK rate sensitive equities across real estate and growth themes that carry similarly interesting stories. If you want to go straight to the source and identify your own highest conviction candidates, head into the UK rate‑sensitive equities (real estate & growth stocks) screener.
Regional REIT (LSE:RGL)
Regional REIT is a pure play on the UK regional office market. This makes its cash flows and balance sheet closely tied to shifts in domestic interest rates and investor appetite for income focused, rate sensitive real estate.
Regional REIT runs a UK commercial property portfolio outside the M25, earning about £73 million from commercial REIT activity, with all revenue coming from the UK, and the stock carries a market value of roughly £142 million.
"Intensifying shortage of high quality regional office space, as new developments stall and older stock is repurposed, may position Regional REIT’s upgraded assets for stronger pricing power and higher rental income growth over the medium term."
How pressures on its funding costs and rental mix evolve will be crucial for investors watching Regional REIT.
With that in mind, read the full narrative for Regional REIT to see how Regional REIT’s funding pressures, leasing trends and asset upgrades could be quietly decoupling from headline UK office sentiment.

Derwent London (LSE:DLN)
Derwent London is one of the purest ways to play UK rate sensitive real estate, with its fortunes closely tied to how investors price prime London offices as borrowing costs and long term growth expectations reset.
Derwent London is a central London office REIT focused on design led regeneration. It generates about £209 million from office buildings within a wider £412 million revenue base that is entirely UK sourced, and the stock carries a market value of roughly £2.1b.
"Acute undersupply of high-quality Grade A West End offices, with vacancy of about 1.4% and constrained speculative development, is likely to support sustained ERV growth and drive higher like-for-like rental income and earnings over the medium term."
What happens when that tight supply story meets a shift in long term rate expectations could be the swing factor for Derwent London’s earnings power.
If that rate reset really starts to bite, read the full narrative for Derwent London to see how Derwent London’s earnings story could be quietly accelerating beneath the surface.

Helical (LSE:HLCL)
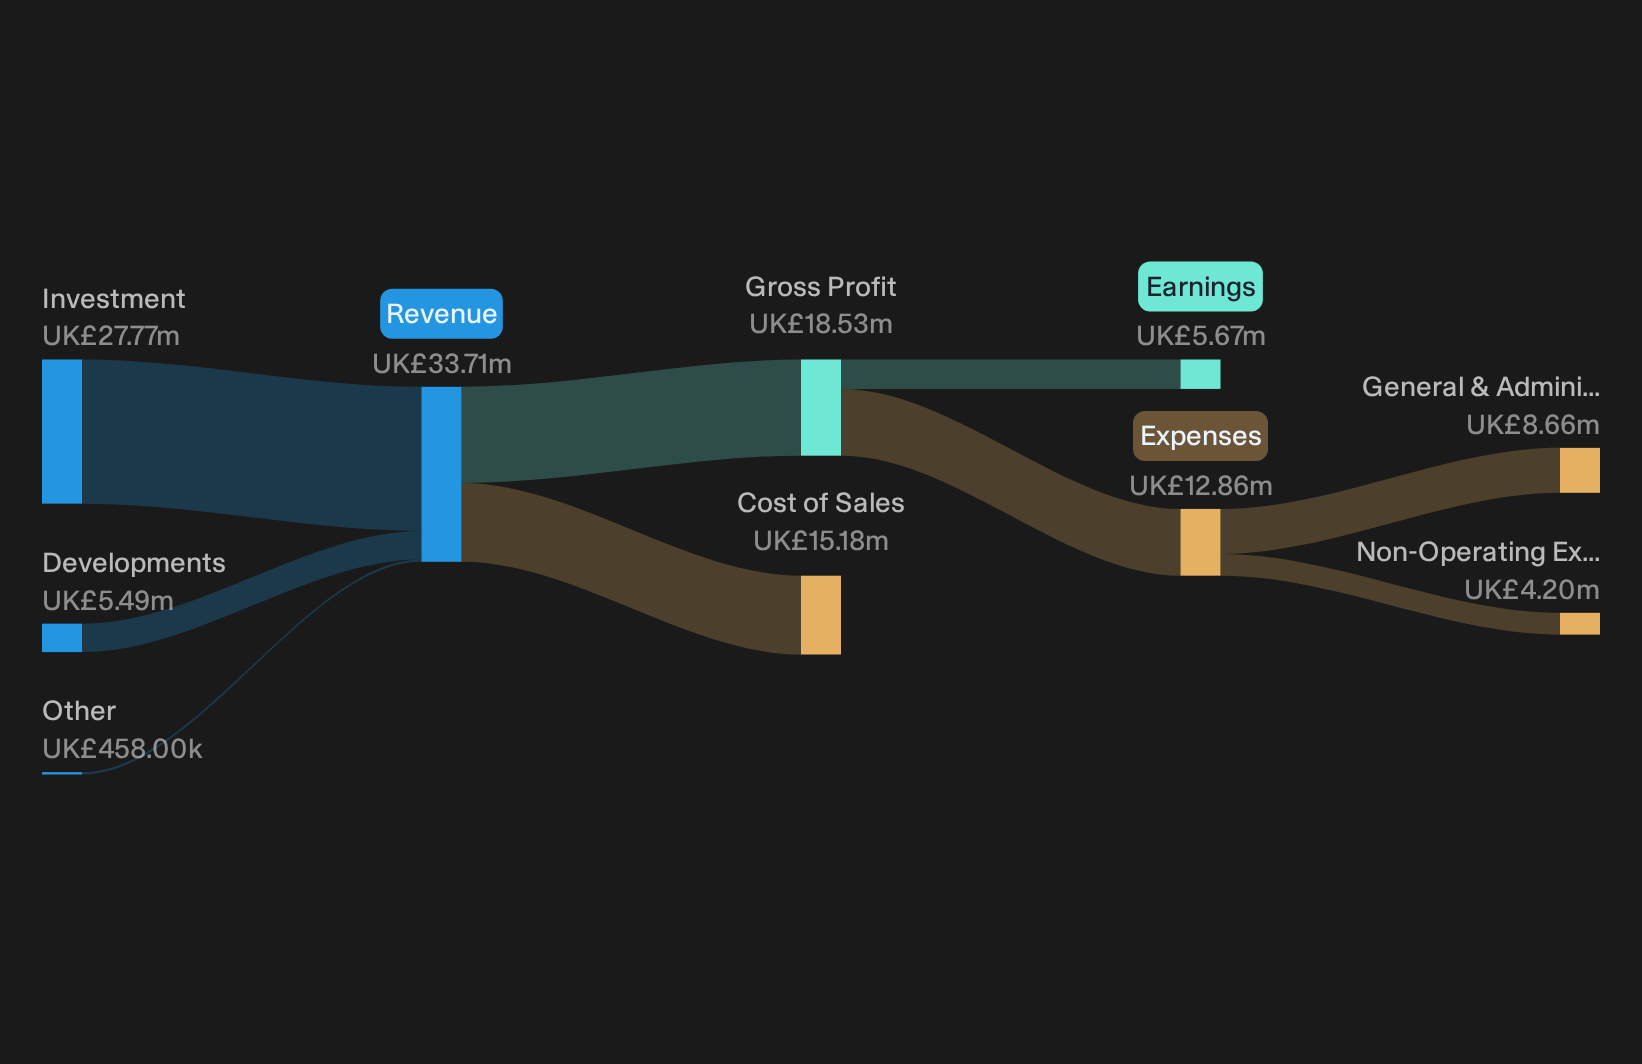
Helical plays directly into the UK rate sensitive real estate theme as a Central London office specialist focused on repositioning older buildings into higher quality space. It generated about £27.8 million from investment assets and £5.5 million from developments, and the stock is valued at roughly £219 million.
For rate focused investors, Helical ties the macro story on UK borrowing costs directly to the fortunes of high grade London offices. This makes what happens to demand and funding costs across its schemes a key test case for this screener.
"Rising demand for highly sustainable, well connected, amenity rich Central London offices alongside a severely constrained new build pipeline is expected to support materially higher headline and effective rents across Helical’s schemes, driving revenue growth and valuation gains."
The real question is how one less visible pressure on Helical’s financing mix and leverage ultimately feeds through to margins and shareholder returns.
That pressure point is exactly why the full narrative for Helical walks through how Helical could turn financing strain into accelerating upside if demand for top tier space keeps tightening.
Seeking Fresh Alternatives Before They Fly
Fresh opportunities move fast. The best breakout stories often gain momentum before the crowd even looks. Scan what others might miss while it still matters and get in early.
- Target resilient cash generators before they hit every watchlist by running a focused screen across the list of solid balance sheet and fundamentals (10 results).
- Spot potential income workhorses while yields are still being ignored by screening for high payout opportunities in the 4 dividend fortresses.
- Track early movers in decentralised finance and payment infrastructure by surfacing under the radar operators through the 20 cryptocurrency and blockchain stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com