


EN
Roche (SWX:ROP) Stock Looks Undervalued After Fresh Phase III Cancer Data
Roche Holding has delivered strong share price gains in recent years, and the question now is whether that market enthusiasm is supported by the earnings that underpin the business. With the stock recently closing at CHF 398.80, investors are increasingly focused on how its profit engine stacks up against what they are being asked to pay today.
- Over the past 3 years the Roche Holding share price has returned 86.0%, which puts real pressure on the valuation case to be grounded in the company’s earnings power rather than just momentum.
- Fresh late stage data in oncology and neuroimmunology together with new product approvals can shape expectations for future profitability, since they influence how durable Roche Holding's earnings base may be and how much investment is required to support it.
- There is a second opinion on Roche Holding worth weighing. See what analysts think Roche Holding's shares could be worth.
The stock's next move may depend on whether Roche Holding's current earnings justify the price implied by that recent share performance.
If you are weighing whether Roche Holding's recent 86.0% three year return lines up with its earnings, it can help to compare that question across 191 high quality undervalued stocks.
Is Roche Holding a Bargain on Earnings?
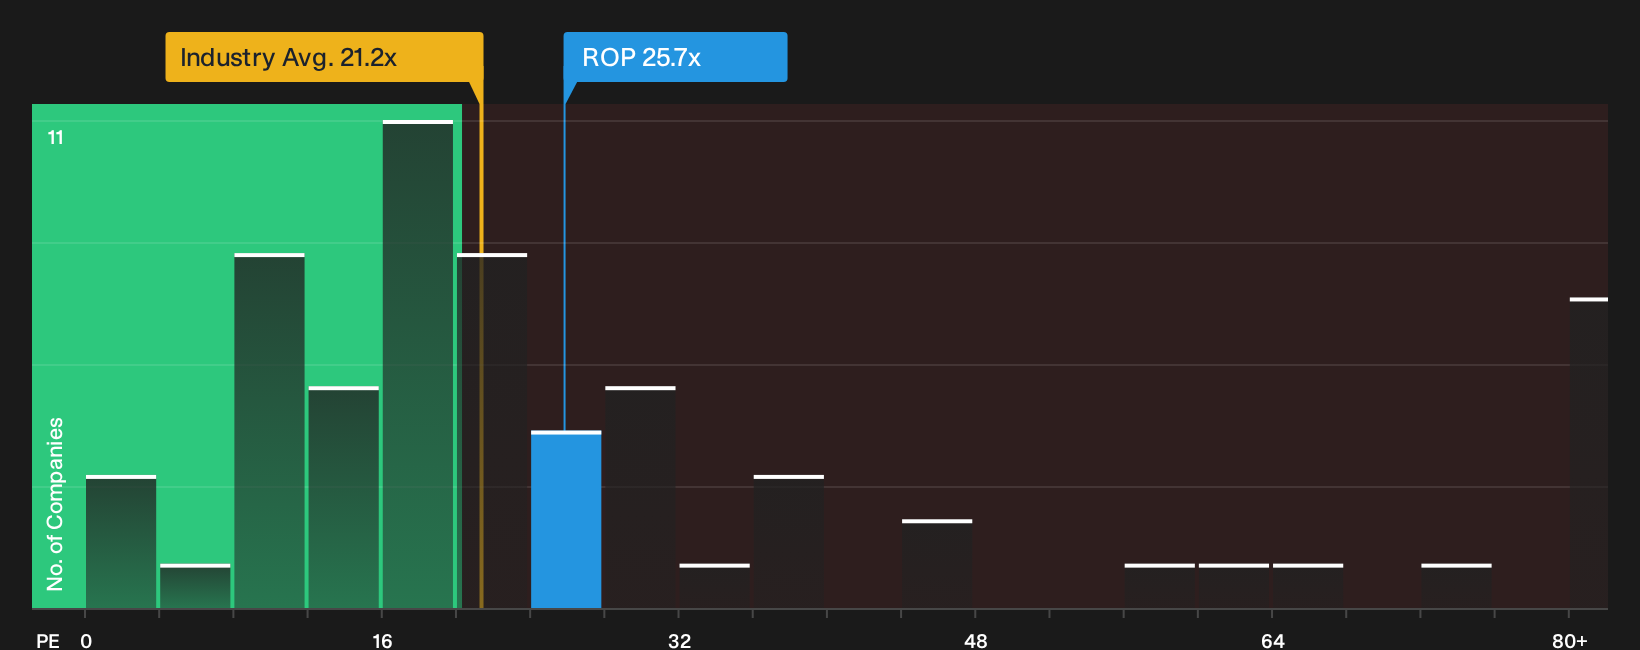
For a mature pharma group like Roche Holding, the P/E ratio is usually a straightforward way to see what the market is paying for each unit of profit. On this measure, Roche trades at around 25.7x earnings, which is above the broader pharmaceuticals sector average of roughly 20.6x but well below the peer set on about 48.1x. That gap to peers indicates that investors are not treating Roche as the most expensive large-cap pharma stock in its group, even after a strong run in the share price.
The tailored fair multiple for Roche, which takes its margins, growth profile, size and risk into account, is higher than the current 25.7x, so the shares screen as undervalued on this framework. Recent late-stage oncology data presented with Genentech, including Phase III results for divarasib, has sharpened focus on Roche Holding’s pipeline depth, yet the P/E still reflects a discount to what this model suggests might be justified for the earnings stream. Explore the numbers behind Roche Holding's P/E valuation.
The Roche Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that Roche Holding valuation question leaves off. They spell out which future paths for growth, margins and earnings would need to occur for the current share price to look materially cheap or expensive. Each one ties a fair value estimate to a clear storyline about Roche Holding's potential catalysts and key risks so you can track over time which version of the business outcome is actually unfolding.
Community views on Roche Holding are split between investors who see pipeline-driven upside and those who think the current price already reflects that potential.
Bull case: 9% undervalued
"A broad wave of late stage pharma assets, including up to 19 medicines that Roche aims to launch by the end of the decade, alongside 10 NMEs recently moved into Phase III, points to a richer mix of higher value products that can support group sales and core EPS over time…"
Discover why this Narrative puts Roche Holding at 9% undervalued.
Bear case: 13% overvalued
"Roche remains a top oncology player but faces increasing competition from more agile biotech firms…"
Explore why this Narrative puts Roche Holding at 13% overvalued.
One more angle on Roche Holding that could change the picture
Valuation only tells part of the story for Roche Holding, because the people steering the business and the way their incentives are set can heavily influence how that earnings base is used. See who runs Roche Holding and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com