


EN
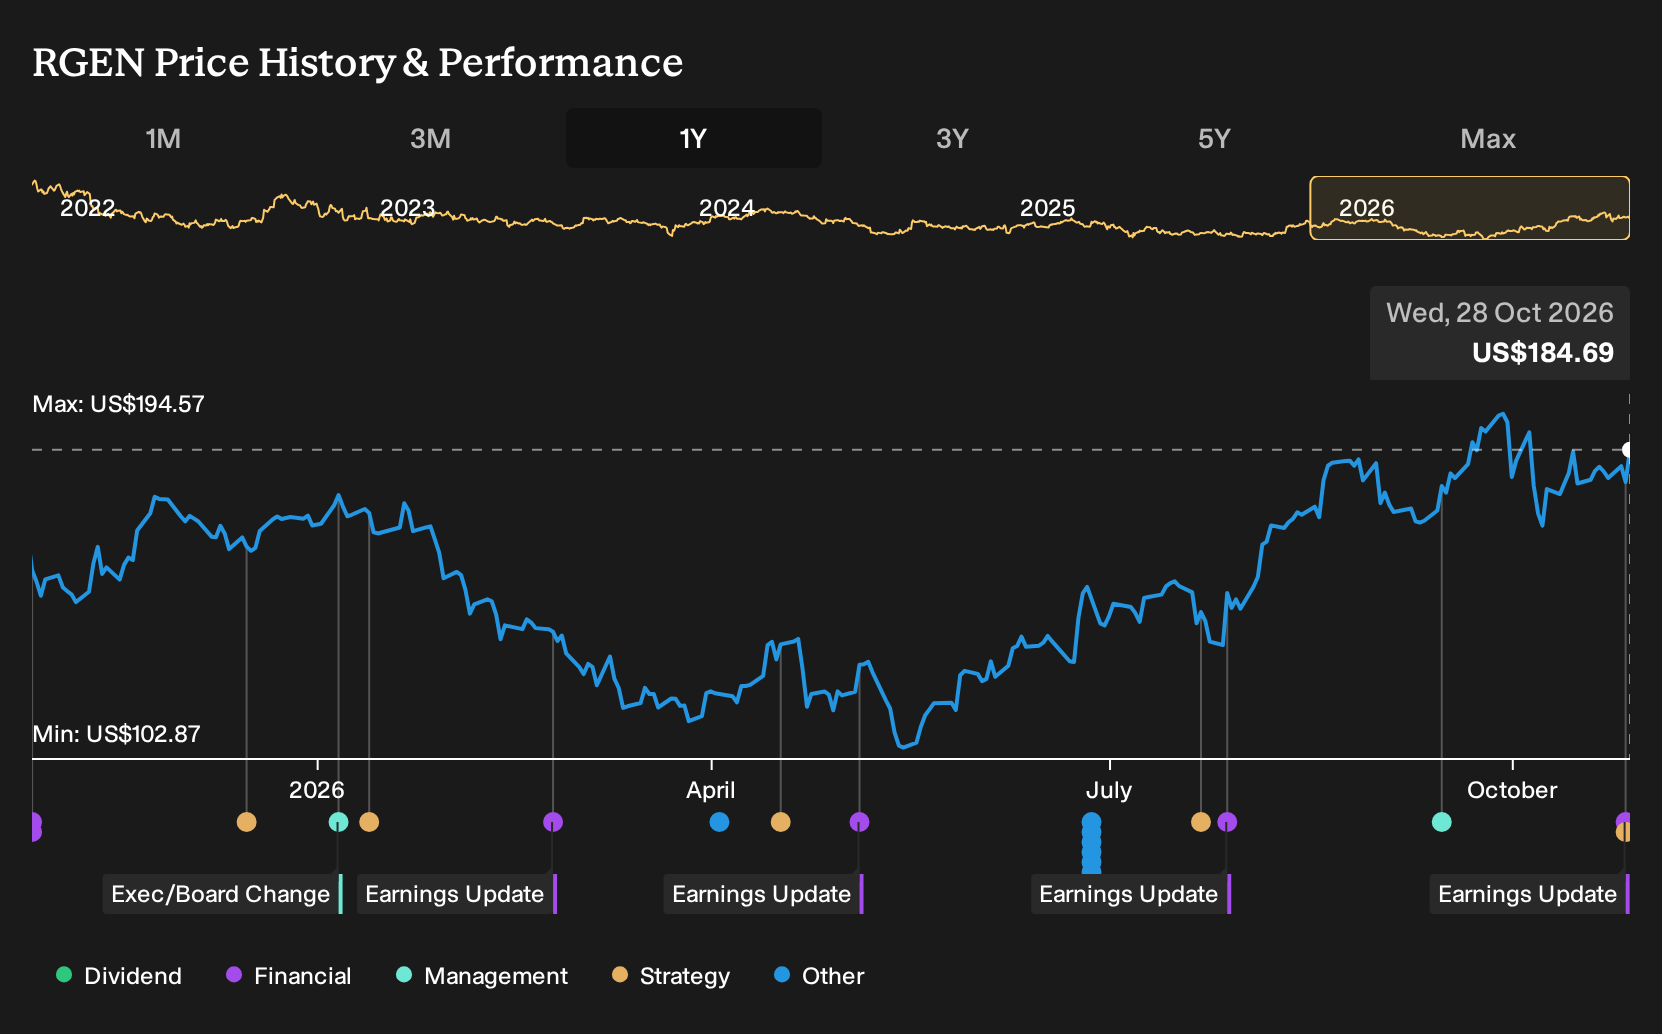
Why Repligen Stock Is Up 5.1% And What's Next After Record Revenue
- Repligen reported record Q3 2026 revenue of US$209.31 million and nine month sales of US$607.7 million, while moving from prior profitability to a quarterly net loss of US$38.43 million after substantial intangible asset impairment charges.
- Behind the headline loss, Repligen raised full year revenue guidance, with strength in proteins, chromatography, analytics and the recently acquired BioLife, which shapes a very different operational picture compared with the income statement alone.
- We will look at how Repligen's investment narrative is reshaped by record Q3 revenue and a sizeable intangible asset impairment.
Extend your research beyond Repligen by scanning a curated set of bioprocessing and life sciences peers with resilient balance sheets and cash flows using our list of solid balance sheet and fundamentals (24 results)
Repligen Investment Narrative Recap
To own Repligen, you need to believe the long thesis is about bioprocessing demand, not quarter to quarter accounting noise. Record Q3 2026 revenue of US$209.31 million and nine month sales of US$607.7 million point to a business still building around proteins, chromatography, analytics and now BioLife, even as reported net income swung to a loss.
The key near term catalyst is whether strong order trends and raised revenue guidance translate into sustained equipment and consumables demand from biopharma and CDMO customers. The biggest current risk is that funding pressure on smaller biotech and volatility in newer modalities caps that order momentum, while heavy spending and product mix shifts keep Repligen from converting higher sales into durable profitability.
The most relevant fresh data point for that thesis is Repligen booking Q3 intangible asset impairment charges of US$41.24 million. Those write downs turned what would otherwise have been a profitable adjusted quarter into a statutory net loss of US$38.43 million, even as basic and diluted EPS moved from earnings a year ago to a reported loss of US$0.68.
For you as a shareholder, that accounting reset matters less than the fact that management raised full year revenue guidance and continues to highlight strong order books across proteins, chromatography, analytics and capital equipment. The impairment concentrates attention on execution risk around acquisitions and product bets, while the raised outlook keeps operational momentum and demand trends squarely in focus as the main catalysts to watch.
Repligen's current earnings of US$41.5 million are set against analyst forecasts that call for revenue of US$1.3 billion and earnings of US$196.6 million by 2029. According to those forecasts, this would reflect revenue growth of 19.5% per year and an earnings increase of roughly US$155 million from today.
Uncover why Repligen's fair value indicates an 8% potential upside to its current price that could close faster than you expect.
Exploring Other Perspectives
One alternate view treats customer concentration as the real swing factor for Repligen, not just quarterly impairments. The lowest analysts already assumed only US$1.4b of revenue and US$182.1 million of earnings by 2029. That is a more cautious story than consensus, and this latest Q3 loss could push those opinions even further apart.
Explore 2 other Repligen fair value estimates, including one that indicates there could be as much as 13% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Repligen research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Repligen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Repligen's overall financial health at a glance.
Looking For More Investment Ideas Beyond Repligen?
Once you have a handle on Repligen, it can help to line it up against a few different types of opportunities. The Simply Wall St Screener lets you filter for the kind of balance sheets, cash flows, or income profiles that fit your own approach, so you can test whether Repligen truly deserves a spot next to your other holdings.
- If you prefer to start with resilience, scan companies that pair sturdy finances with measurable earnings power through our 32 resilient stocks with low risk scores.
- If value is your focus, compare Repligen against businesses that combine quality fundamentals with compressed valuations using the 26 high quality undervalued stocks.
- If income matters more to you than headlines, size up stocks offering substantial yields and robust payout support through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com