


EN
Kuros Biosciences Stock What Changed After 2026 Guidance Upgrade
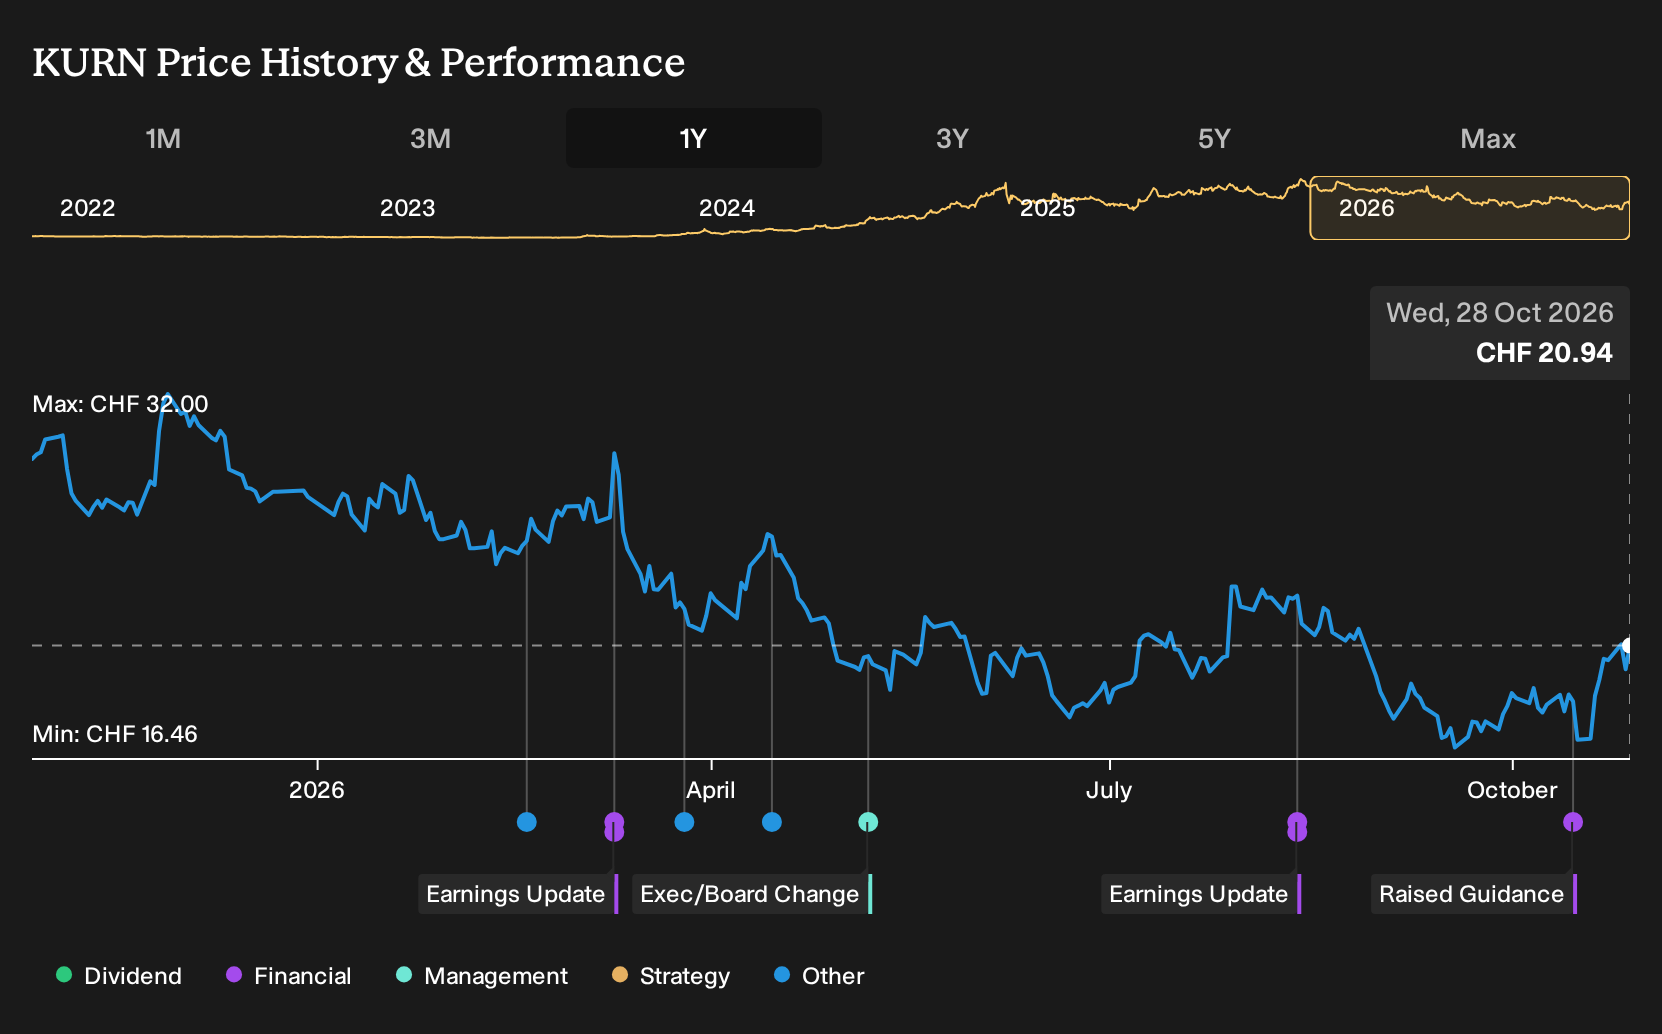
- Kuros Biosciences raised its full-year 2026 group earnings guidance in October 2026 and now anticipates sales growth between 36% and 40%.
- The upgraded outlook signals that management currently sees stronger demand for its synthetic bone graft portfolio and improved earnings visibility for the existing business.
- This article examines how Kuros Biosciences' investment narrative may change as higher 2026 sales guidance reframes expectations for operating leverage and profitability.
Scan how Kuros Biosciences' upgraded 2026 outlook compares with other potential earnings inflection stories by reviewing the hand-picked 199 high quality undervalued stocks.
Kuros Biosciences Investment Narrative Recap
Kuros Biosciences appeals to shareholders who buy into a simple idea. The business needs to convert clinical evidence and surgeon adoption in spine and extremities into sustained, high quality earnings from its synthetic graft portfolio. The raised 2026 guidance suggests management currently sees enough procedure volume and order visibility to support stronger short term operating leverage than previously outlined.
The near term catalyst is execution on manufacturing scale up and commercial reach in the U.S., since most revenue still comes from that market. The biggest risk remains any slowdown in procedure volumes or partner sell through, which could quickly pressure Kuros Biosciences' recently achieved profitability, even with higher sales guidance on the table.
The most relevant announcement here is the October 2026 revision, where Kuros Biosciences lifted full year 2026 sales expectations to 36% to 40% growth. That change speaks directly to how management views demand for MagnetOs and related graft products, and how confident they are in existing contracts and supply capacity into next year.
For catalysts, this upgraded outlook intersects with the longer term plans around a second U.S. production site, digitized planning systems and broader international expansion. Execution on those projects could influence whether current guidance proves a stepping stone or a ceiling. Any trade, reimbursement or supply chain disruption would test how resilient this higher 2026 range really is.
Kuros Biosciences' analyst narrative points to revenues of CHF 275.0 million and earnings of CHF 35.8 million by 2028, based on assumed yearly top line expansion of 38.6% and an earnings swing of about CHF 41.7 million from the current CHF 5.9 million loss to the 2028 consensus profit.
Uncover why Kuros Biosciences' fair value indicates a 57% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community currently span about CHF 32.8 to roughly CHF 131.7, so retail views on Kuros Biosciences differ widely. Examine these opinions, then weigh them against risks like procedure volume or trade setbacks, as well as potential catalysts around new sites and international expansion that could reshape future expectations.
Explore 2 other Kuros Biosciences fair value estimates, including one that suggests as much as 529% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kuros Biosciences research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kuros Biosciences. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kuros Biosciences' overall financial health at a glance.
Looking for more Kuros Biosciences sized ideas?
If you want to set Kuros Biosciences alongside other potential opportunities, use the Simply Wall St Screener to quickly surface stocks that fit different risk and quality profiles.
- For investors who care most about balance sheet strength and fundamental resilience, start with this curated list of solid balance sheet and fundamentals (207 results).
- If income is your priority and you want payouts that do more of the heavy lifting, focus your search with a targeted 223 dividend fortresses.
- When you are hunting for under the radar quality where expectations still look modest, broaden your watchlist with a focused 608 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com