


EN
This Financial Stock Just Raised Its Dividend by 17%
Dividend increases are back in fashion across the financial sector. Citizens Financial Group (CFG) recently raised its quarterly dividend by 13% after reporting a 29% year-over-year (YOY) increase in third-quarter net income, putting shareholder payouts and earnings growth in the spotlight.
Now, Ally Financial (ALLY) is joining the conversation. On Oct. 19, Ally announced a 17% increase in its quarterly dividend, lifting the payment to $0.35 per share. This is the company’s first raise since 2022 and arrived as Ally reported Q3 revenue of $2.33 billion, ahead of Wall Street’s expectations.
But does the bigger payout make ALLY a compelling stock to buy? Or do investors need to weigh more before collecting the dividend? Let’s take a closer look.
The Q3 Earnings Behind Ally's Dividend Increase
Ally Financial provides auto financing, digital banking, insurance, mortgages, and investment services, with a market capitalization of approximately $12.16 billion. Based in Detroit, Michigan, the company serves consumers and businesses through lending and deposit products, combining its automotive financing roots with a broader range of financial services delivered through digital channels.
ALLY stock closed at $38.72 on Oct. 27. Shares are down almost 15% on a year-to-date (YTD) basis and 5% over the trailing 52 weeks.
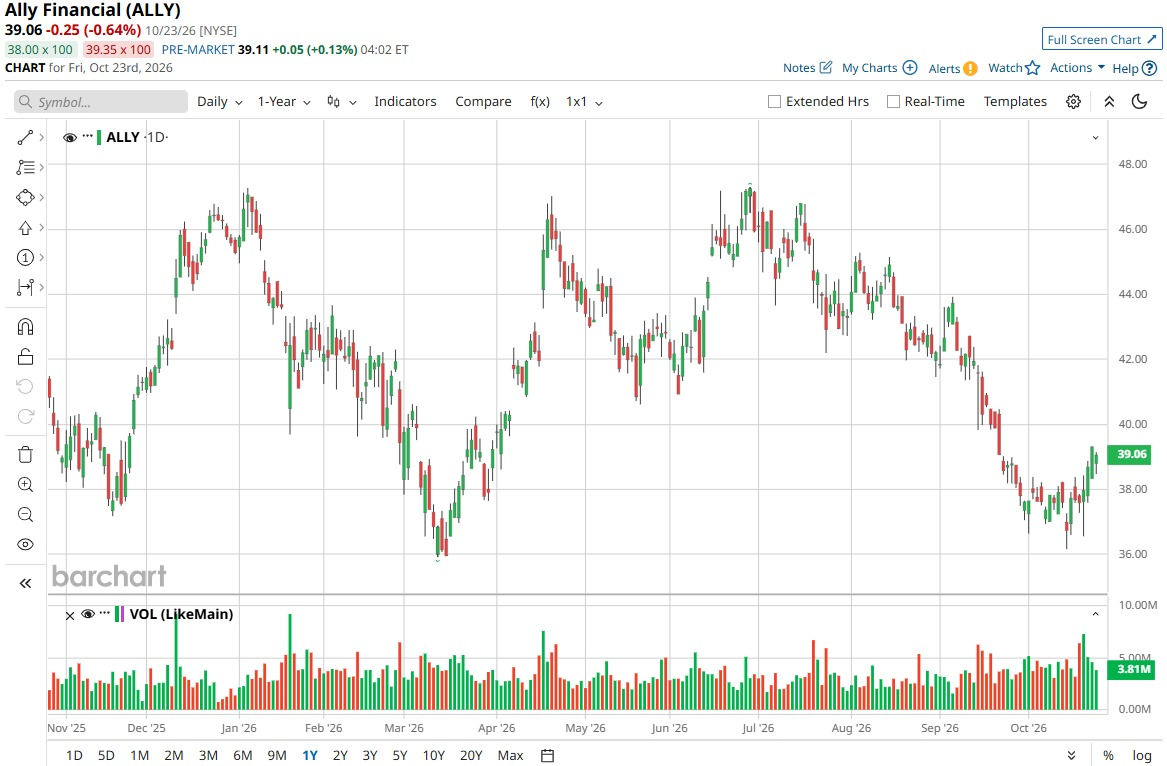
Ally Financial declared a 17% increase in its quarterly dividend on Oct. 19, raising the payout from about $0.30 to $0.35 per share. The increase brings its forward annual dividend to $1.40 per share, up from $1.20.
At 7.8 times forward earnings and 4 times cash flow — below sector medians of 11 times and 9.5 times, respectively — Ally offers a cheaper entry point than peers.
Ally Financial released Q3 fiscal 2026 results on Oct. 20, delivering GAAP total revenue of $2.33 billion, up 8% year-over-year (YOY) and above the $2.3 billion consensus forecast. This revenue beat follows annualized growth of 5% over the past two years, an improvement over the company’s five-year trend.
The company earned $1.30 per share on a reported basis, while adjusted earnings of $1.34 narrowly exceeded the $1.33 consensus estimate. Ally also matched expectations with a 3.6% net interest margin, indicating its lending spread performed as analysts anticipated rather than providing an additional earnings boost.
Its efficiency ratio offered a stronger result at 45.7% against expectations of 55.2%, meaning operating expenses consumed less revenue than analysts had projected. That difference amounted to roughly 948 basis points, although the favorable comparison should not be confused with an equivalent improvement from last year.
Ally’s tangible book value came in at $41 per share, unchanged from a year earlier and 6.3% below the $43.75 forecast. That was a weaker spot in a quarter marked by stronger revenue and better expense efficiency than analysts expected.
What Could Drive Ally’s Next Chapter
Ally is working to attract and retain customers through two connected initiatives. The company introduced “Life Today” on May 14, targeting how consumers save and spend. Developed with Anomaly LA, the campaign spans television, streaming, social media, and more, connecting everyday spending priorities with longer-term financial goals.
Ally Financial followed with Loyally on Sept. 22, launching its first loyalty program for bank and auto customers. The fee-free offering requires no minimum balances and avoids points-based redemptions. Customers access offers through the Ally app, while new customers can participate by opening an eligible account. Some individual perks carry annual values of up to $1,000, with opportunities for VIP experiences “valued at up to $10,000.”
These initiatives could help Ally attract customers and retain existing accounts, supporting the earnings needed to sustain its higher dividend. Their contribution remains unquantified, however, making customer growth and retention important measures to watch.
How Does Wall Street View Ally Financial Stock?
Ally’s next earnings release is scheduled for Jan. 20, 2027, covering the quarter ending December 2026. Analysts expect earnings of $1.37 per share, compared with $1.09 in the prior-year quarter. That represents projected growth of almost 26% YOY, pointing to stronger profitability following the company’s dividend increase.
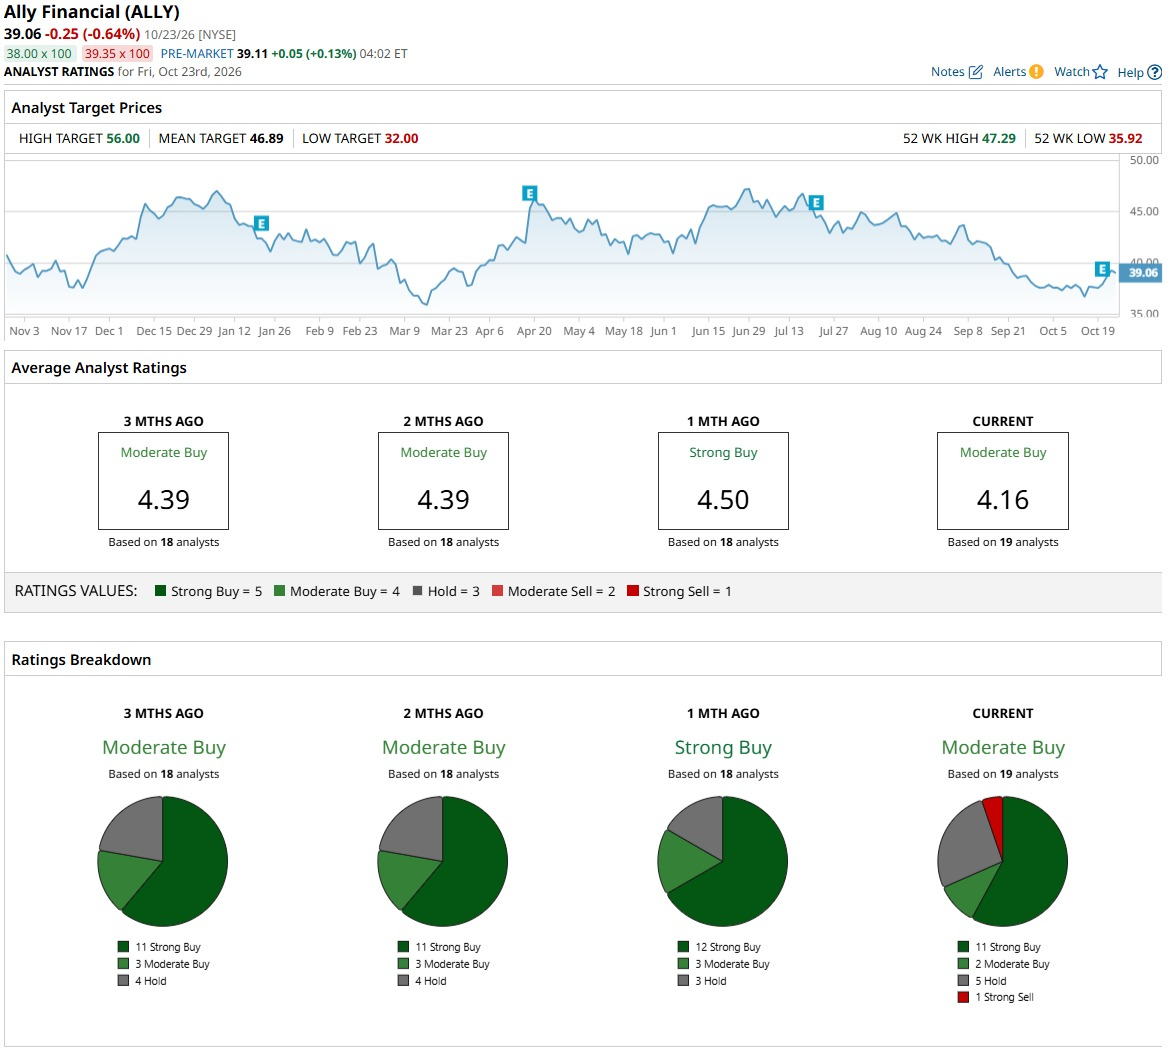
Based on 19 surveyed analysts, ALLY stock has a consensus “Moderate Buy" rating on Wall Street, reflecting a generally positive outlook. The average price target of $46.37 implies approximately 20% potential upside from current levels. That potential price appreciation, alongside the higher dividend, depends on Ally delivering stronger earnings.
Conclusion
Ally’s bigger dividend is a good reason to take a look, especially with revenue growing and the shares trading below sector averages. Earnings will probably improve gradually rather than send ALLY stock soaring overnight, so a bit of patience helps. Flat tangible book value is worth keeping an eye on, and analyst targets aren't guarantees. The stock looks pretty appealing at this price, but the real question is whether Ally can keep earning enough to back that bigger payout.
On the date of publication, Ebube Jones did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.