


EN
Riverview Bancorp (RVSB) Q2 Earnings Revive Profit But Skepticism Lingers
Riverview Bancorp just posted Q2 2027 numbers and the headline is simple. Profit is back on the quarter, and the story is about repair, not hype. Basic earnings per share landed at US$0.10 on revenue of US$15.5 million. Net income reached US$2.0 million, a clear contrast to the trailing 12 month loss picture that has kept many investors cautious.
The stock barely moved, slipping 0.5% to US$6.03, which signals a market that looks unconvinced or simply numb to incremental progress. Price stayed quiet while the income statement turned the volume up.
Like that Riverview Bancorp is back in the black but still uneasy about a turnaround that rests on a single quarter of profit. Use the list of solid balance sheet and fundamentals stocks (24 results) to benchmark this recovery story against banks and financial stocks with sturdier fundamentals.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): US$15.45 million vs. US$13.62 million (up about 13%)
- Net Income (Q2 2027 vs. Q2 2026): US$1.97 million vs. US$1.10 million (up about 79%)
- Basic EPS (Q2 2027 vs. Q2 2026): US$0.10 vs. US$0.05 (up about 89%)
- Net Interest Margin (Q2 2027 vs. Q2 2026): 3.34% vs. 2.76% (reflecting a higher margin on lending activity)
Ask Charlie what makes Riverview Bancorp’s growth forecast so aggressive.
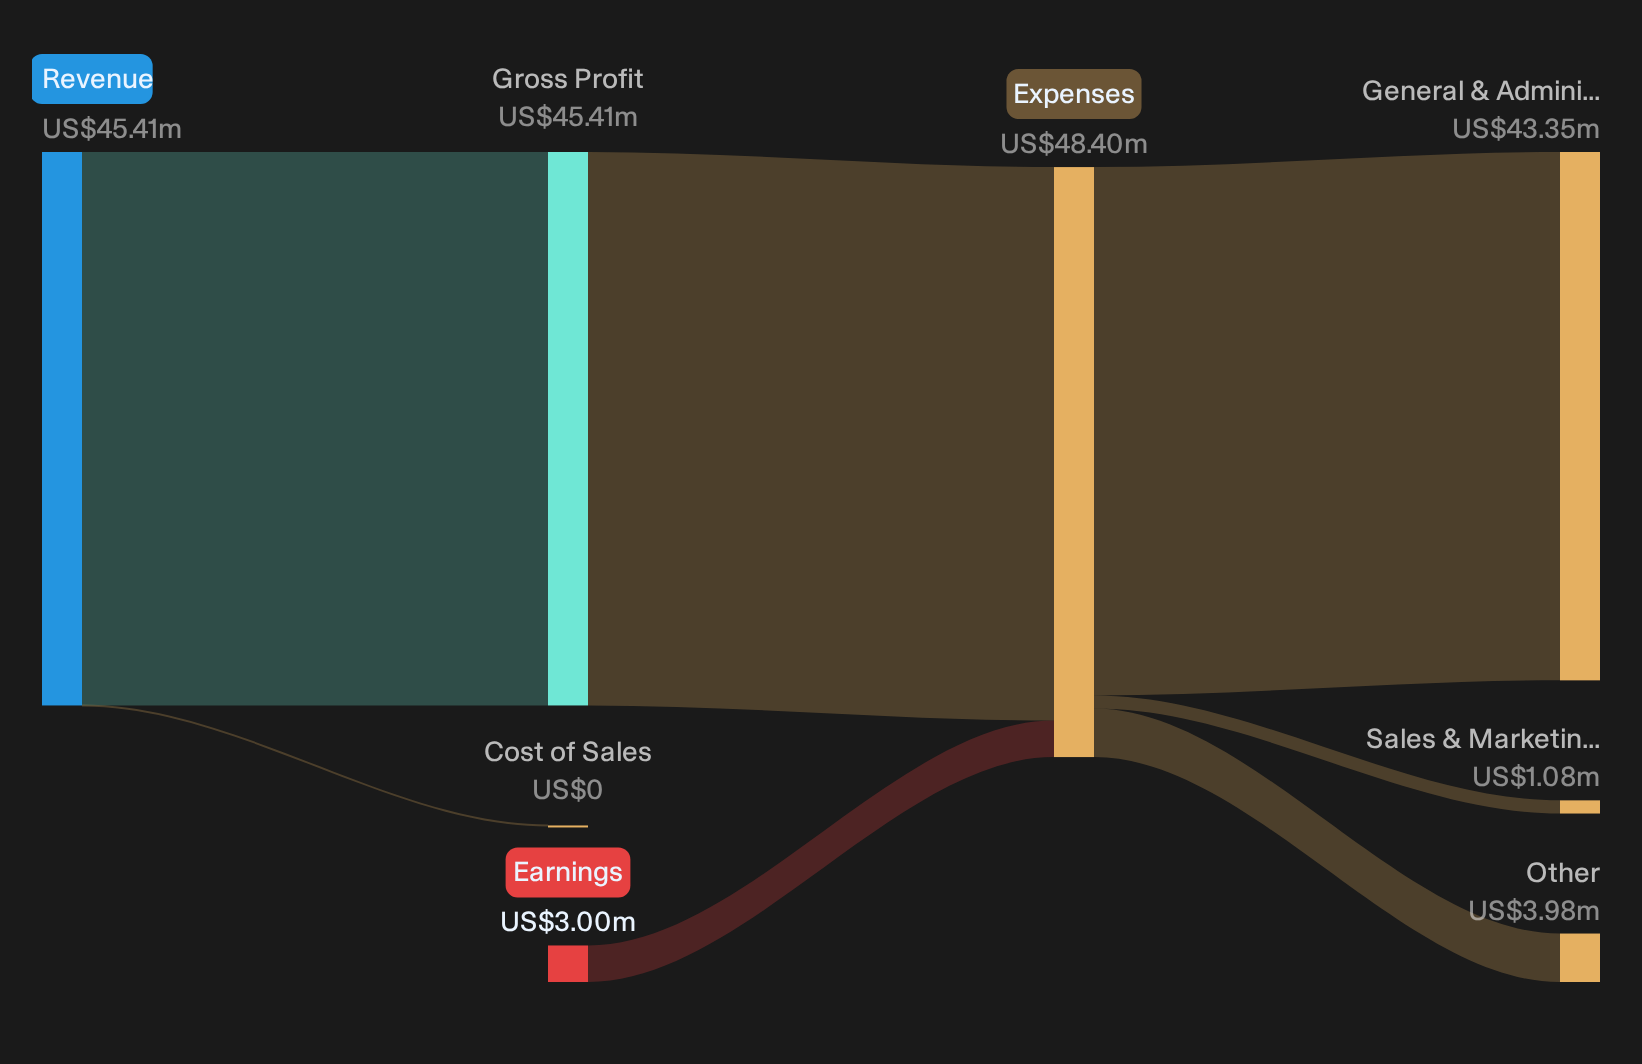
Riverview Bancorp earnings tilt toward cautious optimism
Riverview Bancorp just put up a clean set of headline improvements. Revenue and net income both moved higher year on year, and basic EPS doubled to US$0.10. Net interest margin at 3.34% points to a healthier spread on lending, which supports that relationship banking narrative. Profit returning after a stretch of losses fits a constructive story for a regional lender that relies on steady deposit and loan ties across Washington and Oregon.
Profit return tempers the cautious Riverview thesis
The bearish spin on Riverview Bancorp usually leans on local credit risk and rate pressure. These quarterly figures blunt some of that worry. Higher net income, better EPS and an improved net interest margin point away from immediate earnings strain. The share price barely moved, slipping 0.5%, which suggests investors are not ready to dismiss past losses. A single quarter of profit does not erase cycle risk for a concentrated regional bank, but it does not confirm a near term stress story either.
Are analysts treating Riverview Bancorp’s return to profit as the start of a real earnings reset or a temporary reprieve? Check the consensus price target analysis for Riverview Bancorp.Hunt For Quietly Mispriced Setups
Riverview Bancorp just showed that a clean quarter and a flat share price can live side by side. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 31% below our estimate - extend an advisory platform where new senior hires convert a crowded deal pipeline into higher fee transactions.
- Company 2 - 46% below our estimate - tackle a near record construction backlog as nine large projects shift from bid stage to multi year execution and cash collection.
- Company 3 - 25% below our estimate - scale manufacturing and access for incretin therapies while newer oncology and neuroscience drugs start forming extra revenue pillars.
Those are three of them. See the full list of 29 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com