


EN
Is Gaming and Leisure Properties (GLPI) Trading At A Discount After New Deals?
Gaming and Leisure Properties has seen its share price decline year to date, even as it announces new projects and lease deals that reshape its real estate mix. That gap between activity and performance raises a simple question for you as an investor: whether today's valuation can be explained by the earnings that underpin this gaming focused REIT.
- The stock is down 13.4% year to date, which puts fresh attention on whether the current price still lines up with Gaming and Leisure Properties' earnings power.
- The new joint venture with Prologis around the former Hollywood Casino Joliet site, plus the Sunland Park sale leaseback, may shift how quickly rental income grows and how dependable those cash flows look against funding costs and tenant concentration risk.
- The analysts covering Gaming and Leisure Properties have run their own numbers. See what analysts think Gaming and Leisure Properties's shares could be worth.
The issue now is whether Gaming and Leisure Properties' current share price is properly supported by the earnings that the business is generating.
If you want a broader reference point alongside Gaming and Leisure Properties' earnings story, compare it with other 29 high quality undervalued stocks
Is Gaming and Leisure Properties a Bargain on Earnings?
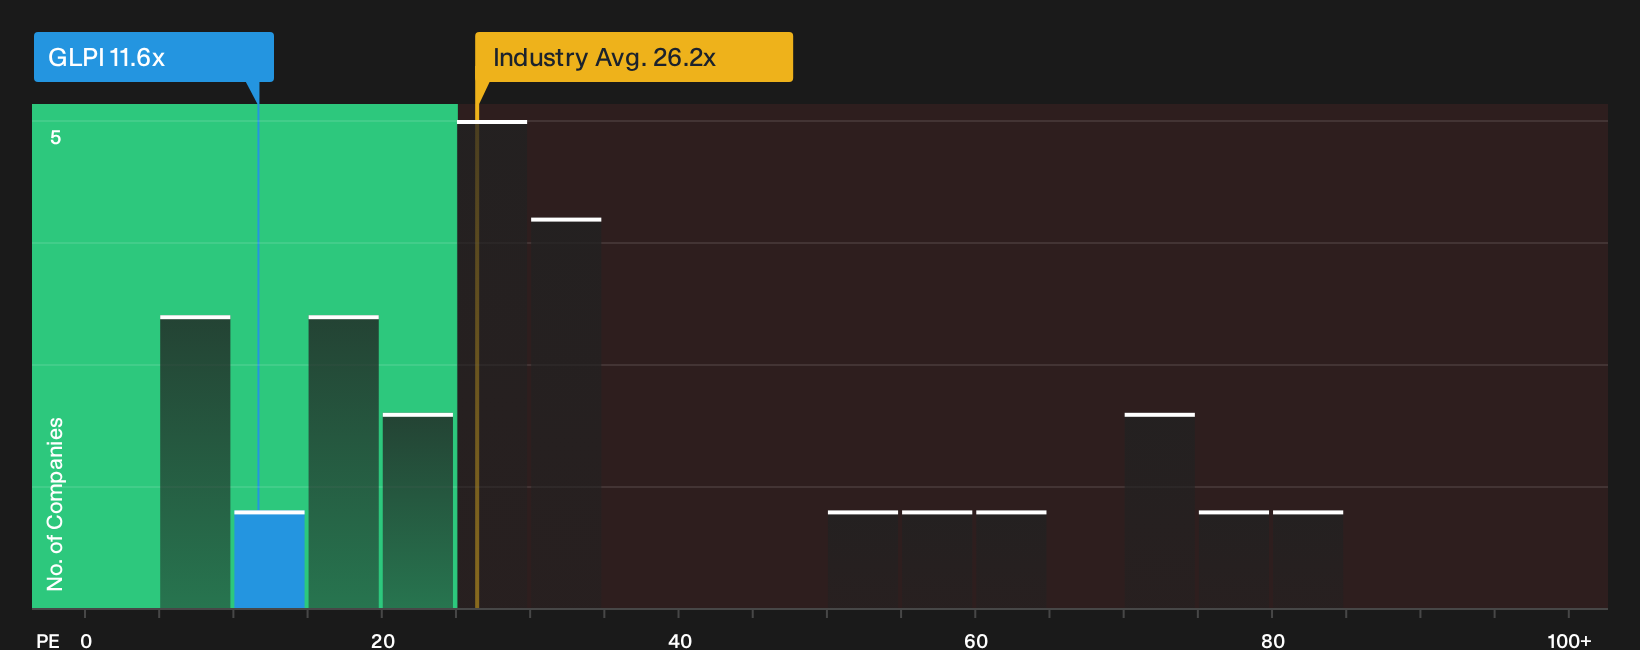
P/E is a useful lens for Gaming and Leisure Properties because earnings are a key anchor for how investors judge a mature, cash generating REIT. On this measure, the stock trades on a P/E of 11.6x, which is below both the specialized REIT industry average of 15.6x and the broader peer group at 19.6x. For a reader, that signals the market is currently paying less per dollar of profit for GLPI than it does for many comparable landlords.
The fair multiple that reflects Gaming and Leisure Properties' own mix of growth prospects, margins, size and risk screens higher than where the shares trade today. As a result, the current P/E points to the stock looking undervalued on this framework. Because the new Prologis joint venture and Sunland Park sale leaseback reshape the asset base while investors focus on tenant quality and funding costs, this discounted P/E suggests those concerns are already reflected in the price. Explore the numbers behind Gaming and Leisure Properties's P/E valuation.
The Gaming and Leisure Properties Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/E puzzle on Gaming and Leisure Properties' valuation leaves off, by spelling out which paths for growth, margins and earnings would line up with a much higher or much lower share price than today. Each narrative ties its numbers to a clear view on how Gaming and Leisure Properties' profitability and risk profile might evolve next, which you can revisit as fresh information comes through.
One of the top community narratives on Gaming and Leisure Properties: 25% undervalued
"Analysts expect Gaming and Leisure Properties to keep compounding AFFO through 2027 as its US$1.8–US$2.6b contracted development and acquisition pipeline flows into cash rent…"
Discover why this Narrative puts Gaming and Leisure Properties at 25% undervalued.
One more forward check for Gaming and Leisure Properties
Price tells you what investors pay today, but the analyst road map for Gaming and Leisure Properties over the next few years offers a separate lens on what those earnings streams could look like. Explore where analysts expect Gaming and Leisure Properties to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com