


EN
Fagerhult Group (OM:FAG) Stock Price Flags Q2 Earnings Dividend Strain
Fagerhult Group stock has been under pressure, with the share down around 15% to 17% over the past week and month as investors react to softer lighting demand and fresh earnings. The new Q2 2026 report shows revenue of SEK 1,973.9m and a small profit with basic earnings per share of SEK 0.07, which keeps the business in the black but highlights how thin profitability has become.
The real story now sits on the balance sheet. Debt is straining cash generation, the dividend is not covered by earnings or free cash flow, and that tension is increasingly what sets the risk reward debate for Fagerhult Group.
Worried that Fagerhult Group’s thin earnings and stretched dividend cover leave too little room for error? You can benchmark it against companies with sturdier cash generation and balance sheets in our list of solid balance sheet and fundamentals stocks (207 results)
Q2 2026 Earnings Summary
- Revenue (Q2 2026 vs. Q2 2025): SEK 1,973.9m vs. SEK 1,848.3m (up about 6.8%)
- Net Income (Q2 2026 vs. Q2 2025): SEK 12.5m vs. SEK 46.3m (down about 73.0%)
- Basic EPS (Q2 2026 vs. Q2 2025): SEK 0.07 vs. SEK 0.26 (fell about 73.0%)
- Trailing 12-Month Net Income Margin (Q2 2026 vs. Q2 2025): 2.3% vs. 2.9% (compressed by 0.6 percentage points)
Fagerhult is layering new savings on top of an existing program. Ask Charlie what Fagerhult’s extra SEK 120m in cuts really means.
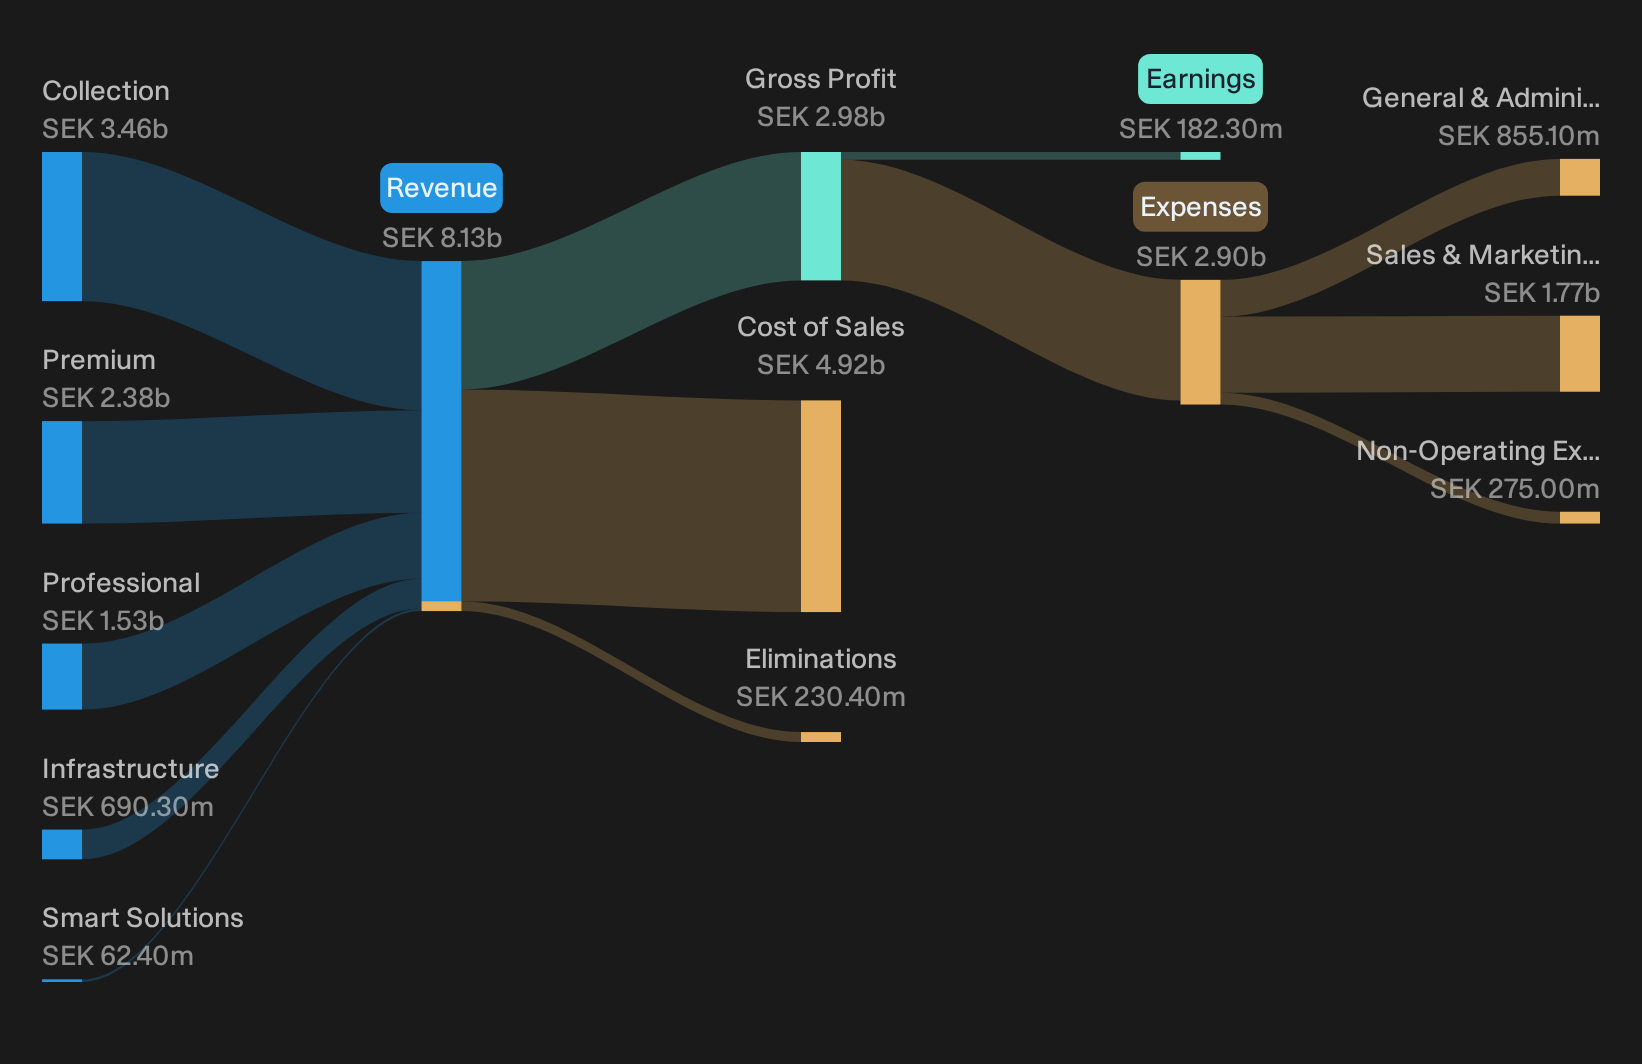
Evaluating Fagerhult’s Cost and Mix Upside
The bullish view depends on Fagerhult Group turning structural themes into real profit gains rather than just talking about them.
"Group wide cost saving and efficiency program targeting an EBITA improvement of SEK 220 million, together with procurement coordination in areas like electronics and IT, is aimed at structurally lowering operating costs and supporting earnings and free cash flow."
Recent numbers show early, but partial, progress. Reported Q3 2026 EBITA margin of 7% benefits from an earn out release, with underlying profitability closer to 5.4%. Identified savings total about SEK 220m and SEK 25m flowed through in Q3. However, cash generation remains weak and working capital still weighs on free cash flow.
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there.
Fagerhult Bear Case: Weak Orders, Soft Cash and Margin Drag
The bearish view on Fagerhult Group argues that cost cuts and mix shifts might not offset sluggish projects and execution risk.
"While focus on segments such as data centers, infrastructure and defense is intended to rebalance exposure away from weak new build offices, execution risk around sharpening the geographic focus and simplifying the structure could keep operating costs high relative to current order intake. This may constrain net margins until the new mix is fully reflected in the income statement."
Q3 backs up that concern. Order intake fell 13.8% organically, while underlying EBITA margin sat near 5.4% and rolling 12 month EBITA margin slipped to 6.5%. Operating cash flow of SEK 62m outflow and higher financial expense further tighten room to absorb ongoing restructuring.
Hunt For Mispriced Cash Generators
Fagerhult Group’s latest quarter leaves investors weighing thin profitability against heavy balance sheet demands. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 38% below our estimate - uses government backed trade in subsidies and recommerce habits to capture more used devices for resale.
- Company 2 - 26% below our estimate - shifts toward higher margin adult and oral health probiotics as it builds its direct distribution footprint.
- Company 3 - 29% below our estimate - sells consulting projects to regulated clients that value cultural proximity and rising utilization of its fee earners.
Those are three of them. See all 195 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com