


EN
Missed New Hope's Rally? Here's What Early Buyers Saw
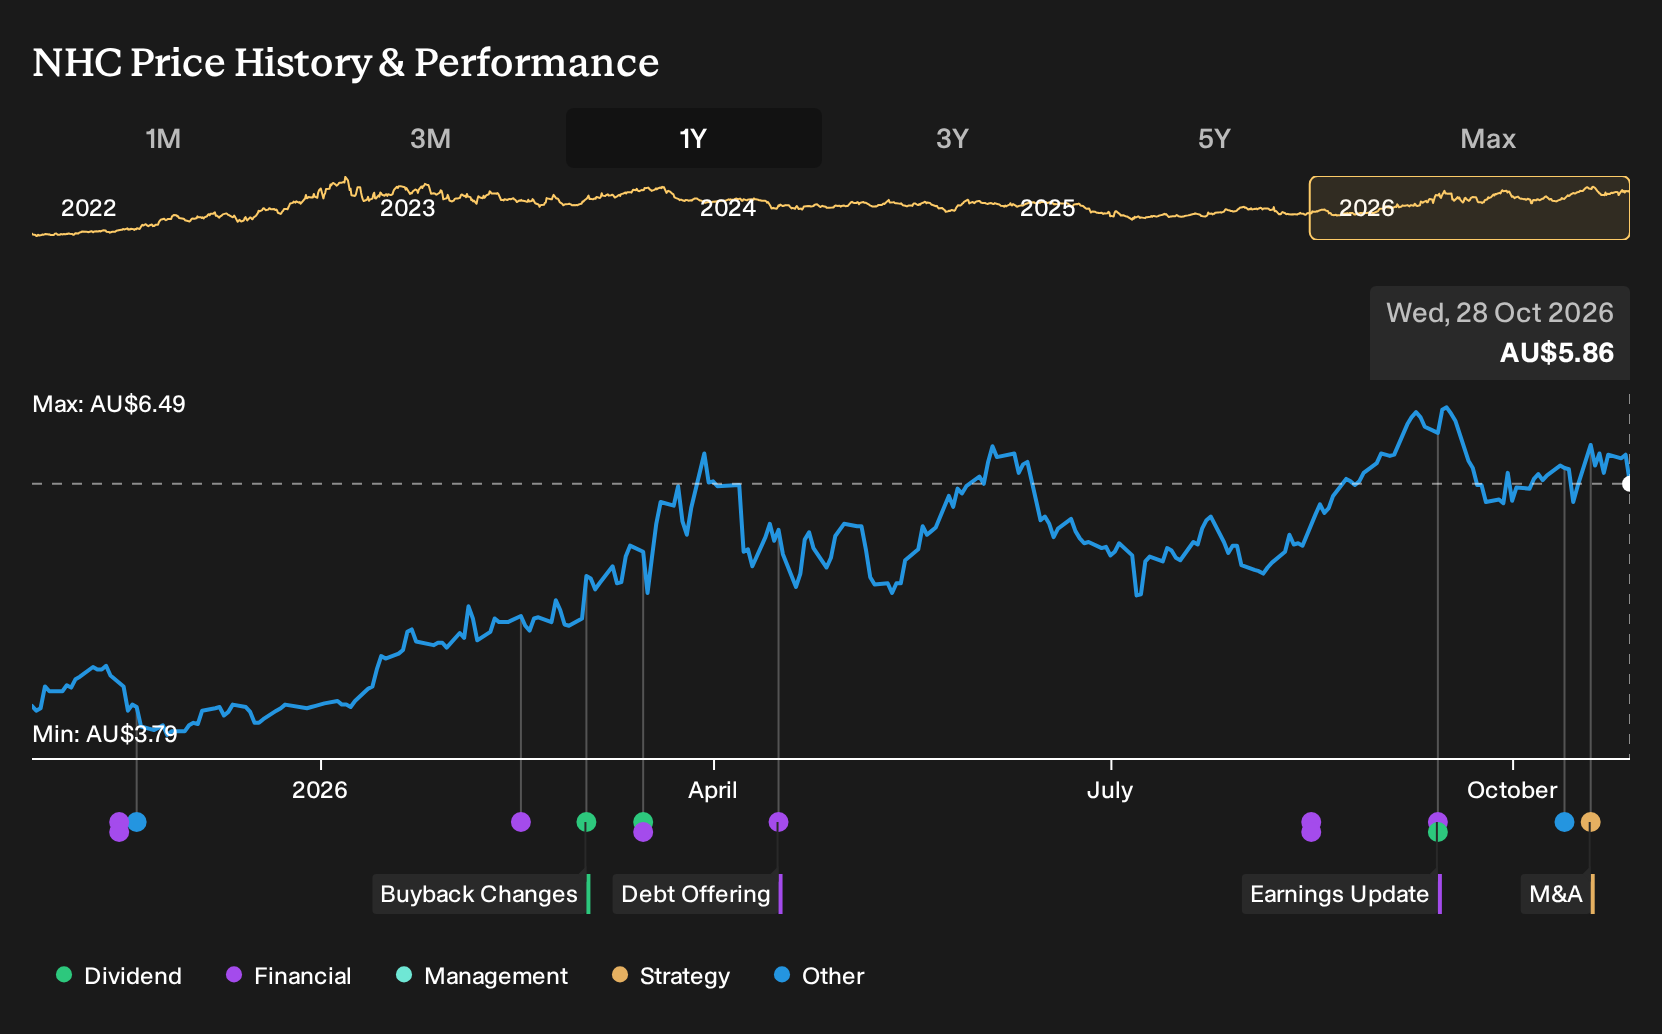
If you only glanced at New Hope headlines, the eye catcher was the A$1.3b move to buy the rest of Malabar Resources and increase its Hunter Valley coal footprint. For New Hope shareholders, the return over the past year was 55.9%, including dividends. If you were deciding back on 28 October 2025 whether to buy, what had to be true about future Asian coal demand and port capacity to make that payoff look reasonable?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
New Hope has already moved. Pinpoint other ways to investigate the theme among 35 elite gold producer stocks.
The Two Stories Investors Had To Weigh On New Hope
The shares cost A$3.99 at the start of the period, and anyone looking at New Hope then had to decide which story about future coal exports and capital access felt more realistic.
On the bullish side, the narrative argued a fair value of A$5.7, 43% above the start price, if Southeast Asian urbanization and port and rail upgrades let New Hope ship more coal while revenue grew 5.8% a year and margins settled near 27.3%.
The bearish case pointed to a fair value of A$2.8, 30% below the start price, stressing ESG driven lending limits as a key threat, alongside the assumption that the business might only justify a future P/E of 4.5x despite the same 5.8% revenue growth.
What The Results Changed For New Hope
The Malabar Resources deal was the big swing for New Hope, since a full A$1.3b acquisition would lean into the bullish export and infrastructure story by locking in more Hunter Valley tonnes and port exposure. Reported H2 2026 revenue of A$952.1m and net income of A$106.7m gave the upbeat thesis some support, although the net margin slipped from 13.1% to 11.2%, so the evidence cut both ways.
The hinge assumption here was not abstract coal sentiment but whether New Hope could turn Asian demand and export access into sustained profitability. When you look at other miners, stress test the story the same way by pairing any capacity or M&A news with the direction of reported net margin, not just top line and share price moves.
What New Hope's Price Now Demands You Believe
New Hope now trades at A$5.86, after a 55.9% gain over the past year, while the selected Narrative’s Fair Value estimate sits below the current price.
The Narrative questions whether a larger three mine portfolio and Maxwell ramp can sustain cash generation if earnings pressure, higher costs and safety issues persist. Anyone paying today’s price is effectively assuming the expanded operations deliver resilient margins despite those risks.
"Although New Hope is moving toward a larger three mine portfolio with the Malabar acquisition, the sharp fall in earnings per share to A$0.19 from A$0.50 on roughly flat A$1.77 to A$1.78b revenue raises the risk that integrating Maxwell simply scales a business model already under price and cost pressure, which could limit future earnings growth even if volumes rise."
The price and this Narrative do not agree. → Uncover what this Narrative says New Hope is actually worth
After New Hope, Who Owns The Dirt?
New Hope offers one version of resource exposure, turning coal into cash with capital, equipment and permits.
Alongside that sits a different model in the same energy landscape.
Some players never drill or operate; they simply own the mineral rights.
Operators fund development, run the rigs and manage execution risk, while the royalty owner takes a contractual slice of production.
That setup separates heavy spending from resource economics, letting the landlord benefit from additional wells without financing each new project.
That argument has a Narrative and a number behind it. → See the company one Narrative values 21% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com