


EN
Ford (NYSE:F) misses Q3 2026 sales expectations
Automotive manufacturer Ford (NYSE:F) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 2% year on year to $49.53 billion. Its non-GAAP profit of $0.49 per share was 21.4% above analysts’ consensus estimates.
For more on Ford, read our free full research report.
Ford (F) Q3 2026 highlights:
- Revenue $49.53 billion vs S&P analysts’ consensus estimates of $50.31 billion (2% year-on-year decline, 1.6% miss)
- Adjusted EPS $0.49 vs S&P analysts’ consensus estimates of $0.40 (21.4% beat)
- Adjusted operating income $2.66 billion vs analysts’ consensus estimates of $2.38 billion (5.4% margin, 11.8% beat)
- Operating margin 2.9%, in line with the same quarter last year
- Free cash flow margin 5.7%, down from 10.4% in the same quarter last year
- Sales volumes fell 9.3% year on year (5.6% in the same quarter last year)
- Market capitalization $46.69 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Ford’s revenue grew at a mediocre 6.8% annualized rate over the last five years, falling short of the industrials sector benchmark.
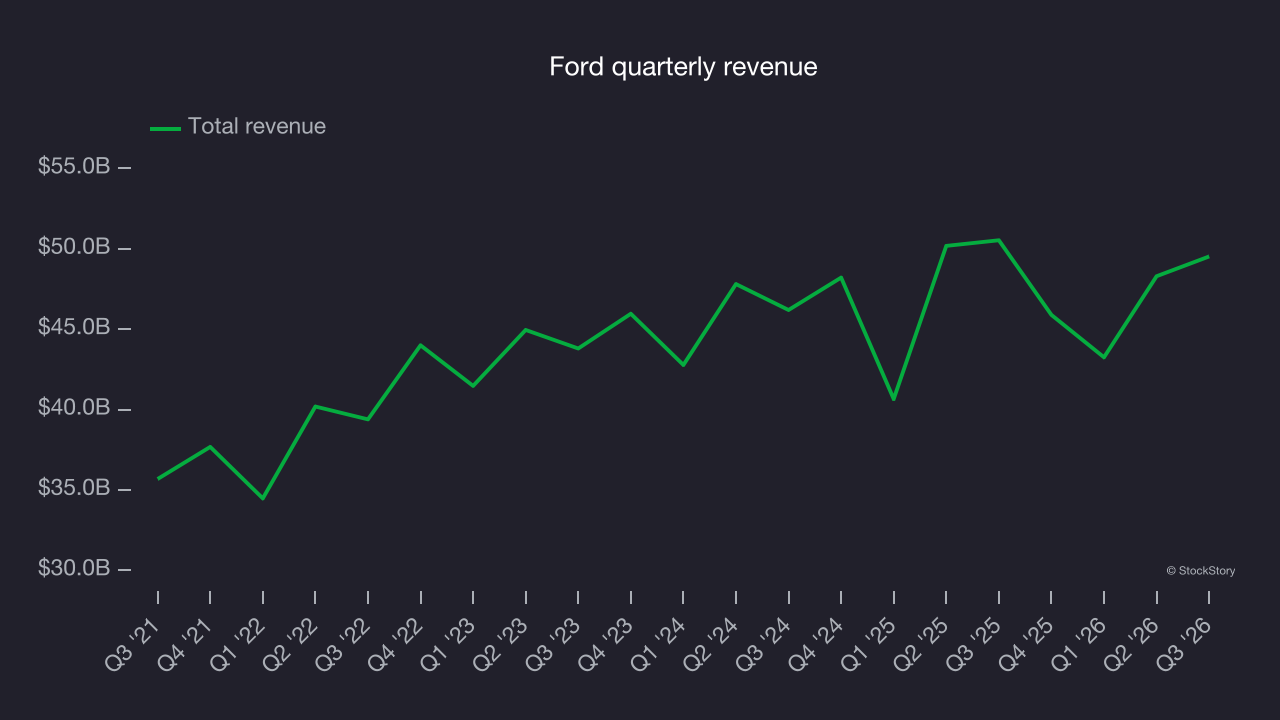
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Ford’s recent performance shows its demand has slowed as its annualized revenue growth of 1.1% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 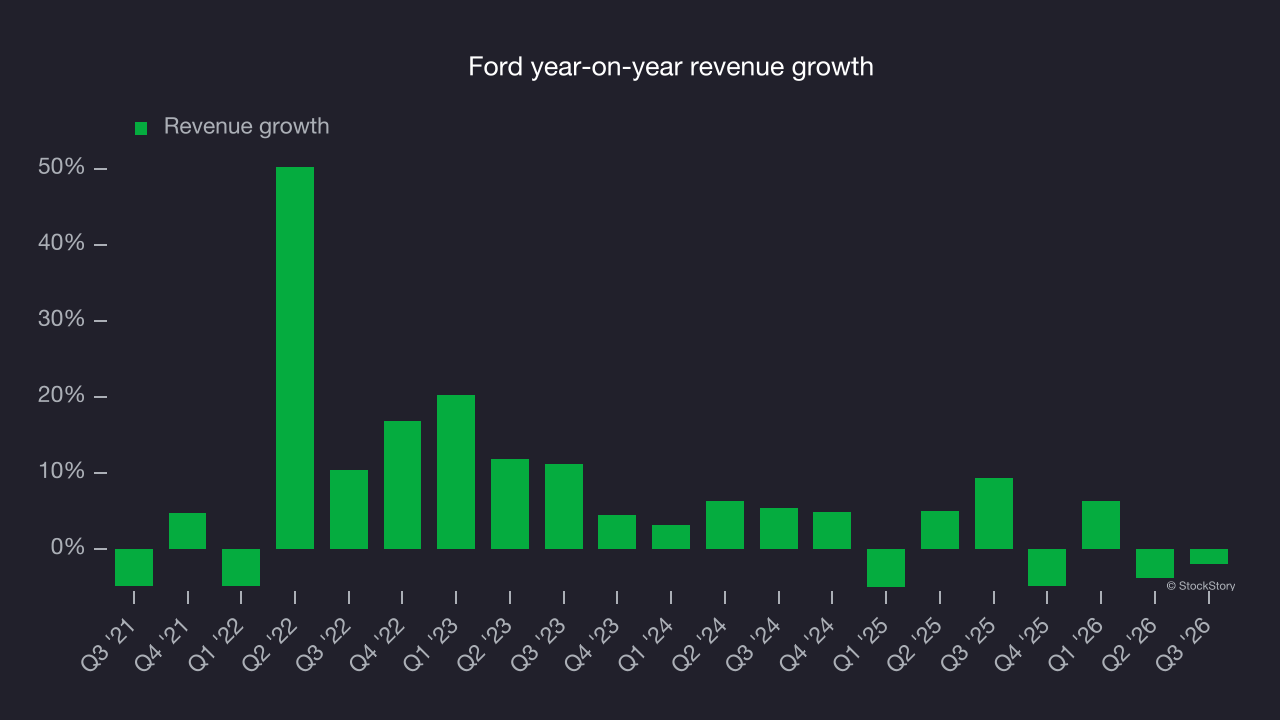
We can better understand the company’s revenue dynamics by analyzing its number of vehicles sold, which reached 1.05 million in the latest quarter. Over the last two years, the number of vehicles Ford sold declined an average of 4.1% year on year. Revenue growth outpaced this metric, indicating that price increases contributed to growth. 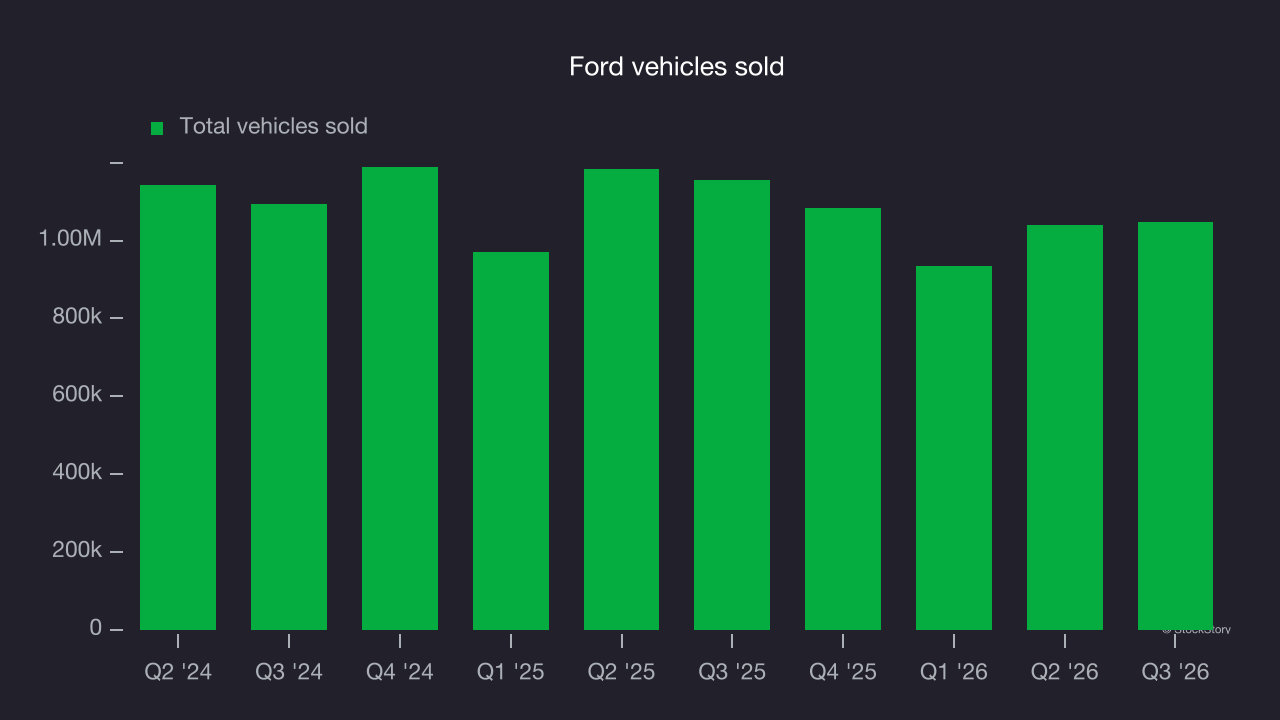
This quarter, Ford missed Wall Street’s consensus estimates and reported an uninspiring 2% year-on-year revenue decline, generating $49.53 billion of revenue.
Looking ahead, sell-side analysts expect revenue to grow 6% over the next 12 months, according to S&P. While this projection indicates its newer products and services will drive better revenue performance, it is still below average for the sector.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income (the bottom line) excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Ford was profitable over the last five years but held back by its large cost base. Its average operating margin of 1.5% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
Ford’s operating margin decreased by 7.4 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. Ford’s performance was poor, showing that costs were rising and it couldn’t pass them on to its customers.
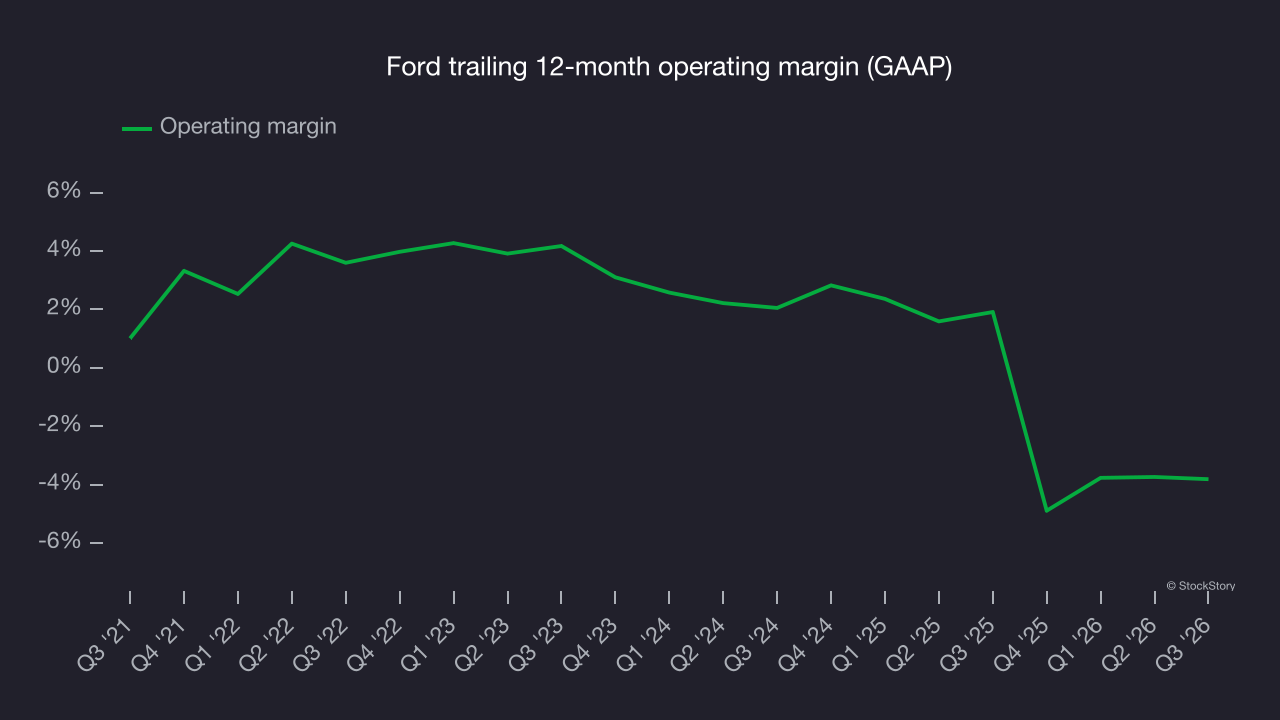
In Q3, Ford generated an operating margin of 2.9%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Ford’s EPS declined by 1.9% annually over the last five years while its revenue grew by 6.8%. This tells us the company became less profitable on a per-share basis as it expanded.
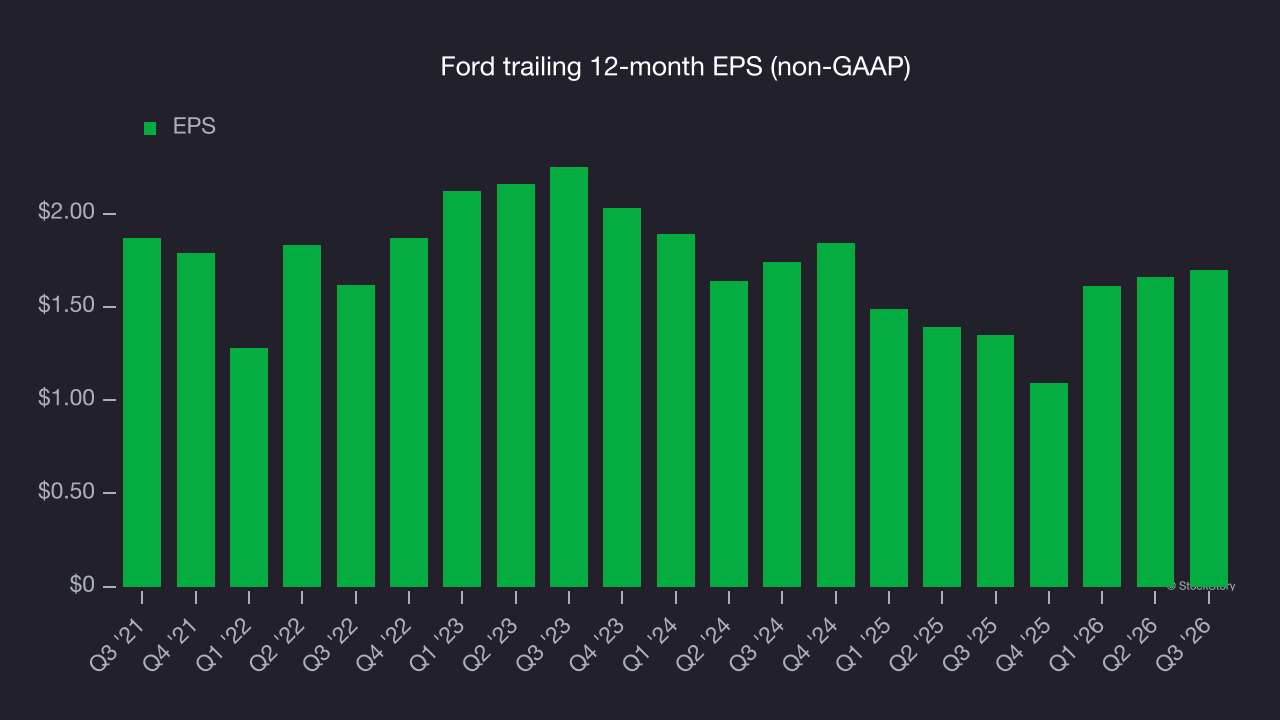
Diving into the nuances of Ford’s earnings can give us a better understanding of its performance. As we mentioned earlier, Ford’s operating margin was flat this quarter but declined by 7.4 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Ford’s EPS declined 1.2% annually over two years, a poor result that trailed its 1.1% revenue growth over the same period.
In Q3, Ford reported adjusted EPS of $0.49, up from $0.45 in the same quarter last year. This result easily cleared analysts’ consensus estimates, a positive outcome for shareholders. Over the next 12 months, Wall Street expects Ford’s full-year EPS to grow 7.6% from $1.70 to $1.83, according to S&P.
Key takeaways from Ford’s Q3 results
Ford turned in a decent quarter, with adjusted operating income well above analysts’ consensus estimates and EPS also beating Wall Street’s estimates. Revenue, however, missed expectations. Investors were likely hoping for more, as shares edged lower 1.3% to $11.78 immediately after the report.
When considering an investment in Ford at the current price, it’s important to assess its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).