


EN
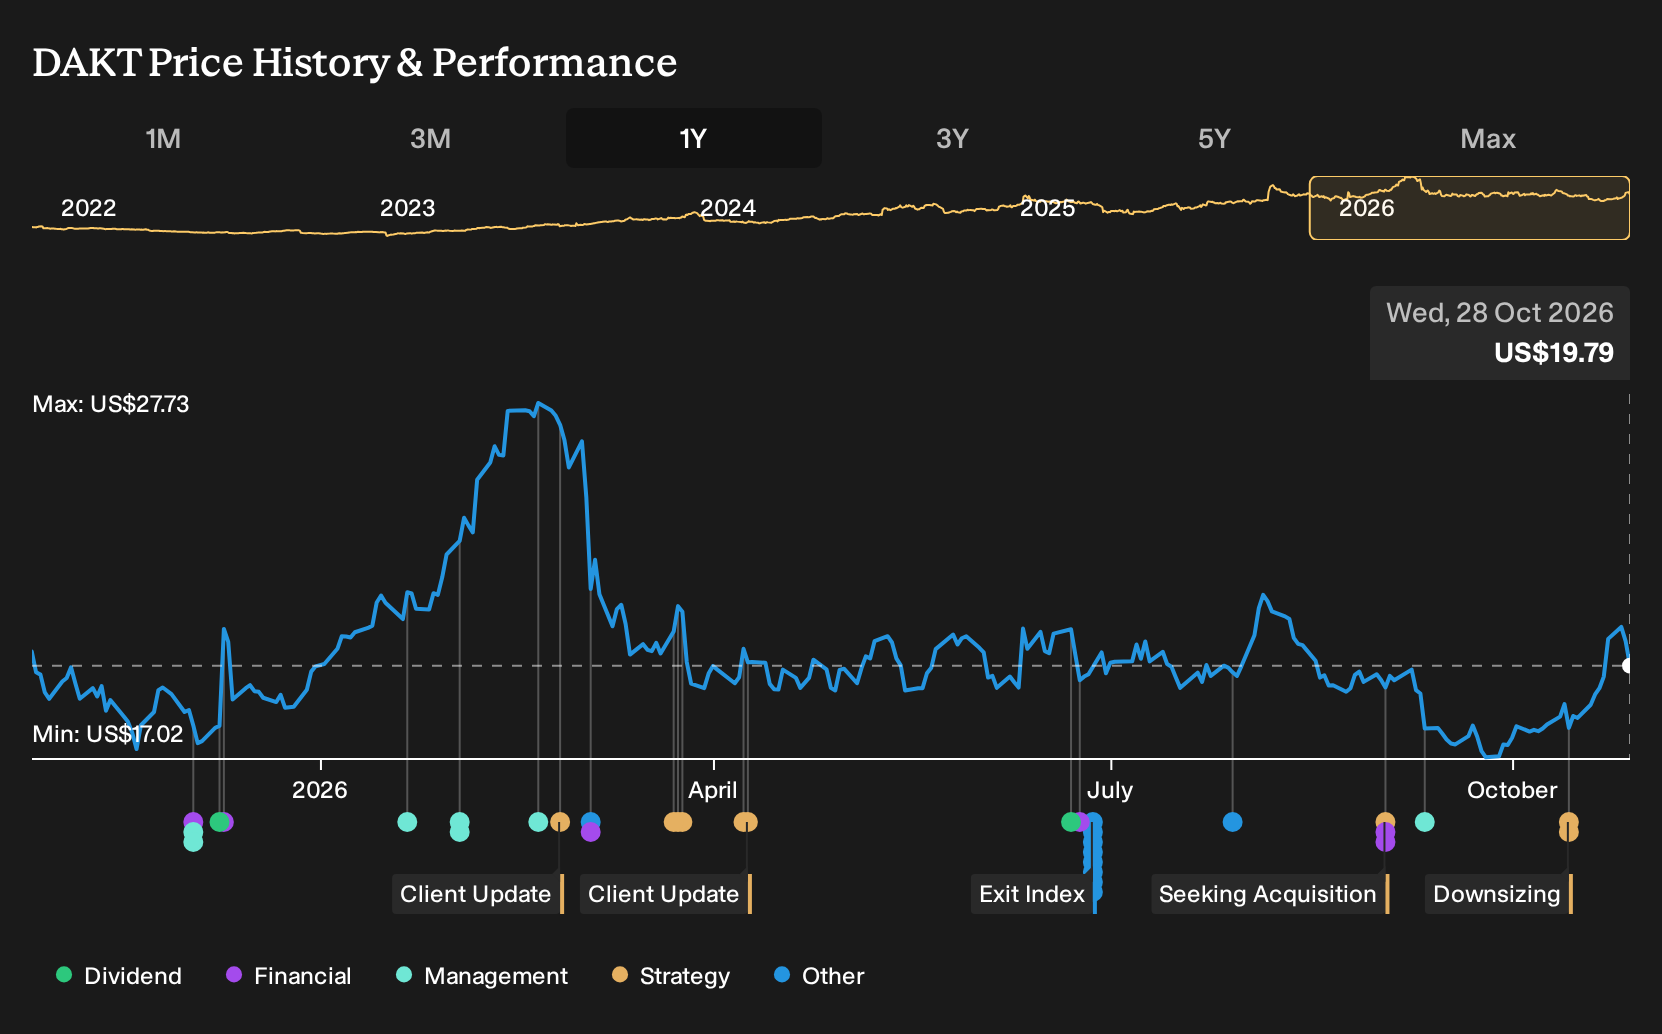
Will Factory Overhaul Change Daktronics (DAKT) Stock Narrative
- Daktronics outlined a worldwide manufacturing reset, including ramping up a new Mexico plant, expanding automatable capacity in China, reshaping U.S. staffing, and beginning a phased exit of its Ireland factory with planned restructuring costs and targeted annual cost savings once the changes are fully in place.
- The company is trading near this restructuring news while planning to spread production for key business units across three countries. This shifts how fixed costs, lead times, and regional risk are balanced in Daktronics’ operating model.
- Attention now turns to how Daktronics’ margin improvement story holds up as it leans harder on Mexico and China while exiting Ireland.
Scan how Daktronics’ manufacturing reset compares with other globally positioned industrials by reviewing the curated list of solid balance sheet and fundamentals (24 results).
Daktronics Investment Narrative Recap
To own Daktronics today, you need to believe the realignment of U.S., Mexico, and China production can keep large project backlogs flowing while supporting the existing margin improvement plan. The short term swing factor is whether this footprint shift keeps lead times and delivery reliability tight enough for Live Events, Commercial, and Transportation customers.
The biggest near term risk sits in execution. Multiple factory moves, a phased Ireland exit, and potential changes around International Transportation work all pull on the same operations and engineering teams. Any stumble that hits utilization, rework rates, or on time delivery could pressure margins just as expectations for earnings growth stay elevated.
The Ireland facility exit is the announcement that most directly frames this reset. Management laid out about US$13.5 million in cumulative pre tax charges and targeted annualized pre tax savings of US$7.7 million once fully in place, with the closure expected to be substantially complete by mid fiscal 2028. That is a meaningful swing factor in how fixed overhead is structured.
For you as a shareholder, the question is whether Daktronics can capture those planned efficiencies without disruption to key segments like transportation signage and international projects. Execution on customer handoffs, spare parts coverage, and equipment transfers will influence how quickly the broader cost reduction and margin objectives translate into more durable earnings power.
Daktronics' consensus story points to revenues of about US$1.1b and earnings of US$98.3 million by 2029, based on analysts' assumption of 7.3% yearly revenue growth and an earnings increase of roughly US$50 million from current earnings of US$48.3 million.
Uncover why Daktronics' fair value indicates a 62% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish angle on Daktronics leans heavily on this factory realignment as a catalyst. The most optimistic analysts were already modeling US$1.1b of revenue and about US$106.5 million of earnings by 2029, compared with US$98.3 million in the consensus view. You can treat the Ireland exit and Mexico ramp as fresh information that might push those narratives closer together or further apart, and use that spread in opinions as a cue to explore multiple scenarios before deciding how this reset fits your own expectations.
Explore 4 other Daktronics fair value estimates, including one that suggests as much as 77% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Daktronics research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Daktronics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Daktronics' overall financial health at a glance.
Looking for more investment ideas beyond Daktronics?
Once you have formed a view on Daktronics, it often helps to compare it with other opportunities that fit different risk, income, and quality profiles. The Simply Wall St Screener can help you quickly surface stocks that match what you want your portfolio to do next.
- If you want potential growth with a smaller upfront outlay, consider using the screener to find 7 elite penny stocks with strong financials that already show stronger financial credentials than many peers.
- If you are hunting for quality at a reasonable price, let the filters surface 29 high quality undervalued stocks that combine solid fundamentals with what may be appealing valuations.
- If portfolio resilience is front of mind, focus on balance sheet strength and use the screener to pull a 30 resilient stocks with low risk scores that could help anchor your holdings during tougher periods.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com