


EN
Evercore (EVR) Stock Jumps As Q3 Earnings Back Margin Strength
Evercore entered its Q3 2026 report with a mixed recent run, roughly flat over the past quarter and slightly down over 90 days, then exploded 12.5% higher today to US$292.38. That single session move suggests euphoria. The earnings print provides more specific context.
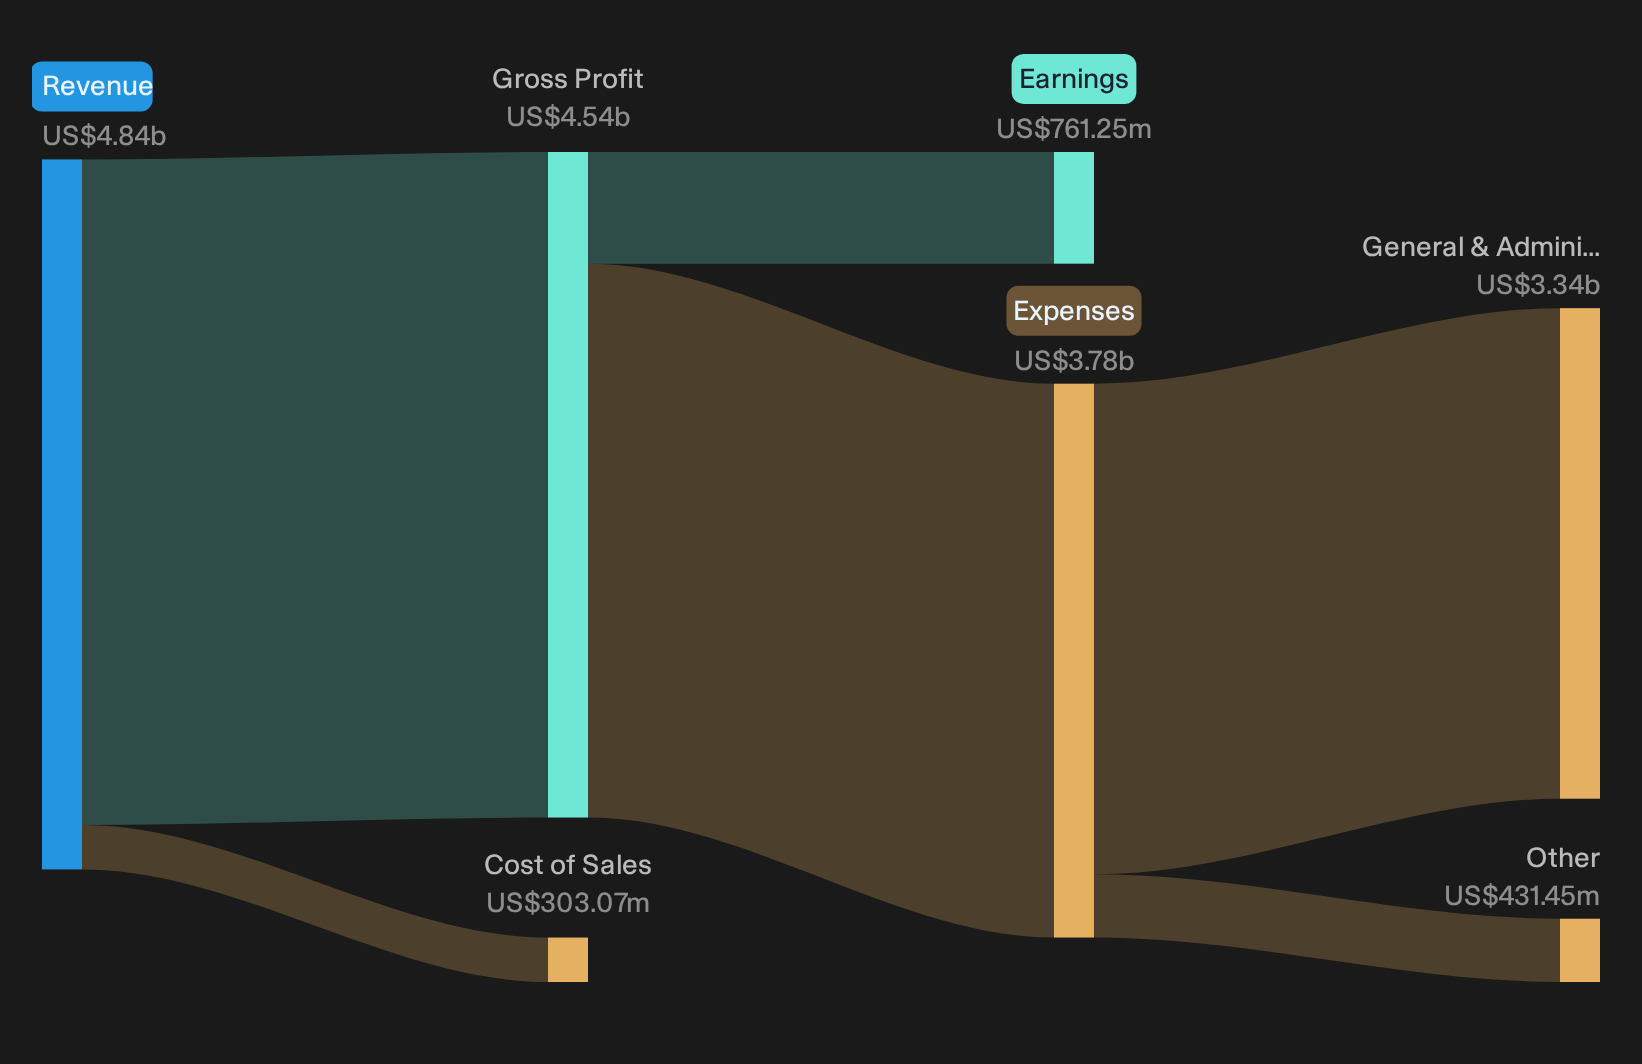
The adviser known for high end deal counsel just posted US$1.17b in quarterly revenue and US$4.19 in basic earnings per share, alongside a 15.7% trailing net profit margin. The key point is margin grip. The increase in profitability, supported by a lower compensation ratio, is what traders are paying up for.
Like the margin strength at Evercore but want similar profitability with an even tighter focus on balance sheet resilience and fundamentals? Scan our list of solid balance sheet and fundamentals stocks (24 results)
Q3 2026 Evercore Earnings Summary
- Total Revenue (Q3 2026 vs Q3 2025): US$1,168.6m vs. US$1,038.9m (up about 12.5%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): US$160.8m vs. US$144.6m (up about 11.2%)
- Basic EPS (Q3 2026 vs Q3 2025): US$4.19 vs. US$3.73 (up about 12.3%)
- Net Profit Margin (Trailing 12 Months vs Prior Year): 15.7% vs. 14.9% (margin improved)
Evercore just posted its sixth straight record revenue quarter. Ask Charlie which Evercore hires matter most for next year.
Evercore’s Bull Story Hinges On Operating Leverage
Supporters argue Evercore can translate investment in people and platforms into higher earnings power that the market does not fully credit yet.
"The main thing that has to go right is that Evercore maintains operating leverage by balancing higher compensation and non-compensation spending with revenue growth across M&A, private capital advisory, ECM, restructuring, and EMEA advisory."
Q3 provides evidence for that claim. Revenue reached US$1.17b while basic EPS was US$4.19 and the trailing net margin stands at 15.7%. Those figures, together with the lower compensation ratio flagged on the call, indicate that expenses are rising more slowly than fee income for now, which aligns with the operating leverage that supporters are focusing on.
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all.
Evercore Bears Focus On Costs, But Mix Risk Remains
Bears argue Evercore’s heavier tech and hiring budget will lock in higher overhead and blunt earnings power even in strong fee years.
"Evercore is increasing spending on technology, data and AI projects together with hiring and related growth initiatives. The Q2 2026 non compensation expense ratio of 17.5% compared with 14.2% for full year 2025 suggests that if these investments do not translate into clear productivity gains, structurally higher overhead could limit future operating leverage and earnings growth."
Q3 cuts against that concern on costs. The adjusted non comp ratio is 14.1% and 13.7% YTD, roughly where management aimed. The missed milestone sits elsewhere. Sponsor and middle market activity still trails historical levels, so concentration in large cap and AI related advisory remains the live risk, not expense creep.
Hunt For Mispriced Earnings Power
Evercore just reminded you that sentiment can change quickly after one earnings report. The real opportunity is in researching stocks that could be undervalued before sentiment changes.
- Company 1 - 40% below our estimate - expands beyond trackers into storage and inverter packages that deepen ties with utility scale developers.
- Company 2 - 43% below our estimate - rides a surge in orders as larger LED boards and transportation projects move to software linked display contracts.
- Company 3 - 23% below our estimate - embeds AI assistants in productivity, coding and security tools that enterprises already treat as critical infrastructure.
That is three of the list. See all 29 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com