


EN
How Investors Are Reacting To Entergy (ETR) Ahead Of Earnings Report
- Entergy plans to release third quarter 2026 results on November 2, with management set to outline recent operating performance and financials on a public webcast that will be available through its Investor Relations site.
- The expanded capital program, which now includes about 30 GW of new and repowered resources plus over 1,000 miles of standardized transmission, highlights how Entergy is positioning its regulated utilities for long term demand tied to data centers and industrial load.
- We will look at how Entergy’s long term buildout plan and upcoming earnings release shape the company’s broader investment narrative.
Entergy Investment Narrative Recap
To own Entergy, you need to buy into a long buildout story. The core belief is that data center and industrial demand can support a 10 year plan that adds about 30 GW of new and repowered generation plus more than 1,000 miles of transmission. The near term catalyst is clear. The 3Q26 earnings release and webcast on November 2 should clarify how current operations line up with that plan.
The biggest near term risk is execution and funding, not demand. A capital program of this size could strain cash flow, especially with debt already flagged as not well covered by operating cash. Management commentary on cost trends, equity needs and regulatory feedback will matter more than a single quarter’s headline EPS.
The most relevant recent development is Entergy’s decision to spell out that expanded capital plan, framed around standardized transmission designs and a much larger build program. That disclosure ties directly into the coming earnings call because investors will be looking for concrete progress updates rather than just a slide deck of ambitions.
For you, the key questions are practical. How much of that planned capacity is actually permitted, contracted and in active construction. How regulators are reacting to bill impacts and data center moratoriums. And whether management can keep enough financial flexibility, given that debt coverage by operating cash flow is already a flagged weak point.
Entergy's current analyst narrative points to US$17.6b in revenue and US$3.1b in earnings by 2029, based on 9.2% yearly revenue growth and an earnings increase of roughly US$1.3b from the US$1.8b level cited for today.
Uncover how Entergy's fair value indicates an 11% potential upside to its current price that could narrow quickly.
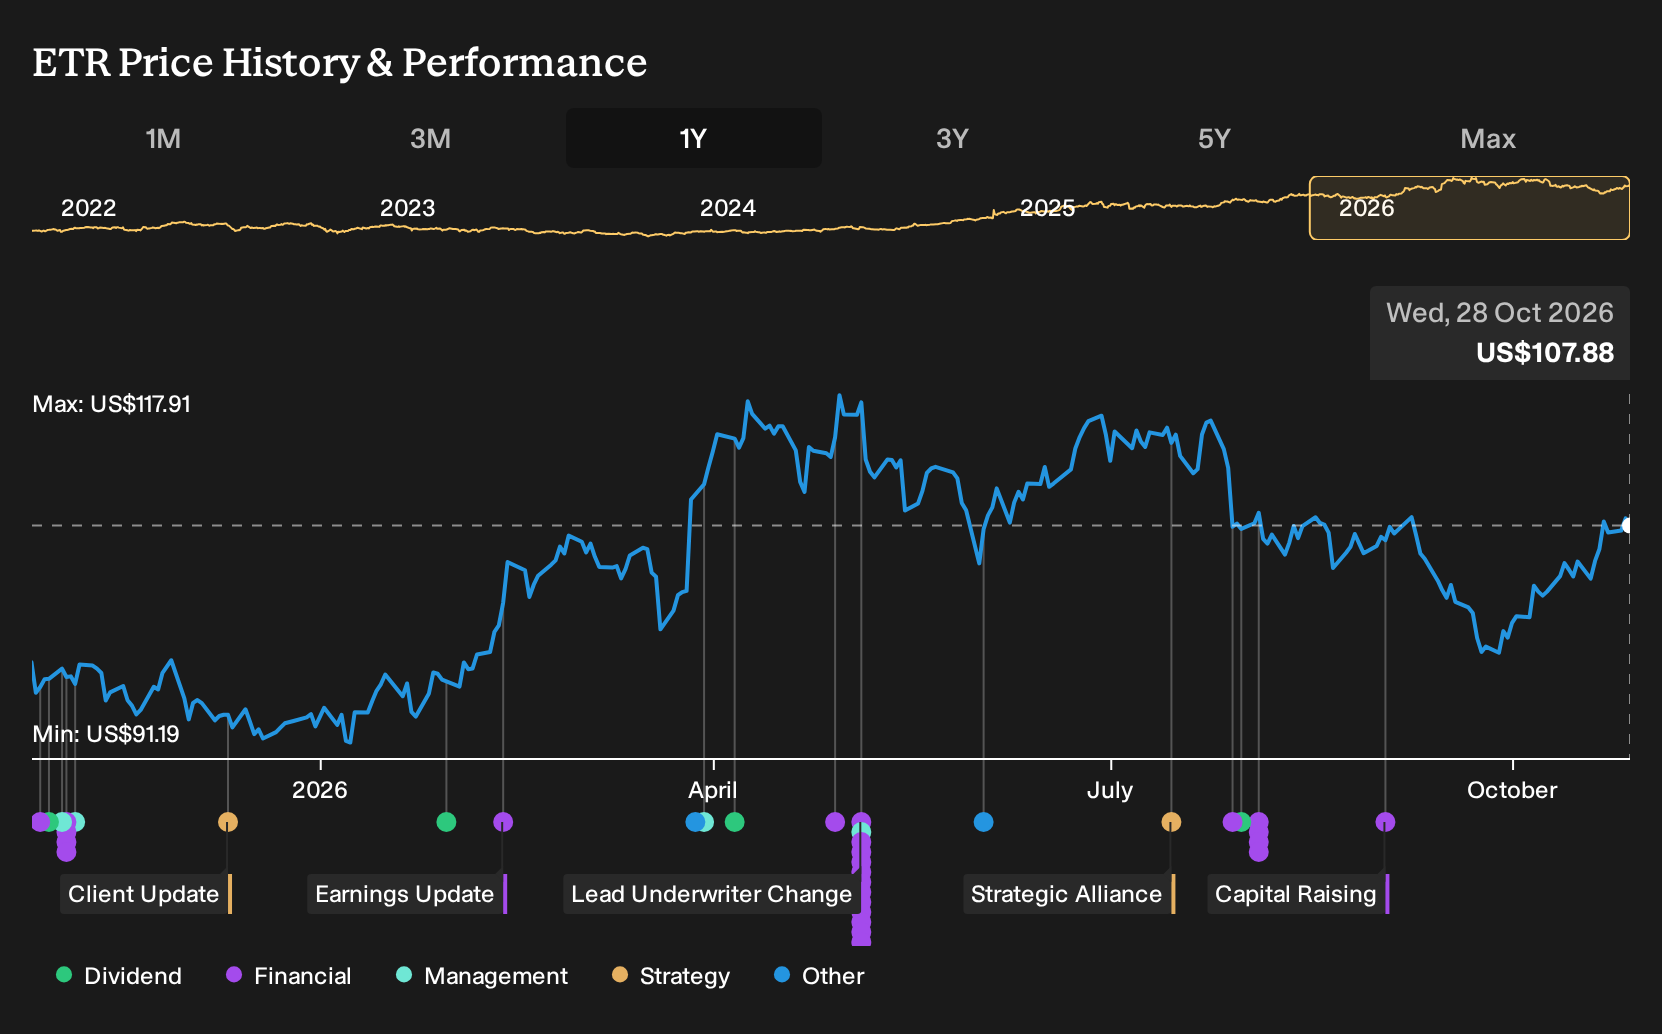
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community run from about US$82 to nearly US$120, which is a wide span for Entergy. Those retail views sit beside risks around heavier financing needs, policy uncertainty on gas and new nuclear, and regulatory pushback. As a result, you should expect sharply different opinions and explore several competing angles.
Explore another Entergy fair value estimate, including one that suggests as much as 24% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Entergy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Entergy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Entergy's overall financial health at a glance.
Looking For More Ideas Beyond Entergy?
If Entergy has your attention but you want a wider watchlist, the Simply Wall St Screener can help you quickly surface other companies that fit the kind of profile you care about most.
- If balance sheet strength matters to you, filter for companies with resilient finances using the list of solid balance sheet and fundamentals (24 results).
- If potential mispricing is your focus, scan for opportunities trading below estimated value through the 29 high quality undervalued stocks.
- If you prefer cash returns in your pocket, target income focused opportunities by running the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com