


EN
WEX’s (NYSE:WEX) Q3 2026: strong sales, full-year sales guidance is optimistic
Payment solutions provider WEX (NYSE:WEX) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue rising 12.8% year on year to $780.1 million. The company’s full-year revenue guidance of $2.98 billion at the midpoint came in 2.6% above analysts’ consensus estimates. Its non-GAAP profit of $6.13 per share was 8.1% above analysts’ consensus estimates.
For more on WEX, read our full research report, it’s free.
WEX (WEX) Q3 2026 highlights:
- Revenue $780.1 million vs S&P analysts’ consensus estimates of $755.6 million (12.8% year-on-year growth, 3.2% beat)
- Pre-tax profit $185.5 million (23.8% margin)
- Adjusted EPS $6.13 vs S&P analysts’ consensus estimates of $5.67 (8.1% beat)
- Revenue guidance The company lifted its revenue guidance for the full year to $2.98 billion at the midpoint from $2.88 billion, a 3.5% increase
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $21.38 at the midpoint, a 7.5% increase
- Market capitalization $6.35 billion
“We delivered another quarter of strong revenue and adjusted EPS, expanded margins, and returned the vast majority of our adjusted free cash flow to shareholders through share repurchases,” said Melissa Smith, WEX’s Chief Executive Officer and President. “Our results reflect real progress in pricing, new business wins, and innovation across each of our segments. We’re building on that momentum by continuing to strengthen our segments, bring innovative solutions to market, and drive sustainable growth and long-term shareholder value.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. WEX’s 10.5% annualized revenue growth over the last five years was decent. Its growth rate was slightly above that of the average financials company and shows its offerings resonate with customers.
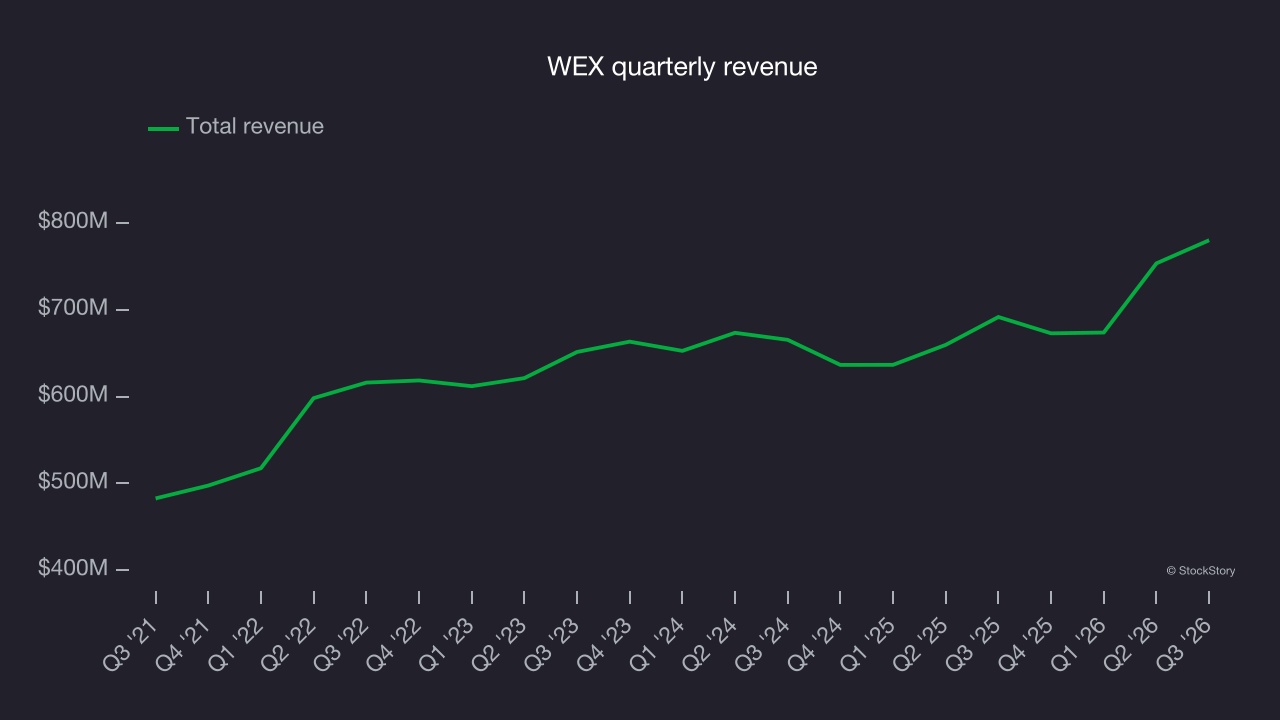
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. WEX’s recent performance shows its demand has slowed as its annualized revenue growth of 4.2% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 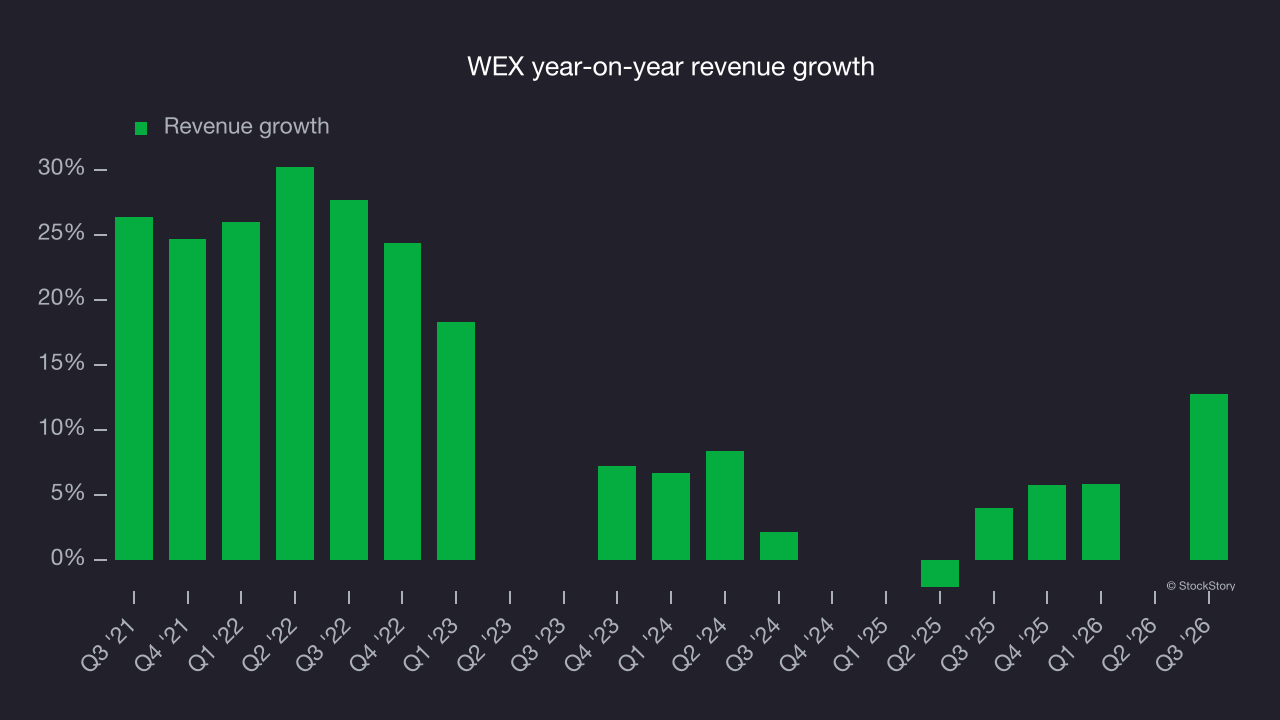 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, WEX reported year-on-year revenue growth of 12.8%, and its $780.1 million of revenue exceeded Wall Street’s consensus estimates by 3.2%.
Key takeaways from WEX’s Q3 results
WEX’s full-year outlook provided important positives this quarter: EPS guidance came in well above analysts’ consensus estimates, and revenue guidance also topped Wall Street’s consensus. EBITDA, however, missed expectations. Shares rose 2.2% to $193.28 immediately after the release.
WEX reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. The latest quarter is only one part of assessing longer-term business quality. Quality, when combined with valuation, can help determine if the stock is a buy. For more on WEX, read the full research report here (it’s free).