


EN
Flex (FLEX) Q2 Results Fuel Margin Optimism Despite Cash Strain
Flex just dropped its Q2 FY2027 scorecard and the stock exploded 11.6% in a single session to about $93, snapping a weak 30 day stretch where it had fallen roughly 17%. Traders rushed in on a headline that actually supports the excitement. Revenue landed at $8.5b with adjusted earnings per share at $1.18, both firmly aligned with a story of rising scale and improving profitability. The real heartbeat of this move sits in the guidance and margin direction, not the one day chart, where the emotional reaction and the fundamentals start to wrestle.
If you like how Flex combined solid Q2 revenue and earnings with stronger guidance, but want a broader range of companies that pair scale with resilient fundamentals, compare it with our list of solid balance sheet and fundamentals stocks (24 results).
Q2 2027 Earnings Summary
- Total Revenue (Q2 2027 vs. Q2 2026): US$8,491m vs. US$6,804m (+24.8%)
- Net Income (Excl. Extra Items, Q2 2027 vs. Q2 2026): US$263m vs. US$199m (+32.2%)
- Basic EPS (Q2 2027 vs. Q2 2026): US$0.70 vs. US$0.53 (+32.2%)
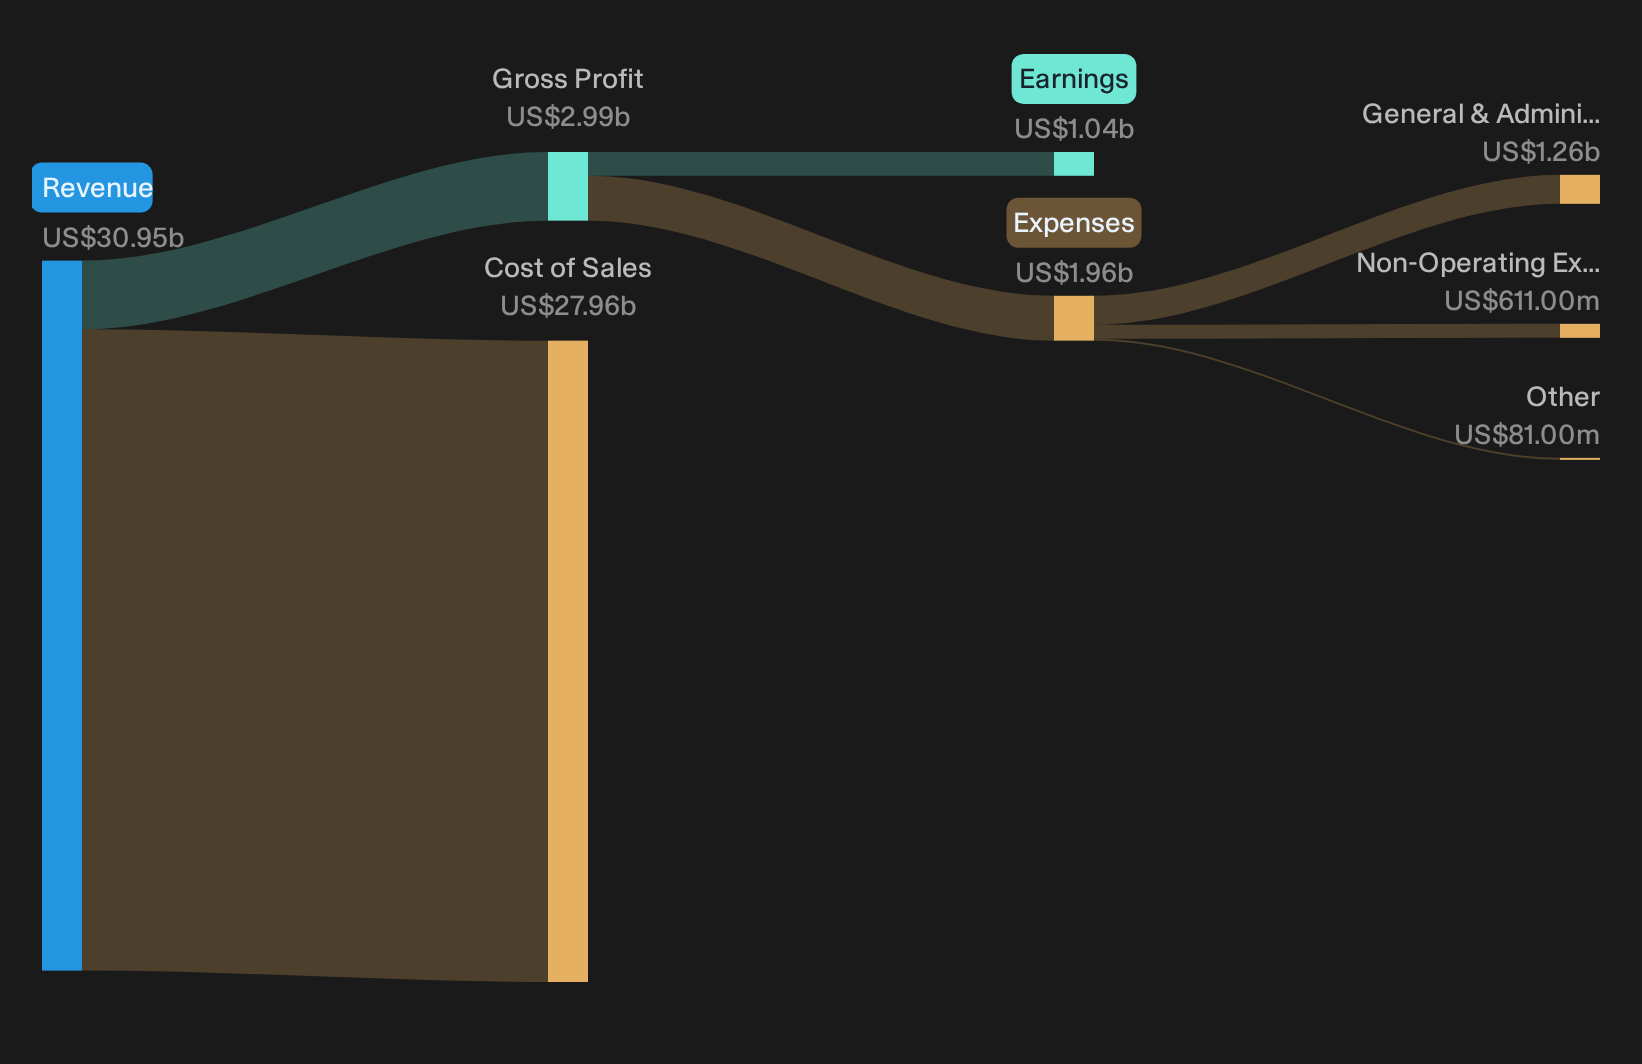
- Trailing 12-Month Net Income (Excl. Extra Items, Q2 2027 TTM vs. Q2 2026 TTM): US$1,037m vs. US$876m (+18.4%)
Flex just turned its cloud unit into a full-stack AI infrastructure play. Ask Charlie what makes Flex’s AI infrastructure spin-off so different.
Flex Bull Case Tested Against AI And Axiom Progress
The optimistic view on Flex hinges on AI infrastructure and Axiom taking over as the main earnings engines rather than just extra growth.
"The main thing that has to go right is that Flex and Axiom convert the AI-driven power and data center build-out, including the EPC Power acquisition and expanded AI hardware programs, into sustained orders that more than offset pressure in legacy consumer and lower-value revenue streams."
Q2 results move that goal from theory to early execution. CPI revenue climbed sharply to US$2.5b with double digit operating margin, Power margins reached about 16%, and guidance calls for CPI expansion of 75% to 85% and higher group profitability. EPC Power is already folded into Axiom and tied to that outlook, while consumer exposure stayed contained inside ITS.
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for.
Flex Cash Strain Confirms Bear Concerns On Spending
Bearish investors question whether Flex can fund AI and the Axiom spin without crimping cash returns.
"While Cloud and Power Infrastructure bookings and visibility are strong, the planned separation into Axiom requires heavy capital expenditure of about US$1.5b to US$1.6b and ongoing separation spending that has already pulled free cash flow conversion guidance down to about 40%."
Q2 free cash flow of US$261m already absorbed US$61m of separation costs and net capex near 3% of sales. Full year guidance still calls for US$1.5b to US$1.6b of capex and about 40% free cash flow conversion, so the cash drag described in the bearish view has not eased yet, even with stronger margins.
Hunt For Mispriced Earnings Power
Flex shows how quickly sentiment can change when guidance and margins align. The real opportunity is studying stocks that could be undervalued before the market reassesses them.
- Company 1 - 23% below our estimate - connects cloud infrastructure, productivity software and AI tools into a unified workflow that embeds deeply in operations.
- Company 2 - 32% below our estimate - sells advanced AI chips integrated with a proprietary software stack that can tightly bind large-scale data center developers.
- Company 3 - 31% below our estimate - advises corporate and sponsor clients on complex transactions where a stronger pipeline and senior hires aim to increase deal size.
That is three of the list. See every one of the 29 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com