


EN
Will Softer Earnings Change Storebrand Share Price Narrative
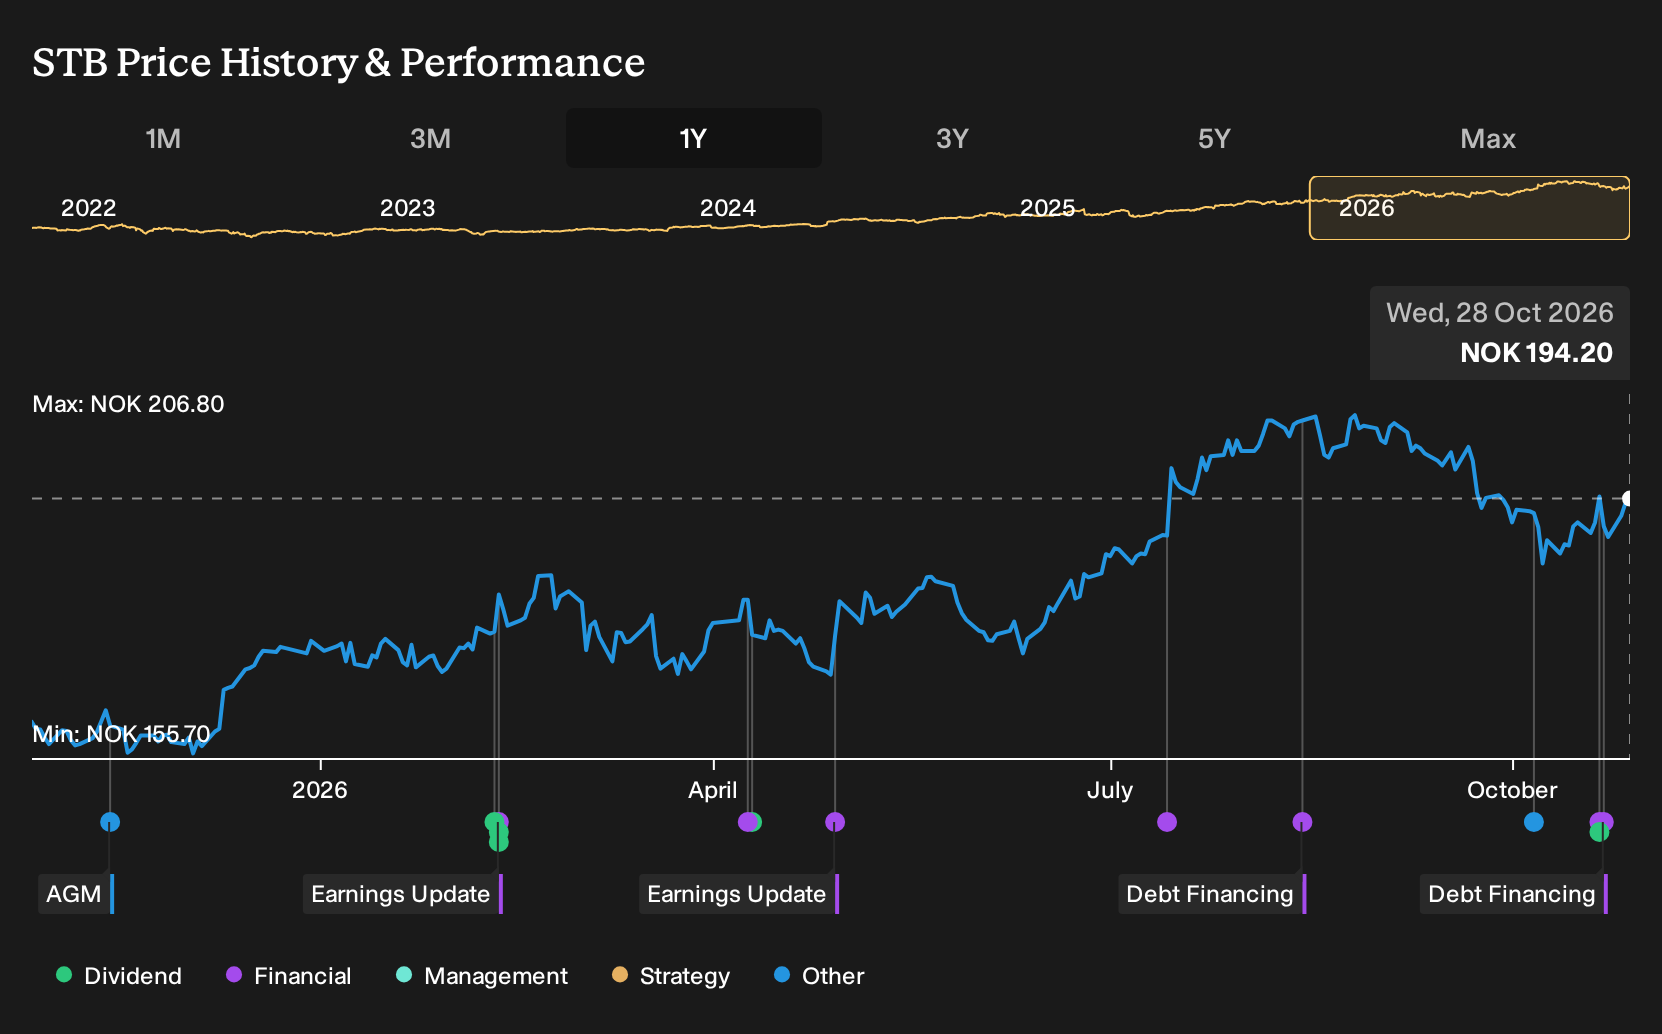
- Storebrand ASA reported third quarter 2026 net income of NOK 945 million and nine month net income of NOK 2,970 million, alongside the Board’s stated intention to propose a dividend of around NOK 6 per share for 2026.
- The combination of softer earnings and a clear dividend signal gives investors a direct view into how Storebrand is balancing capital strength, shareholder cash returns and future business investment priorities.
- This analysis reviews how Storebrand's investment narrative is shaped by softer earnings alongside the proposed NOK 6 per share dividend.
Compare Storebrand's mix of capital strength and cash returns with a curated field of financial stocks in our list of solid balance sheet and fundamentals (207 results) to see how this balance sheet focus appears in other companies.
Storebrand Investment Narrative Recap
To own Storebrand, you need to be comfortable with a Nordic pensions and insurance group that leans on fee based savings, insurance underwriting and long dated pension promises, supported by a balance sheet that funds dividends. Softer third quarter and nine month earnings, with lower net income than last year, highlight earnings sensitivity as the key short term pressure point.
The main near term catalyst is straightforward: investors will watch how quickly profitability metrics recover while Storebrand maintains its intended NOK 6 per share dividend. The biggest current risk is that thinner profit margins and weaker recent earnings persist, which could constrain flexibility around both capital deployment and future growth initiatives.
The most relevant update alongside the earnings print is Storebrand Bank ASA’s NOK 200 million perpetual Additional Tier 1 bond issue, with a coupon set at 3 month NIBOR plus 225 basis points. The capital story and the earnings story are landing in the same week, which gives a clearer picture of how the group is funding itself while signaling cash returns.
This AT1 instrument, with a first call date in March 2032 and planned listing on Euronext ABM, sits in the context of earlier concerns that debt is not well covered by operating cash flow. For shareholders, the key operational question is whether this new layer of capital supports the pensions and insurance engine without increasing risk if earnings pressure or margin compression continue.
Storebrand earnings assumptions and valuation bridge
Analysts are effectively sketching a version of Storebrand where the top line shrinks fast while profitability becomes much richer. Their models point to revenue falling by 48.1% a year over the next three years, paired with profit margins moving from 6.8% today to 42.8% by 2028. That mix of falling sales and higher margins is what underpins the earnings and valuation debate.
On current forecasts, earnings today of NOK 5.5b are expected to be NOK 4.9b by 2028, which is a decline of NOK 0.6b. The consensus view has Storebrand on a P/E of 13.3x on those NOK 4.9b earnings in 2028, compared with 9.8x today and slightly above the GB Insurance industry multiple of 13.0x. Analysts also factor in a gradual reduction in the share count of 2.11% a year over the next three years, which would mechanically lift earnings per share if profit holds at forecast levels.
Storebrand's narrative projects NOK 11.4b revenue and NOK 4.9b earnings by 2028. This assumes a 48.1% yearly revenue decline and an earnings decrease of NOK 0.6b from NOK 5.5b today.
Uncover why Storebrand's fair value indicates a 19% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly NOK 158 to NOK 325 per share, which is a wide gap for the same Storebrand story. Those private investors have not yet reflected the latest dividend signal and new AT1 issue, so you are effectively weighing fresh balance sheet moves against older earnings expectations.
Explore 2 other Storebrand fair value estimates, including one that suggests up to 67% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis and judgment.
- A great starting point for your Storebrand research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Storebrand. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Storebrand's overall financial health at a glance.
Looking for more Storebrand style investment ideas?
If the Storebrand story has helped clarify what you want from a financial stock, use that checklist and extend it across the wider market with the Simply Wall St Screener. Pick the mix of balance sheet strength, income potential and valuation that matters to you, then let the filters surface a focused shortlist.
- If capital preservation comes first for you, start with companies that score strongly on financial resilience through the 223 resilient stocks with low risk scores.
- If you are hunting for mispriced quality, use valuation and fundamentals filters together through the 195 high quality undervalued stocks to see which opportunities line up with your checklist.
- If you are comfortable going off the beaten path, widen your opportunity set with the 610 high quality undiscovered gems and see which lesser known stocks match your preferred metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com