


EN
Will Sams Club Partnership Change Affirm Stock Narrative
- Affirm, Inc. has entered an exclusive multi-year collaboration with Sam’s Club, offering eligible members fixed, transparent pay-over-time plans for online purchases now, with in-club access targeted for 2027 and no late fees or compounding interest.
- Affirm Holdings is pairing its strongest reported profit quarter and leadership reshuffle with a major retail partner rollout. This development could test how its underwriting, unit economics, and product adoption hold up as volumes potentially shift toward larger ticket, recurring Sam’s Club traffic.
- We will now examine how Affirm Holdings’ new Sam’s Club collaboration could influence the existing investment narrative around growth and profitability.
Scan how Affirm Holdings’ Sam’s Club push compares with other consumer finance plays primed for volume shifts by reviewing the hand picked 21 high quality undiscovered gems in the space.
Affirm Holdings Investment Narrative Recap
To own Affirm Holdings, you need to believe its underwriting, technology and merchant partnerships can support growing pay over time usage while keeping credit losses and funding costs under control. The Sam’s Club deal plugs directly into that view, but the financial impact will depend on how much member adoption offsets the impending loss of another large enterprise partner.
In the near term, the key catalyst remains execution around volumes, unit economics and credit performance as fiscal 2027 ramps, especially with more 0% APR offers that lean on merchant subsidies. The biggest risk remains the same: competition, funding reliance and exposure to weaker U.S. consumer health could pressure margins even if Sam’s Club volumes build.
The most relevant recent development alongside Sam’s Club is Affirm’s strongest reported profit quarter and the leadership reshuffle that moved Michael Linford to president and put Pat Suh over global markets. Management is signaling focus on the core franchise while Max Levchin turns to longer term products.
For you, that pairing matters. A profitable base, a clearer org chart and the Sam’s Club rollout all converge on the same test: whether Affirm can scale large, recurring merchants while keeping revenue less transaction costs near guided levels and credit quality steady, despite the continued use of less profitable 0% products and higher risk funding.
Affirm Holdings' analyst narrative points to forecast revenues of US$8.5b and consensus earnings of US$1.5b by 2029, based on an assumed 25.8% yearly revenue growth rate. That earnings outlook implies a decline of US$0.4b from current earnings of US$1.9b rather than an increase, even as analysts present the 2029 targets as the basis for their valuation work.
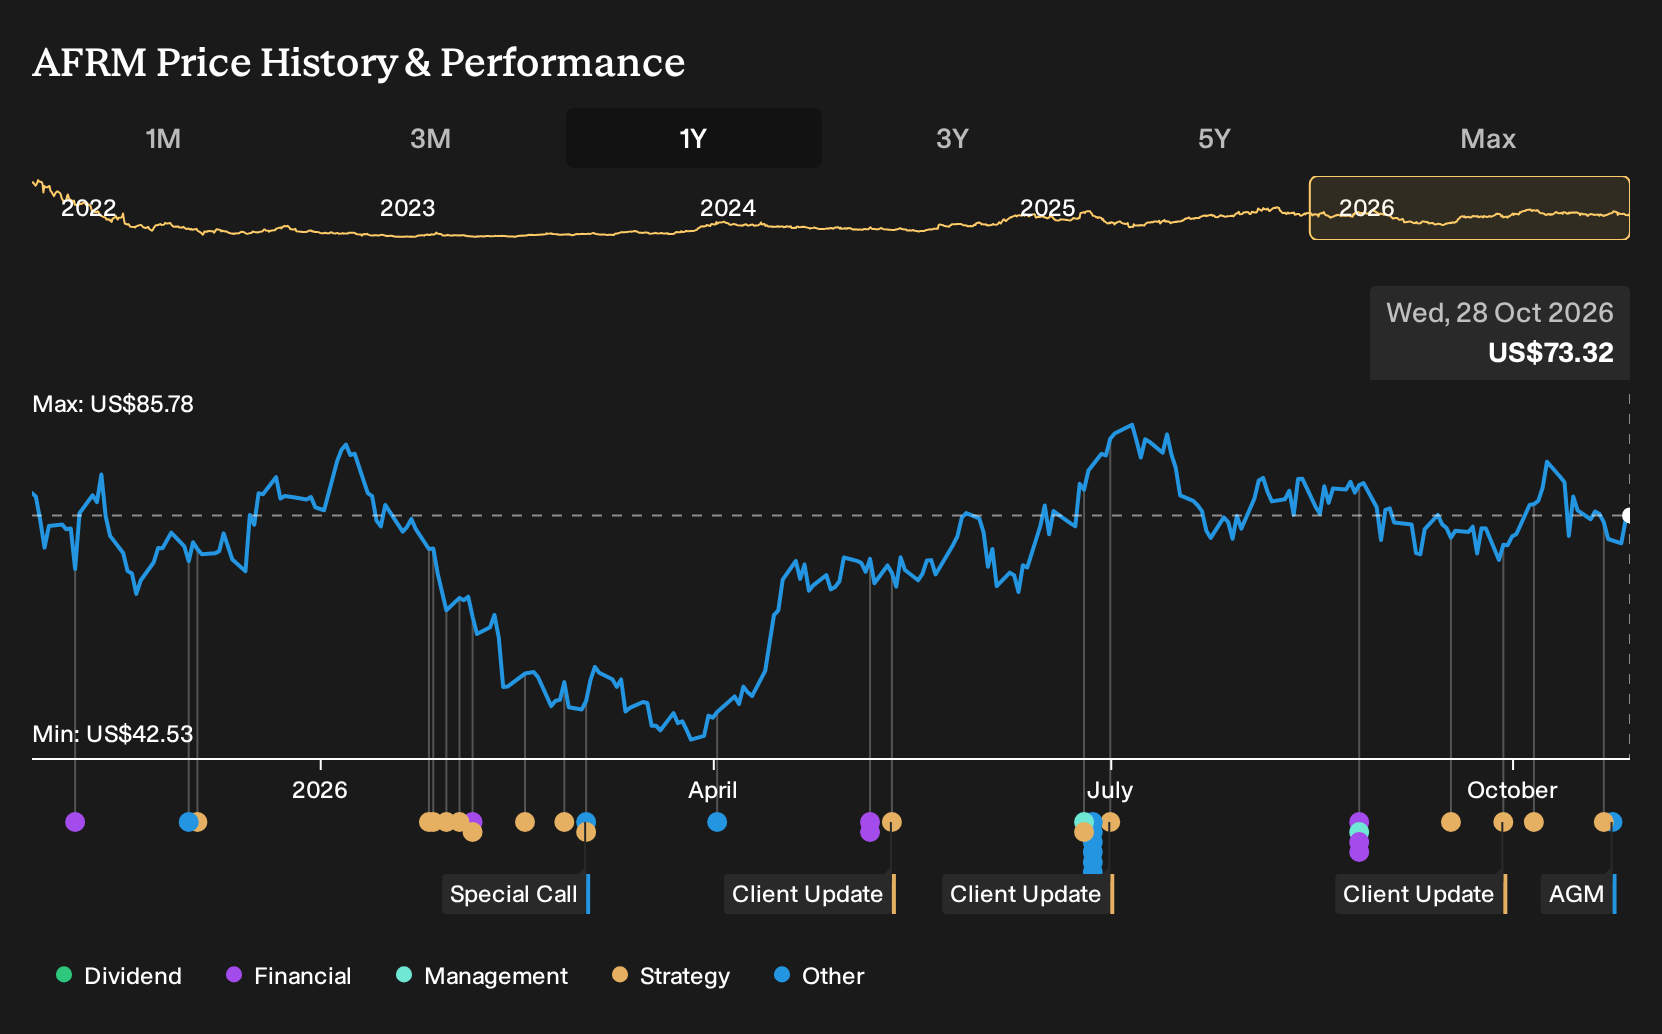
Uncover why Affirm Holdings' fair value indicates a 37% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One alternate view puts consumer caution at the center of the Affirm Holdings story. The most bearish analysts assumed annual revenue growth of 22.9% and earnings of about US$1.2b by 2029, versus US$1.9b today. That is a much more pessimistic path, and it came before this Sam’s Club agreement, which could prompt fresh estimates. Readers should compare both sets of expectations and decide which feels closer to their own view.
Explore 5 other Affirm Holdings fair value estimates, including one that suggests as much as 16% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Affirm Holdings research is our analysis highlighting 5 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Affirm Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Affirm Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Affirm Holdings?
Once you have a view on Affirm Holdings, it can help to compare that thesis against other opportunities that fit different risk profiles, income needs or balance sheet priorities. The Simply Wall St Screener can surface sets of stocks that match what you care about most, rather than leaving you to scroll through tickers one by one.
- If you want income potential with staying power, focus on companies screened for robust yield and resilience by reviewing the 5 dividend fortresses available right now.
- If capital preservation and steadier profiles matter more to you, concentrate on businesses that pass strict risk filters through the 30 resilient stocks with low risk scores tailored for that purpose.
- If you prefer stronger balance sheets and fundamentals, aim your attention at companies that clear rigorous financial health checks via the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com