


EN
Nabtesco (TSE:6268) Could Be 17% Undervalued After Fresh Cash Flow Commentary
Fresh analyst commentary on Nabtesco (TSE:6268) has focused on its ability to turn equipment sales and services into recurring free cash flow, prompting renewed debate over whether today’s valuation reflects that cash generation.
Recent trading paints a mixed picture for Nabtesco. The share price is up 3.15% over one day and 1.45% over the past week, yet it is down 7.57% over 30 days. At the same time, a 15.40% year to date share price return and 17.33% one year total shareholder return suggest that longer term momentum has been stronger than the latest pullback.
Compare Nabtesco's cash flow story with hand picked industrial peers by screening for 16 high quality undervalued stocks that pair recurring cash generation with solid balance sheets.
Nabtesco now trades at a double discount, both to some analyst targets and to one intrinsic value estimate, after a strong multi year run. Is that caution a warning sign, or an opportunity for patient investors?
Most Popular Narrative: 17% Undervalued
Nabtesco last closed at ¥4,420 while the most widely followed narrative anchors fair value around ¥5,346. As a result, the market conversation is circling around whether free cash flow and earnings quality justify that gap.
The main factor that has to go right is that Nabtesco continues to translate its focus on earnings quality into results that outperform the consensus view often enough for that track record to remain credible.
The current narrative that Nabtesco is undervalued implies that the 2.13% share price move around the latest earnings surprise does not fully reflect the earnings power suggested by the recent numbers for the stock.
See why 2 investors see Nabtesco as 17% undervalued.
Result: Fair Value of ¥5,346 (UNDERVALUED)
Still, that earnings driven story for Nabtesco can quickly lose traction if quarterly results stay close to analyst estimates or if the slimmer business mix magnifies any slowdown.
Find out about the key risks to this Nabtesco narrative.
Another View: Nabtesco Through The P/E Lens
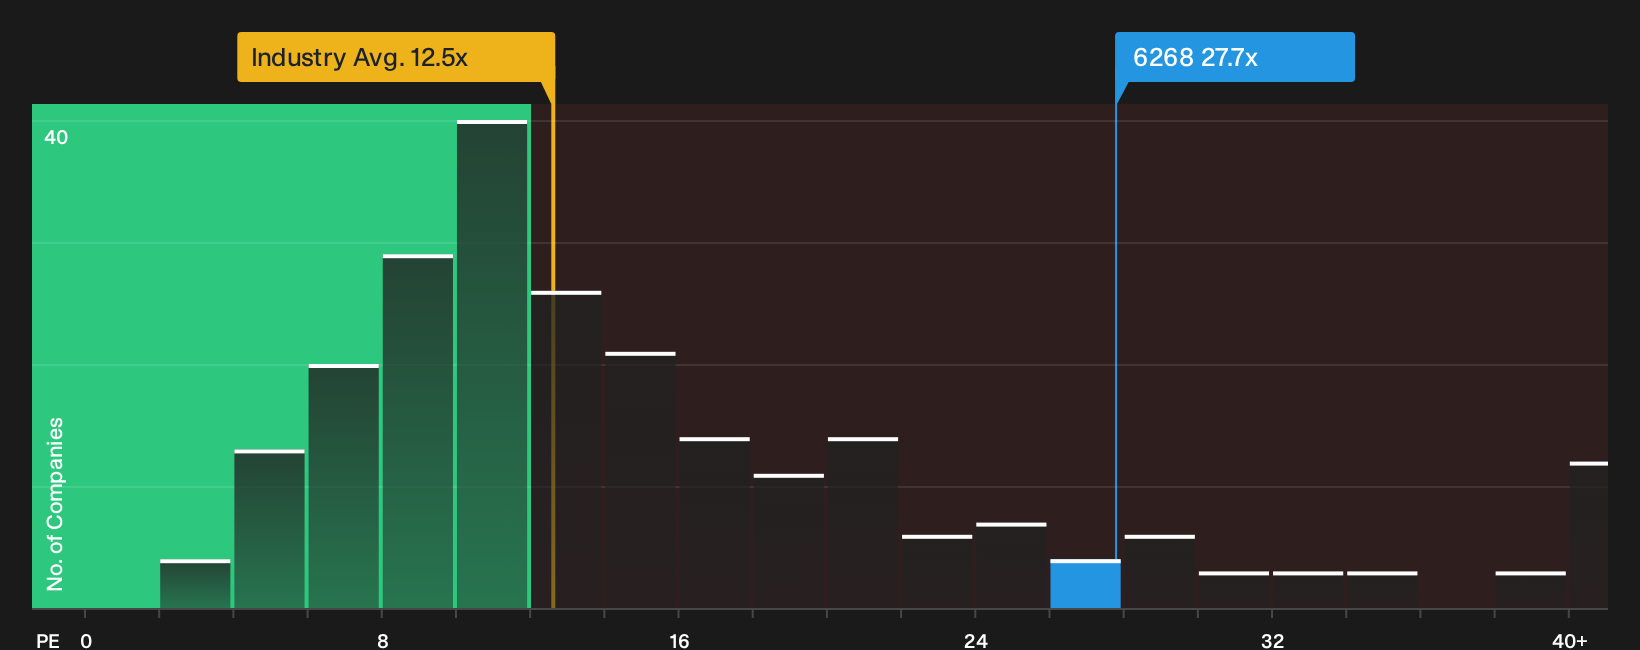
Nabtesco screens as cheap on some models, yet the picture shifts when you look at the P/E. The stock trades on 27.7x earnings, which is more than double the JP Machinery sector at 12.5x and above its own fair ratio of 19.8x. Is that premium comfort, or concentration risk if sentiment cools?
To see how this earnings multiple compares in more detail, including against peers and that fair ratio the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Nabtesco can be confusing, so act promptly, review the data yourself, and then weigh up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Nabtesco?
If Nabtesco has caught your attention, broaden your watchlist now and use the Simply Wall Street Screener to uncover other opportunities you might be missing.
- Target stability first by reviewing a list of solid balance sheet and fundamentals (23 results) that can help anchor your portfolio when markets feel noisy.
- Hunt for quality at a sensible price through a 16 high quality undervalued stocks that pairs strong fundamentals with more conservative valuations.
- Prioritise reliable income by scanning a 29 dividend fortresses that focus on higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com