


EN
Georgia Factory Expansion Could Be A Big Moment For Mitsubishi Heavy Industries Stock
- Mitsubishi Heavy Industries, through Mitsubishi Power Americas, has backed a US$490m expansion of the Savannah Machinery Works facility in Georgia. This increases turbine manufacturing capacity and supports more than 220 additional roles across power generation equipment for customers in the Americas.
- The Georgia expansion anchors more production and jobs in the US. This could reshape Mitsubishi Heavy Industries' cost base and supply resilience for energy equipment across the region.
- The focus now turns to how Mitsubishi Heavy Industries' investment narrative aligns with this US$490m US manufacturing expansion and capacity build out.
Scan other infrastructure players tied to the energy build out by reviewing the hand picked 42 power grid technology and infrastructure stocks alongside Mitsubishi Heavy Industries' latest US manufacturing push.
Mitsubishi Heavy Industries Investment Narrative Recap
To own Mitsubishi Heavy Industries, you need to be comfortable with a complex industrial group that leans heavily on large, long duration projects in energy, infrastructure and defense. The key near term swing factor is how efficiently that record order backlog above ¥14t converts into revenue and cash, especially as the business shifts more into higher margin services.
The Savannah Machinery Works expansion looks directionally aligned with that execution story rather than a new catalyst on its own. It may marginally support Energy Systems delivery in the Americas, while the main risk remains operational, including export control constraints from China and any repeat of goodwill issues in Industrial Power Solutions.
Among recent developments, the stand out operational data point is the record Q1 FY 2026 order intake of ¥2,022.4b. That backlog depth is what gives the Mitsubishi Heavy Industries story its line of sight on future work, especially in gas turbine combined cycle projects and related services that management is prioritising.
Seen next to that order momentum, the US$490m Georgia expansion reads as capacity being built against an already contracted pipeline rather than a speculative bet. The execution test for shareholders is whether these new factories, the ITO efficiency program and portfolio reshaping away from Logisnext combine to lift underlying margins without leaning on one time gains.
Mitsubishi Heavy Industries Forward Assumptions And Valuation Anchors
Analyst models around Mitsubishi Heavy Industries lean on a fairly specific earnings path. Forecasts build toward revenue of ¥6,695.3b and earnings of ¥615.3b by 2029, using an assumed annual revenue growth rate of 9.3%. The implied move in profit is an increase of about ¥206.3b from earnings today of ¥409.0b to that 2029 consensus level.
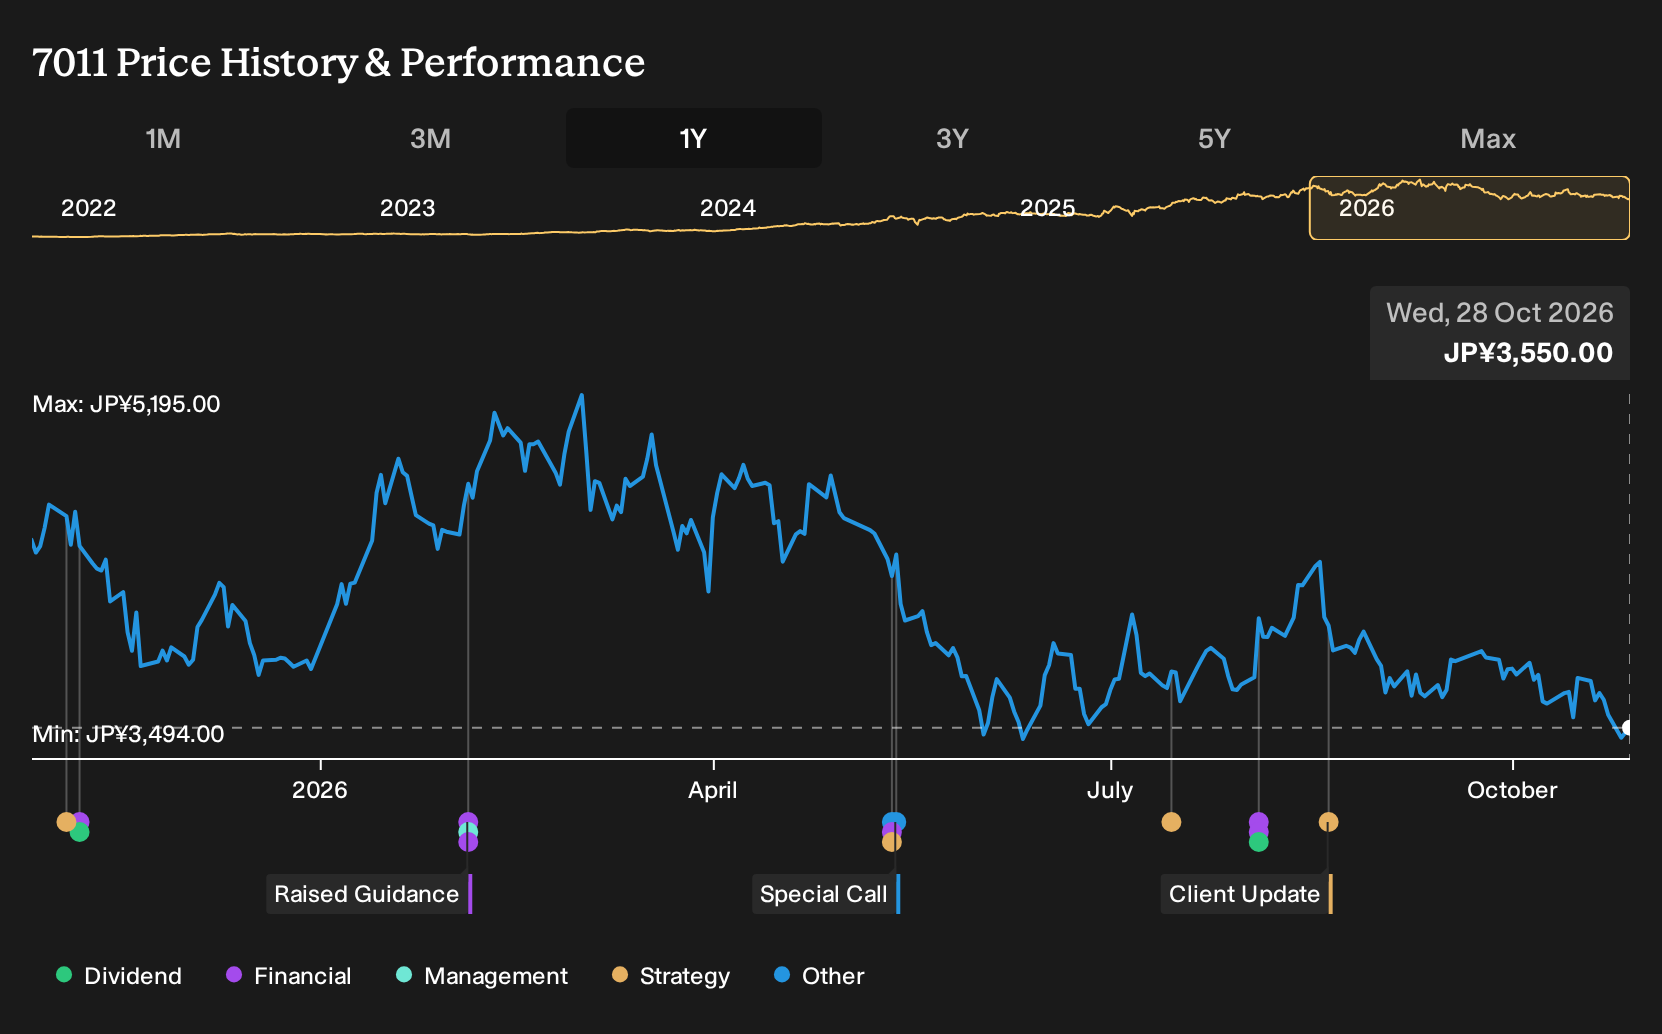
Uncover how Mitsubishi Heavy Industries' fair value indicates a 54% potential upside to its current price before sentiment around Mitsubishi Heavy Industries' order book shifts.
Exploring Other Perspectives
One alternate view puts Mitsubishi Heavy Industries’ reliance on one time gains front and center. The most cautious analysts, who were pencilling in 6.6% annual revenue growth to about ¥6,224.5b and earnings of ¥494.2b by 2029, see margin pressure as a real risk. They may revisit that stance once this US$490m Georgia expansion beds in.
Explore 5 other Mitsubishi Heavy Industries fair value estimates, including one that suggests as much as 11% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mitsubishi Heavy Industries research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Mitsubishi Heavy Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mitsubishi Heavy Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Mitsubishi Heavy Industries?
If you want to stress test your thesis on Mitsubishi Heavy Industries and broaden your watchlist, use the Simply Wall St Screener to compare it with other businesses that share similar qualities or offer a different balance of risk and reward.
- For investors who want a margin of safety backed by fundamentals, scan a curated set of businesses through 16 high quality undervalued stocks.
- If capital preservation and steadier profiles matter most to you, focus your search on companies screened as 22 resilient stocks with low risk scores.
- When you want resilient balance sheets and robust financial foundations, start with our list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com