


EN
Special Dividend Plan Might Change The Case For Investing In SGX Stock
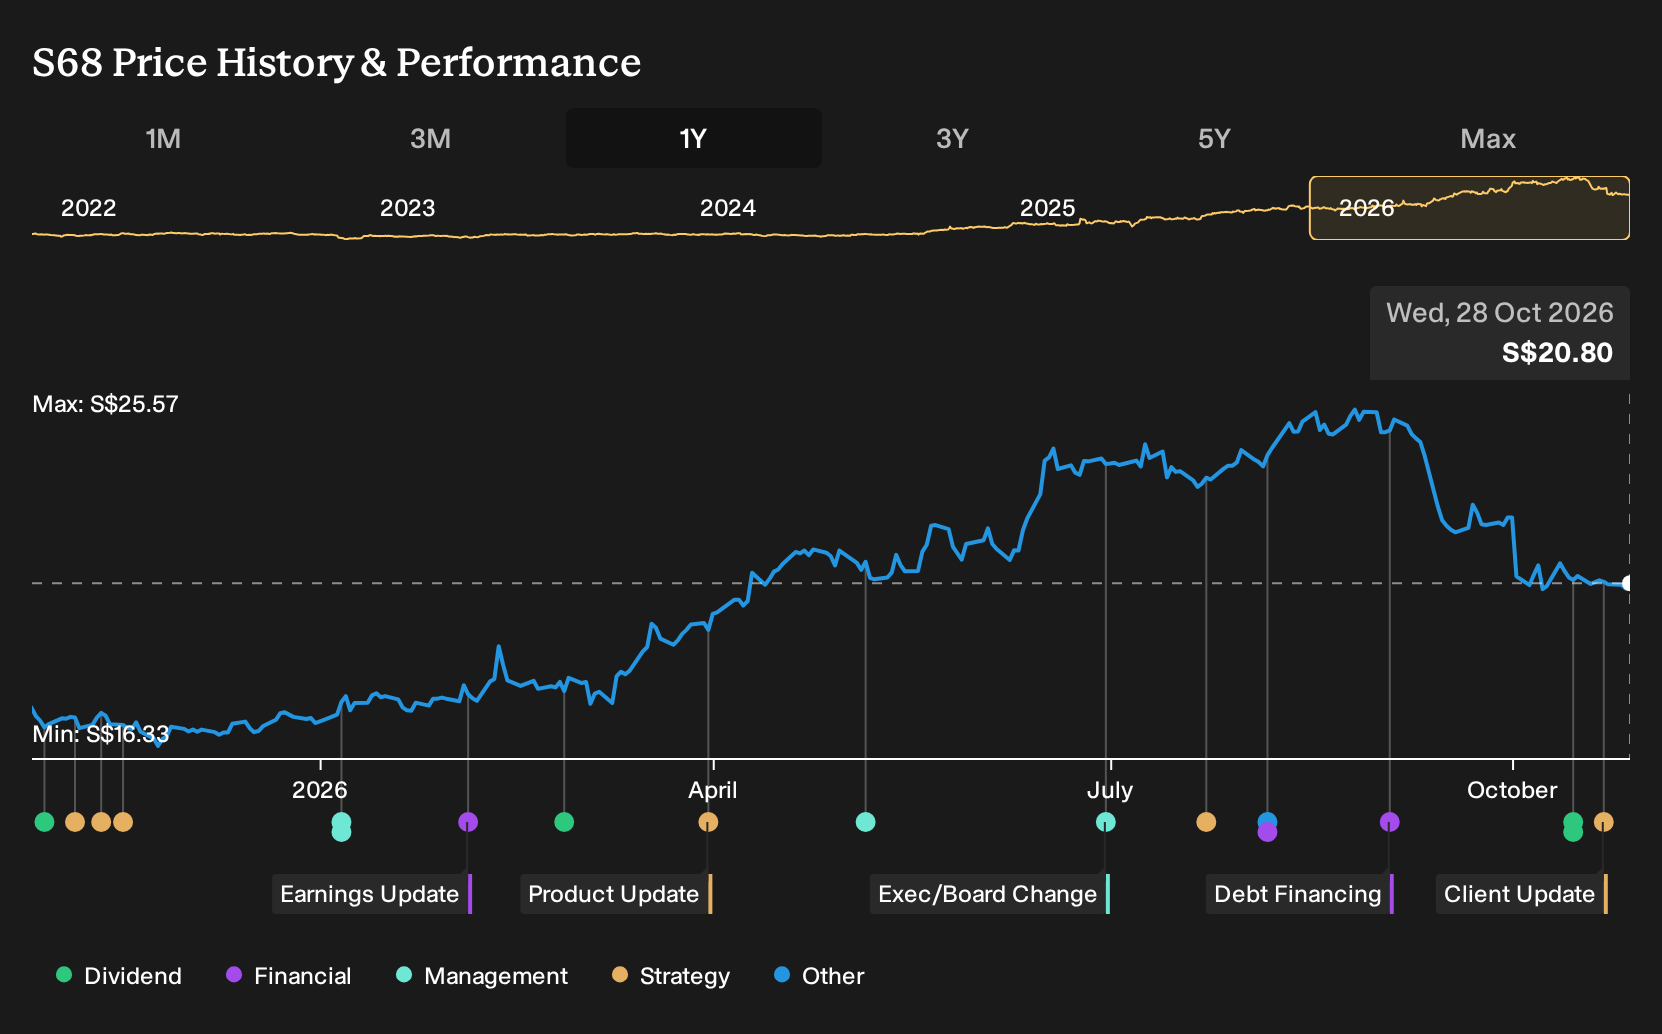
- Singapore Exchange Limited has proposed a one off additional tax exempt dividend of 12.5 cents per share and a higher final tax exempt dividend of 11.5 cents per share for FY2026, both subject to approval at the AGM held on 23 October 2026.
- These cash returns highlight how Singapore Exchange is using its balance sheet to reward shareholders while it continues to invest in multi asset expansion, FX growth and technology upgrades outlined in its broader capital and expense plans.
- We will now examine how Singapore Exchange's one off additional dividend could reshape the investment narrative built around multi asset expansion.
Scan beyond Singapore Exchange and see how other capital-market operators are rewarding investors with special payouts and disciplined balance sheets inside the curated list of solid balance sheet and fundamentals (207 results).
Singapore Exchange Investment Narrative Recap
To own Singapore Exchange, you need to believe its push into multi asset derivatives, FICC and SGX FX can keep attracting activity, while higher FY2027 capex and expenses translate into better platforms and product rollout. The recent one off and higher final dividends are a capital return story and do not materially shift that operating thesis.
The most important near term swing factor remains whether rising costs and the planned S$100m technology spend convert into stronger client usage and fee resilience. The biggest risk is that SGX FX volumes and multi asset activity do not support pricing power, which could pressure fee yields and crimp operating leverage.
The Memorandum of Collaboration with The Philippine Stock Exchange looks most relevant here, because it ties directly into SGX multi asset and regional connectivity ambitions. If the partnership broadens ETF, derivatives and cross border product access, it could support liquidity and usage across both markets over time.
That type of link up also connects with existing catalysts such as the Global Listing Board, the SGX FX franchise and efforts to deepen cash equity activity. Execution risk remains real. New products, regulatory alignment and technology work all need to be delivered properly before any impact on trading volumes or fee income shows up.
What The Analyst Scenario Implies For Singapore Exchange
Singapore Exchange's narrative projects SGD 1.9b revenue and SGD 959.1m earnings by 2029. This assumes 6.7% yearly revenue growth and an earnings increase of about SGD 260.7m from current earnings of SGD 698.4m.
Uncover why Singapore Exchange's fair value indicates a 15% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view says the real swing factor for Singapore Exchange is not FX or multi asset at all. It is whether equity derivatives pressure lingers. The most cautious analysts were only pencilling in revenue of about SGD 1.6b and earnings near SGD 769.5m by 2029 before this news. That is a much harsher story than consensus. These forecasts were set before the special dividends and the new collaboration with The Philippine Stock Exchange, so you may see them evolve as analysts refresh their models. Use that gap in expectations as a prompt to compare several viewpoints before deciding how this fits your own portfolio plan.
Explore 4 other Singapore Exchange fair value estimates, including one that suggests as much as 15% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Singapore Exchange research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Singapore Exchange. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Singapore Exchange's overall financial health at a glance.
Looking For More Investment Ideas Beyond Singapore Exchange?
Once you have formed a view on Singapore Exchange, it can help to widen the lens and compare it with other opportunities that fit different portfolio goals using the Simply Wall St Screener.
- For investors hunting for mispriced opportunities with strong fundamentals, scan through 195 high quality undervalued stocks that may warrant a closer look.
- If your priority is resilience and capital preservation, filter for companies in the 223 resilient stocks with low risk scores to see which ones align with a lower volatility approach.
- For those willing to do extra homework in return for less crowded ideas, sort through 610 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com