


EN
UMB Financial (UMBF) Stock Could Be 42% Undervalued On Excess Returns
UMB Financial has delivered a 123.6% share price gain over the past three years, which naturally raises a pointed question for holders and potential buyers alike. Is the current price around US$133.80 adequately explained by the returns the bank earns on the capital it puts to work?
- The 123.6% move over three years puts a spotlight on whether UMB Financial's long term return on capital can support a meaningfully higher equity valuation than it had before that run.
- For a regional banking group that relies heavily on disciplined loan underwriting and fee income, the key valuation driver is how efficiently management can recycle customer deposits and equity into profitable assets without eroding credit quality or raising funding costs too sharply.
- What if you looked at UMB Financial through its earnings instead? See what UMB Financial's 11.1x P/E says about the price.
The issue now is whether the returns UMB Financial earns on its capital are strong and durable enough to make today's share price look sensible.
If you want to test the same question about returns on capital across a wider field, compare UMB Financial with companies in the solid balance sheet and fundamentals stocks screener (24 results).
Is UMB Financial a Bargain on Excess Returns?
The Excess Returns model looks at how much profit UMB Financial can earn above the return investors usually demand on its equity. In this view, the bank starts from a Book Value of $101.87 per share and an Average Return on Equity of 12.33%, which translates into a Stable EPS estimate of $14.53 per share based on inputs from 11 analysts. After subtracting a Cost of Equity of $9.54 per share, that leaves an Excess Return of $4.98 per share that the model assumes can be sustained.
Those surplus returns are then applied to a higher Stable Book Value of $117.81 per share, sourced from 12 analyst estimates, to work out what that stream of value might be worth to shareholders over time. On these assumptions, the Excess Returns framework puts UMB Financial's estimated intrinsic value substantially above the current share price of $133.80, which suggests the market is not fully pricing in the level of profitability implied by these inputs yet. Find out what UMB Financial could be worth using our Excess Returns estimate.
The UMB Financial Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for UMB Financial pick up where the earlier valuation puzzle leaves off and spell out which paths for growth, profitability and earnings would make the current share price look high, low or broadly in line. Each scenario ties a grounded fair value estimate to a specific mix of potential catalysts and risks, so you can track over time which version of UMB Financial's story appears to be taking shape.
One of the top community narratives on UMB Financial: 18% undervalued
"Expansion of UMB Financial’s commercial and industrial lending across Texas, California, Utah and other Heartland markets points to ongoing market share gains..."
Discover why this Narrative puts UMB Financial at 18% undervalued.
The share price is only one signal in the UMB Financial story
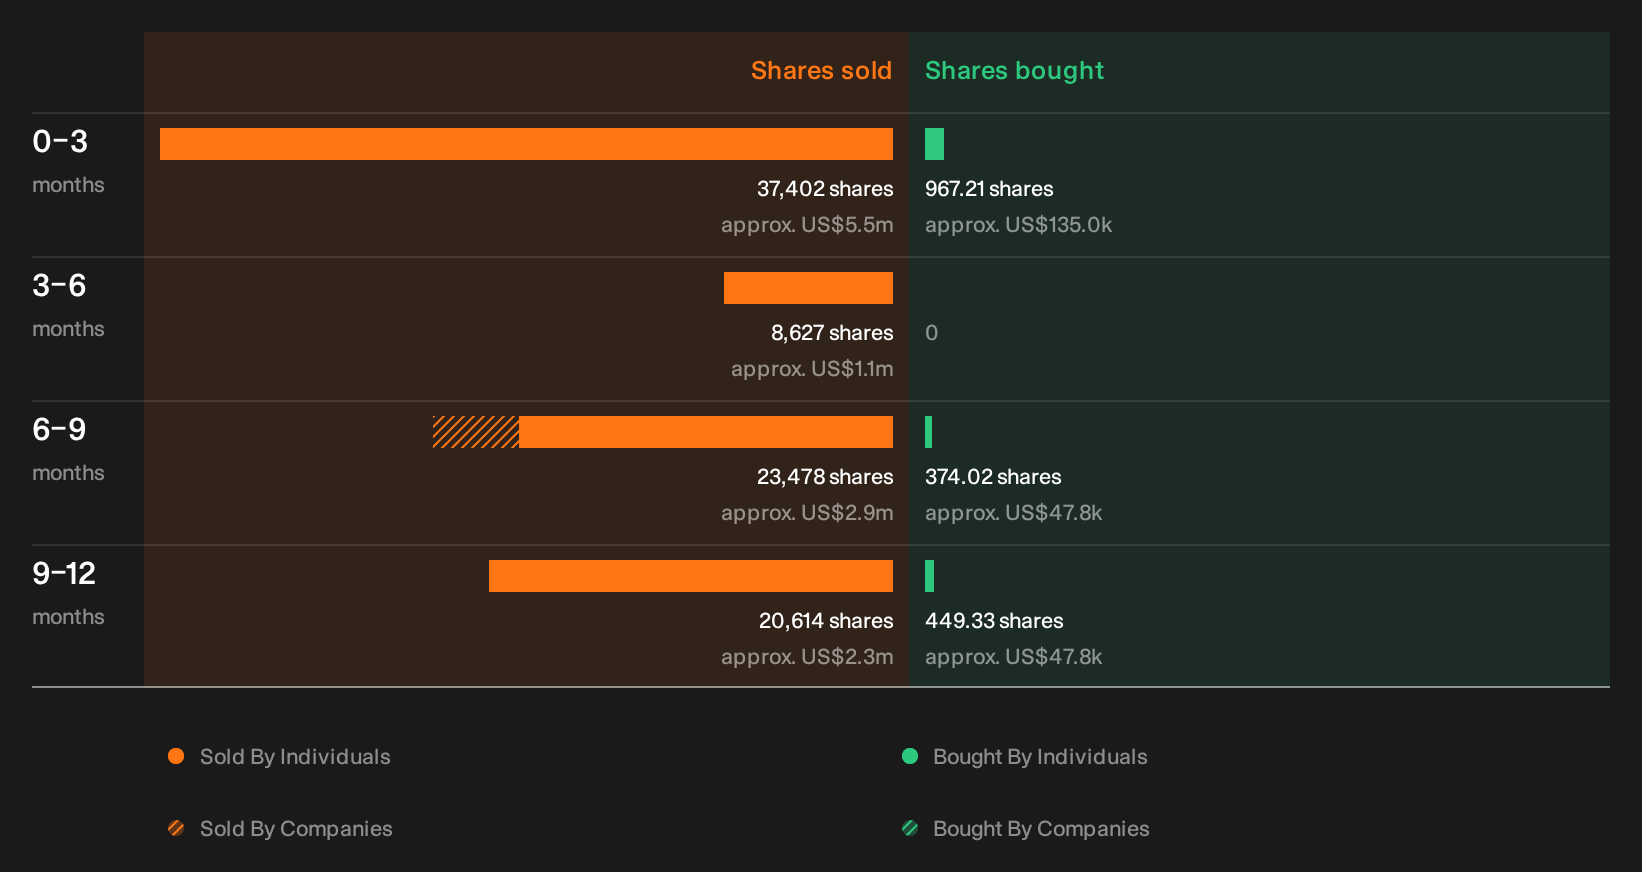
UMB Financial’s valuation picture is detailed, yet our checks also point to recent selling by people inside the business, and the who, how much, and what it might mean are still for you to review. See the recent insider selling flagged for UMB Financial.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com