


EN
What Humana Holders Saw Early
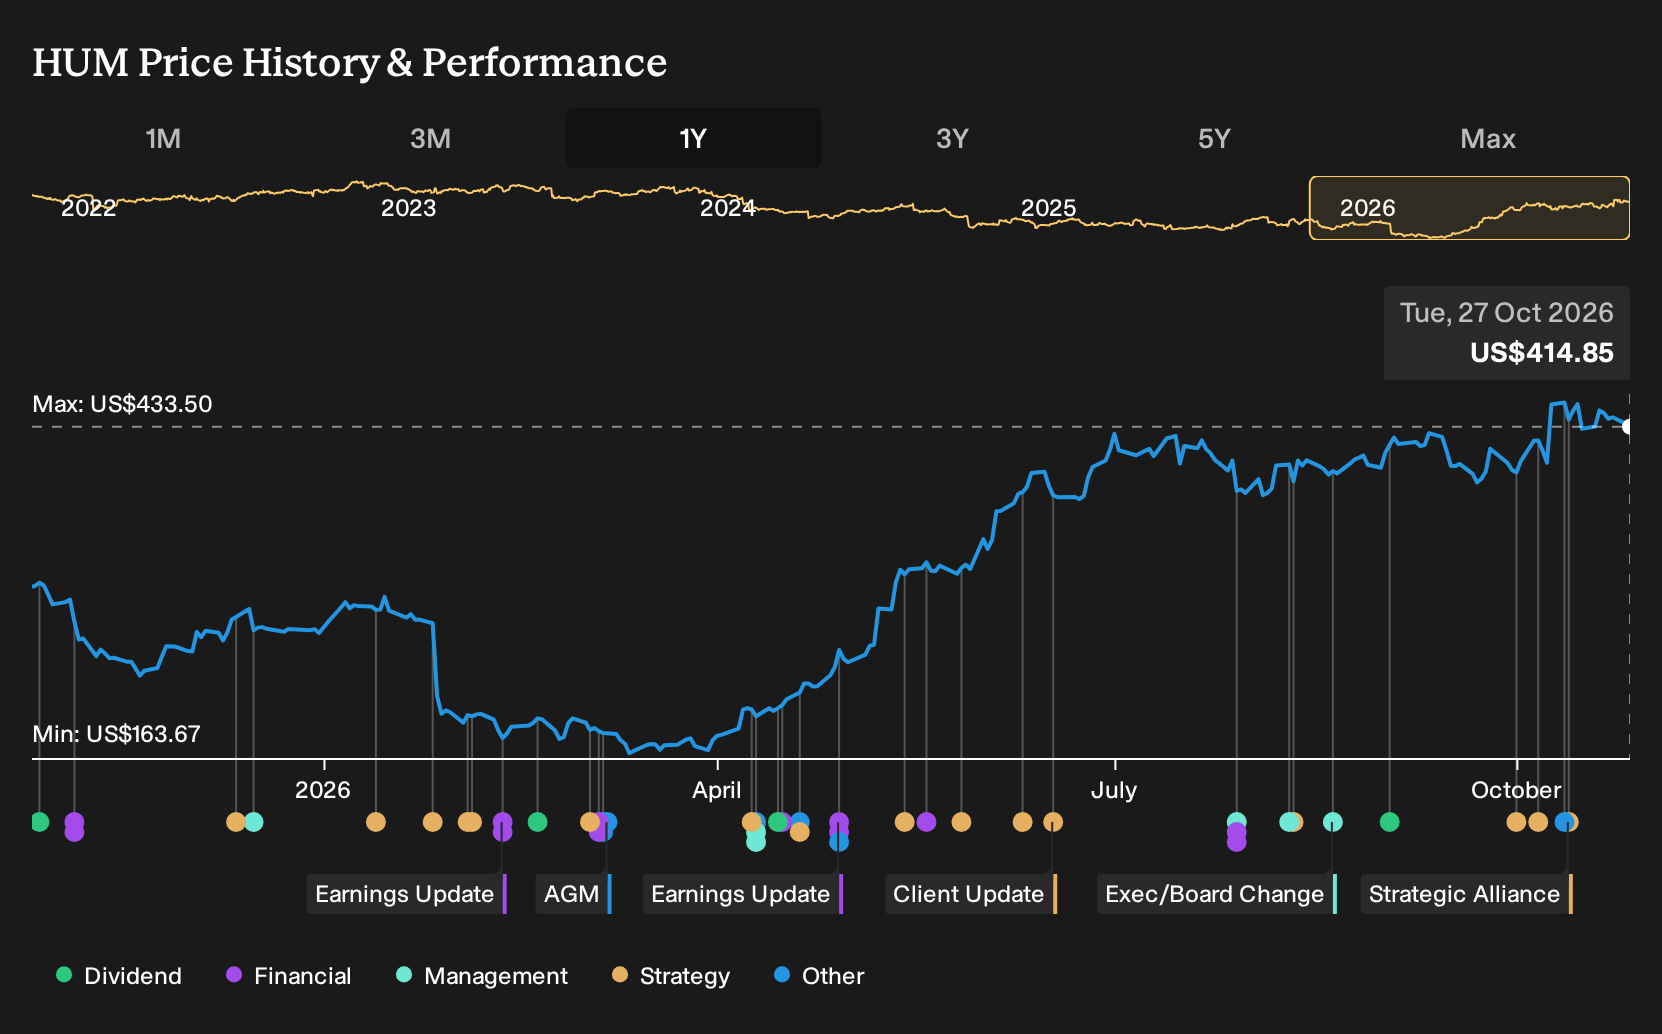
Humana spent the past year juggling higher medical costs, Medicare Advantage market exits, and a fresh overbilling settlement, yet the share price quietly told a different story. Holding Humana over the past year would have returned 42.3%, including dividends. If you had bought on 27 October 2025, with analysts split between bullish aging demographic tailwinds and reform-driven margin risk, what exactly in the record back then could have justified taking that ride?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
This theme extends beyond Humana. See which of 34 healthcare AI stocks may still merit a closer look.
The Two Humana Stories Investors Had To Choose Between
The shares cost US$292 at the start of the period, and anyone looking at Humana then had to decide which of two stories about Medicare Advantage and cost pressures felt more realistic.
On the optimistic side, the May 2025 bull narrative put Fair Value at US$353, or 21% above the start price, assuming aging demographics and CenterWell growth would support higher efficiency and more predictable profitability.
The April 2025 bear view set Fair Value at US$250, or 14% below the start price, stressing reform risk, rising healthcare costs, and Humana’s reliance on Medicare Advantage reimbursement.
What The Results Put To The Test For Humana
Humana’s Q2 2026 report showed revenue at US$40,867m and net income at US$694m, ahead of Q2 2025 on both counts, with net margin steady at 1.7%. That outcome gave the optimistic Medicare Advantage and CenterWell story some support, although the margin profile still left the higher profitability leg of the bull case unproven.
The useful takeaway is clear. When a thesis leans on better margins, you track not just revenue and profit, but the percentage margin line and judge whether it is actually moving.
What Humana's Price Now Asks You To Believe
Humana trades at US$415 today. The selected Narrative’s Fair Value sits below that level, since it argues that a lot of the Medicare Advantage margin repair and Stars recovery story is already embedded in the quote.
This view hinges on whether cost cuts, Stars gains and CenterWell investments truly sustain a higher earnings base. A buyer at today’s price effectively assumes Medicare Advantage margin restoration holds. How do rising drug trends, compliance costs and execution risk on plan pruning affect that bet?
"The current figures on margin targets, cost trend assumptions, plan exits, and balance sheet actions suggest that Humana’s share price already reflects successful Medicare Advantage margin restoration and sustained earnings stability. Although Humana is pruning roughly 600,000 lower return Medicare Advantage plans to support its 3% pretax margin goal by 2028, management also expects drug trend to tick modestly higher in 2027."
The price and this Narrative do not agree. → Uncover what this Narrative says Humana is actually worth
Humana And A Parallel Bet
Humana asks you to consider whether Medicare and value-based care earnings can really hold. Nearby, another insurer is wrestling with the same core question.
That other group is investing in care programs that move complex members into closer clinical management. The intent is more durable plan designs when medical trends stay tricky.
It is also using software, data tools and AI to reduce back-office waste and claims friction. Fewer manual processes could support steadier health-plan economics.
Pharmacy contracts built around full rebate pass-through add another angle, aiming for cleaner pricing and stickier clients. If those pieces align, a playbook for managing risks similar to Humana may already be forming.
One Narrative has already put a figure on it. → Uncover the company trading 15% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com