


EN
Is Pinterest (PINS) Stock Already Pricing In Its Earnings Potential?
Pinterest has seen its share price under pressure in recent years, and that puts the focus squarely on what investors are paying for its earnings today. With fresh product news in advertising and a mixed return profile, the key issue is whether the current valuation lines up with what the business is actually earning.
- Over the past 5 years the stock has fallen 53.6%, which raises the question of how much future earnings power is already baked into the current price.
- The rollout of global Programmatic Deals for display and video ads may support expectations for more scalable ad demand and could influence how investors think about Pinterest's long term profit potential.
- There is a second opinion on Pinterest worth weighing. See what analysts think Pinterest's shares could be worth.
The issue now is whether Pinterest's latest share price fairly reflects the earnings that the company is generating today.
If you are weighing Pinterest against other opportunities that also turn on earnings and pricing power, a focused stock screen of 29 high quality undervalued stocks.
Has Pinterest Run Too Far on Earnings?
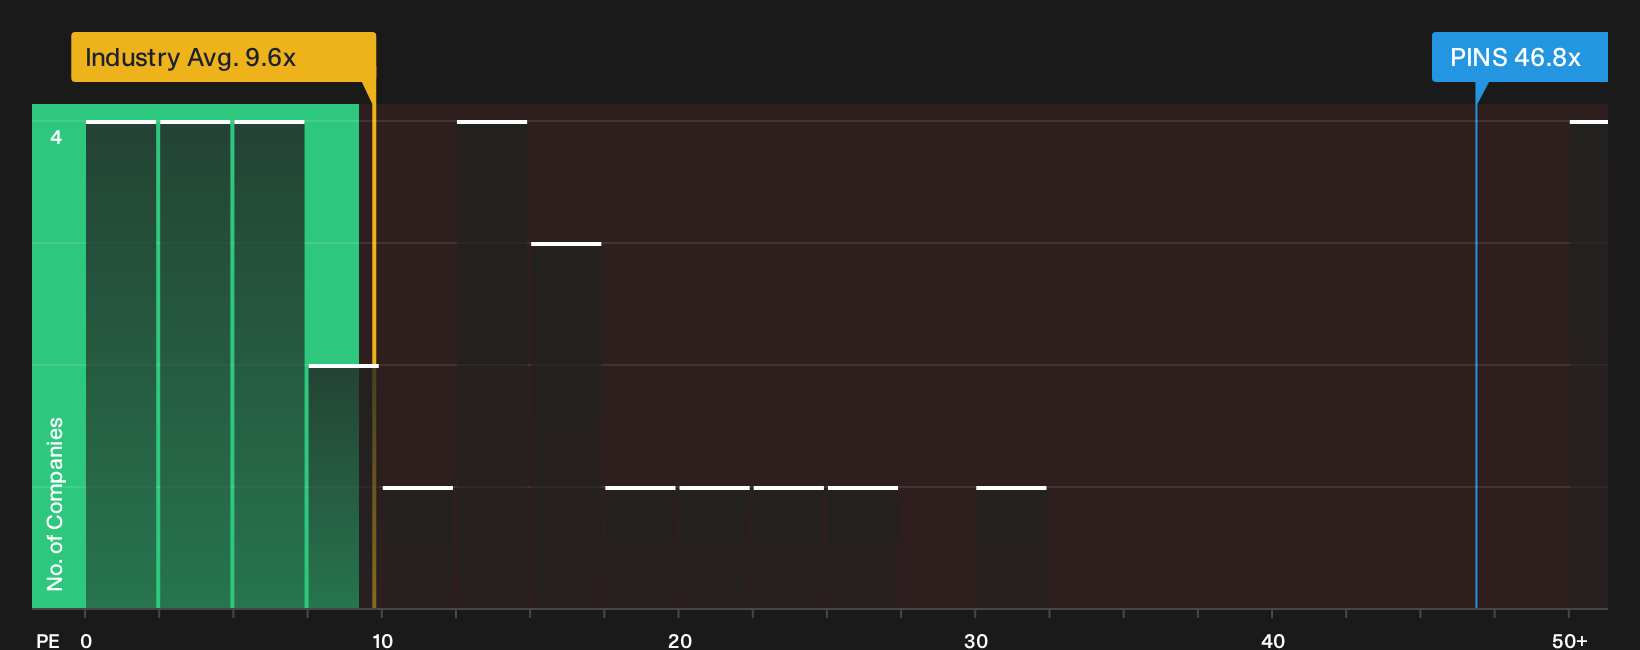
Pinterest is best judged on its P/E multiple because earnings now matter more than a pure user or revenue story. The stock trades on a P/E of 46.8x, which is roughly double the 23.6x peer average and far above the broader Interactive Media and Services group on 9.6x. That is a rich tag for each dollar of profit and signals that the market is already paying a premium for the company’s current earnings base.
On this framework, the tailored fair multiple sits below Pinterest’s current 46.8x, so the shares screen as overvalued on earnings. The launch of global Programmatic Deals may help the ad platform case in investors’ minds, yet the pricing still assumes a stronger earnings profile than the benchmark would suggest. That leaves you weighing whether Pinterest’s business quality and execution justify paying this kind of mark up on the P/E line. Explore the numbers behind Pinterest's P/E valuation.
The Pinterest Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St take the valuation puzzle around Pinterest and turn it into clear sets of forward assumptions that link today's P/E multiple to possible future paths for growth, margins and earnings. Each one lays out its own earnings and cash flow assumptions instead of a single headline multiple or model output, so you can compare those inputs with Pinterest's reported results over time.
One of the top community narratives on Pinterest: 29% undervalued
"The main thing that has to go right is that Pinterest closes the gap between engagement and monetization, particularly in international and SMB segments..."
Discover why this Narrative puts Pinterest at 29% undervalued.
One more piece of the Pinterest story still needs checking
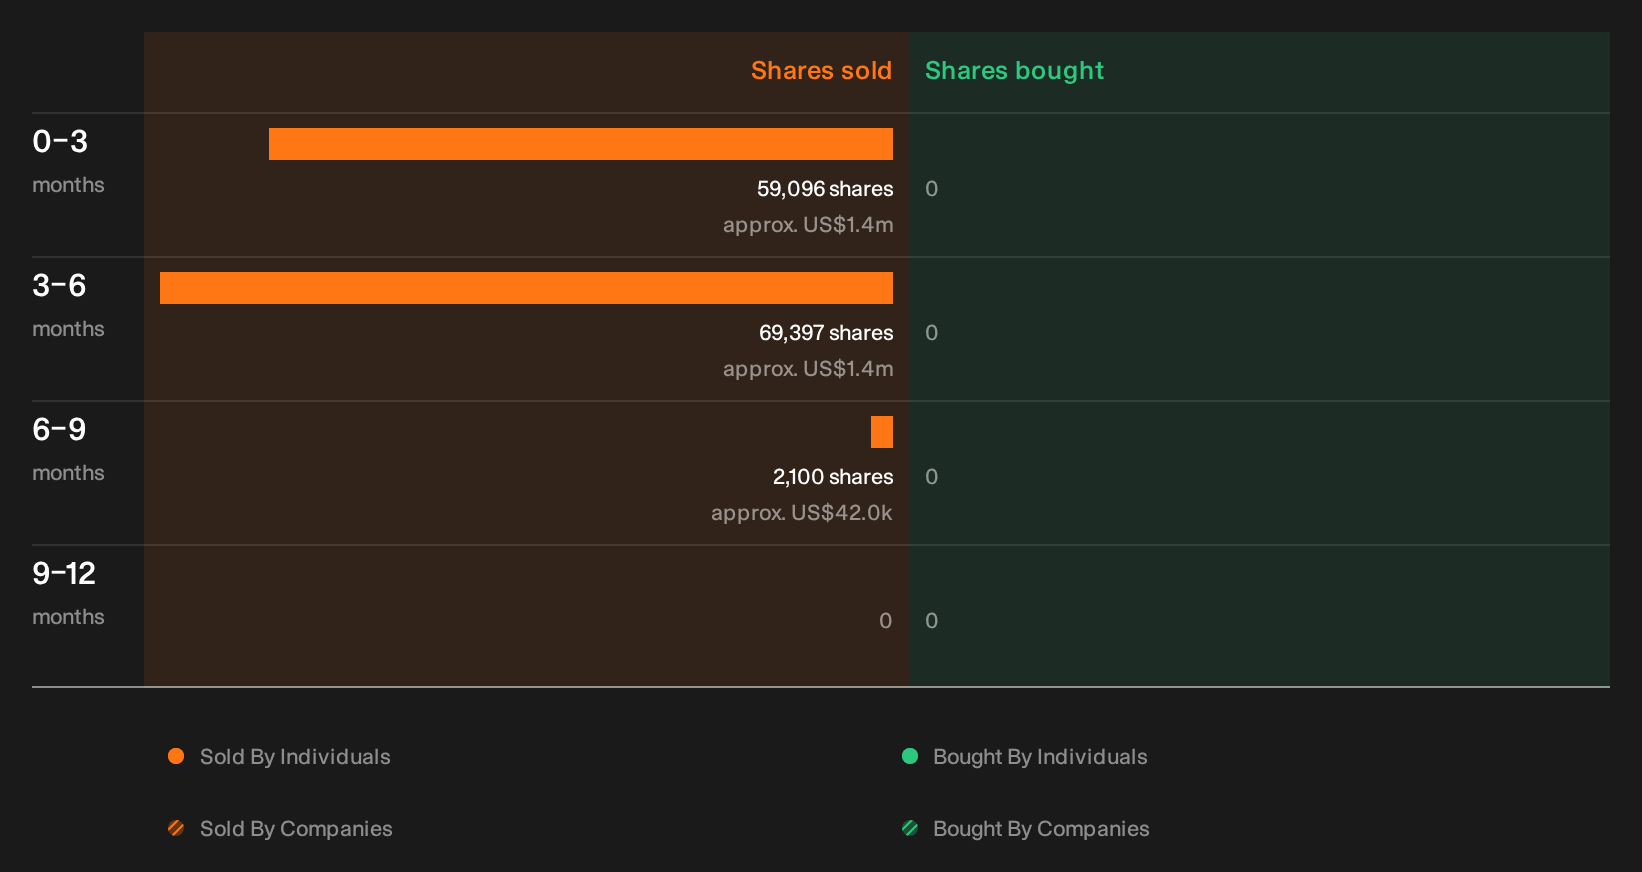
Valuation is only part of the picture for Pinterest, because recent trading disclosures by company insiders can hint at how those closest to the business are acting with their own holdings. See the recent insider selling flagged for Pinterest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com