


EN
What Yalla Group Doubters Saw Before The Drop
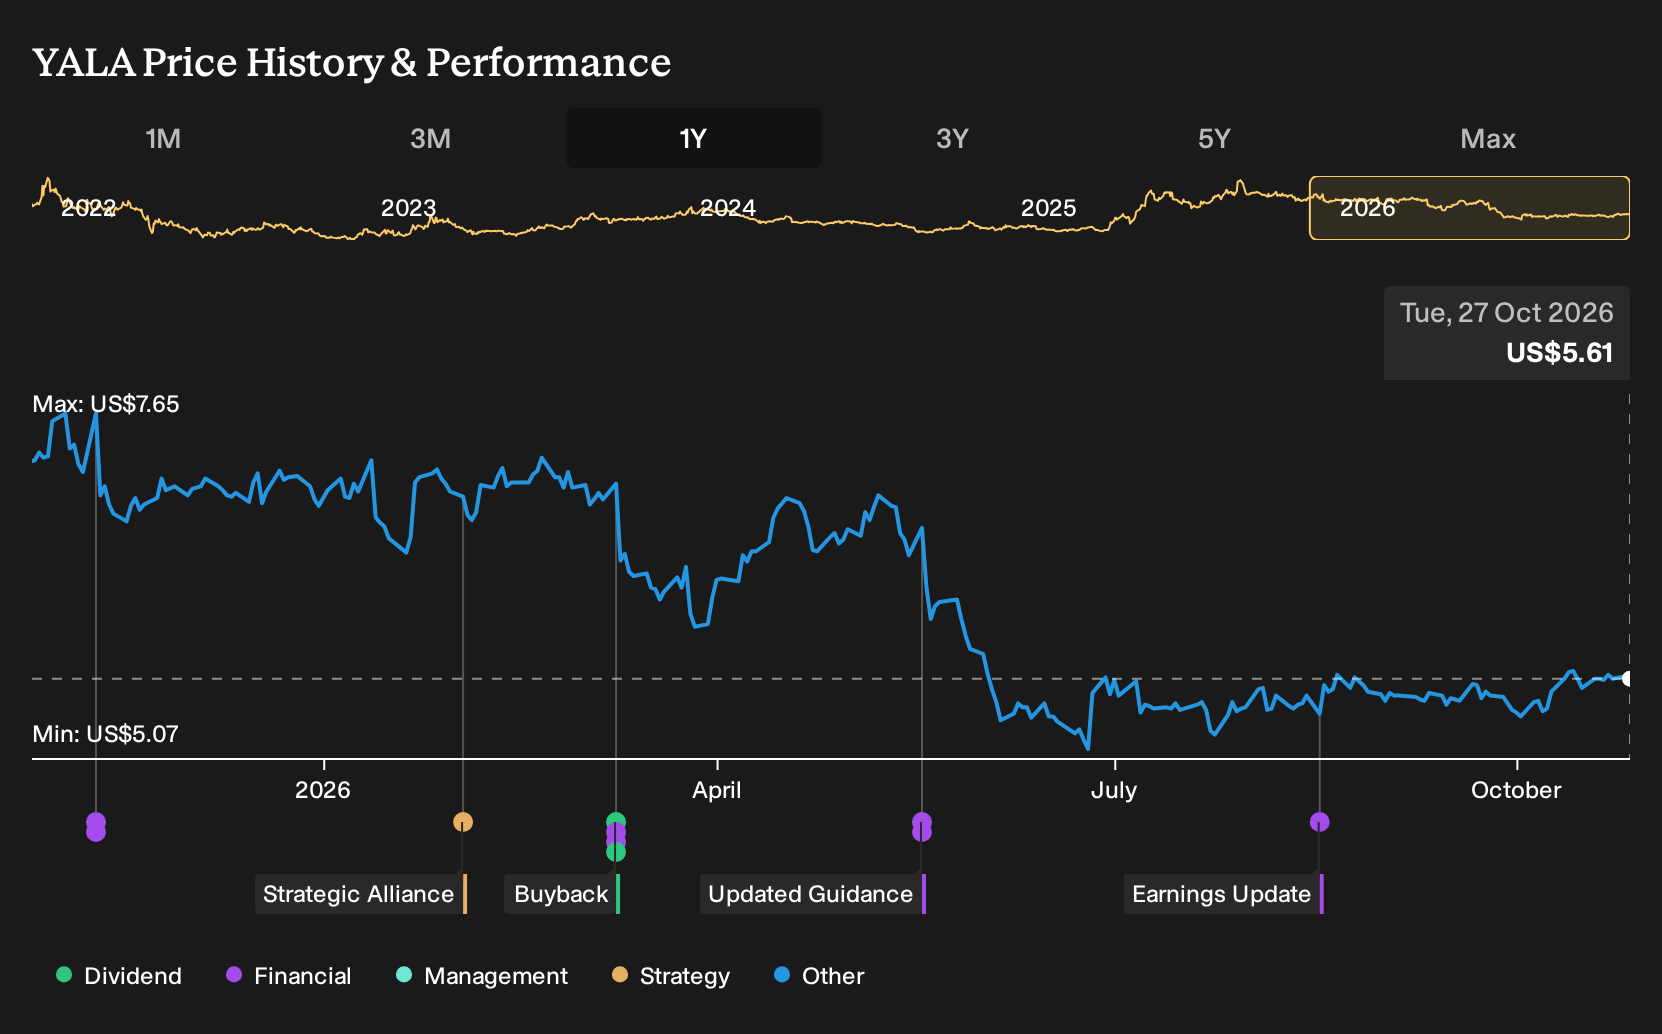
If you had bought Yalla Group on 27 October 2025 and simply held through new game launches, flat revenue guidance and rising geopolitical noise, the result would have stung. For Yalla Group shareholders, the loss over the past year was 23.7%, including dividends. If that decision rested on MENA user growth, high starting net margins and a higher future P/E of 10.4x, which of those pillars did the original case underestimate or misread?
Yalla Group has already moved. Pinpoint other ways to investigate the theme among 16 cryptocurrency and blockchain stocks.
The Argument You Would Have Been Weighing Up On Yalla Group
The shares cost US$7.29 at the start of the period, and anyone looking at Yalla Group then had to choose between two very different stories.
The optimistic case leaned on robust MENA expansion and product diversification. Analysts said this could justify a Fair Value of US$9.27, effectively a price implied by assumptions like 5.4% annual revenue growth and a future P/E of 10.4x.
The cautious view focused on heavier regulation, data privacy pressure, and fiercer competition. A Fair Value of US$6.50 was built around concerns that rising compliance costs might squeeze margins down to about 39.9%.
What The Results Changed For Yalla Group
The strongest new fact was Yalla Group’s Q1 2026 update that gaming services brought in US$30.3m, or 38.3% of revenue, helped by early traction from new titles. That supported the view about diversification. However, Q2 2026 results showed revenue and net income both fell, and net margin slipped from 43.5% to 38.5%. Taken together, the evidence pointed in different directions.
The key assumption that influenced the analysis was margin resilience during product shifts and geopolitical stress. For any other stock, you would track reported net margin and segment mix each quarter against the original thesis, then decide what you are really paying for.
What You Would Be Paying For In Yalla Group Today
Today Yalla Group trades at US$5.61. The selected Narrative views its Fair Value as higher than that price, based on newer games, AI supported services, and buybacks offsetting pressure on legacy social products.
For that higher figure to be justified, a buyer today would need confidence that game and AI offerings can develop into a larger, profitable share of revenue.
"The key factor is that investment in new games and AI tools converts higher marketing and R&D spending into game services that can represent a larger share of the revenue mix while margins remain resilient."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where Yalla’s Question Leads Next
Yalla Group raises one puzzle. Where else is engagement and attention turning into real business power?
Search, video and social apps all compete for your time. That contest creates demand for tools that help big customers run ads, manage data and roll out AI features.
One major platform quietly links all three. It sells cloud capacity, office software and AI models that slot into everyday workflows.
The real interest lies in how that toolkit shapes budgets. When buyers standardise on one provider for ads, cloud and AI, the ripple effects can linger.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 35% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com