


EN
Should Earnings Estimate Upgrades Require Action From Expeditors International Of Washington (EXPD) Investors?
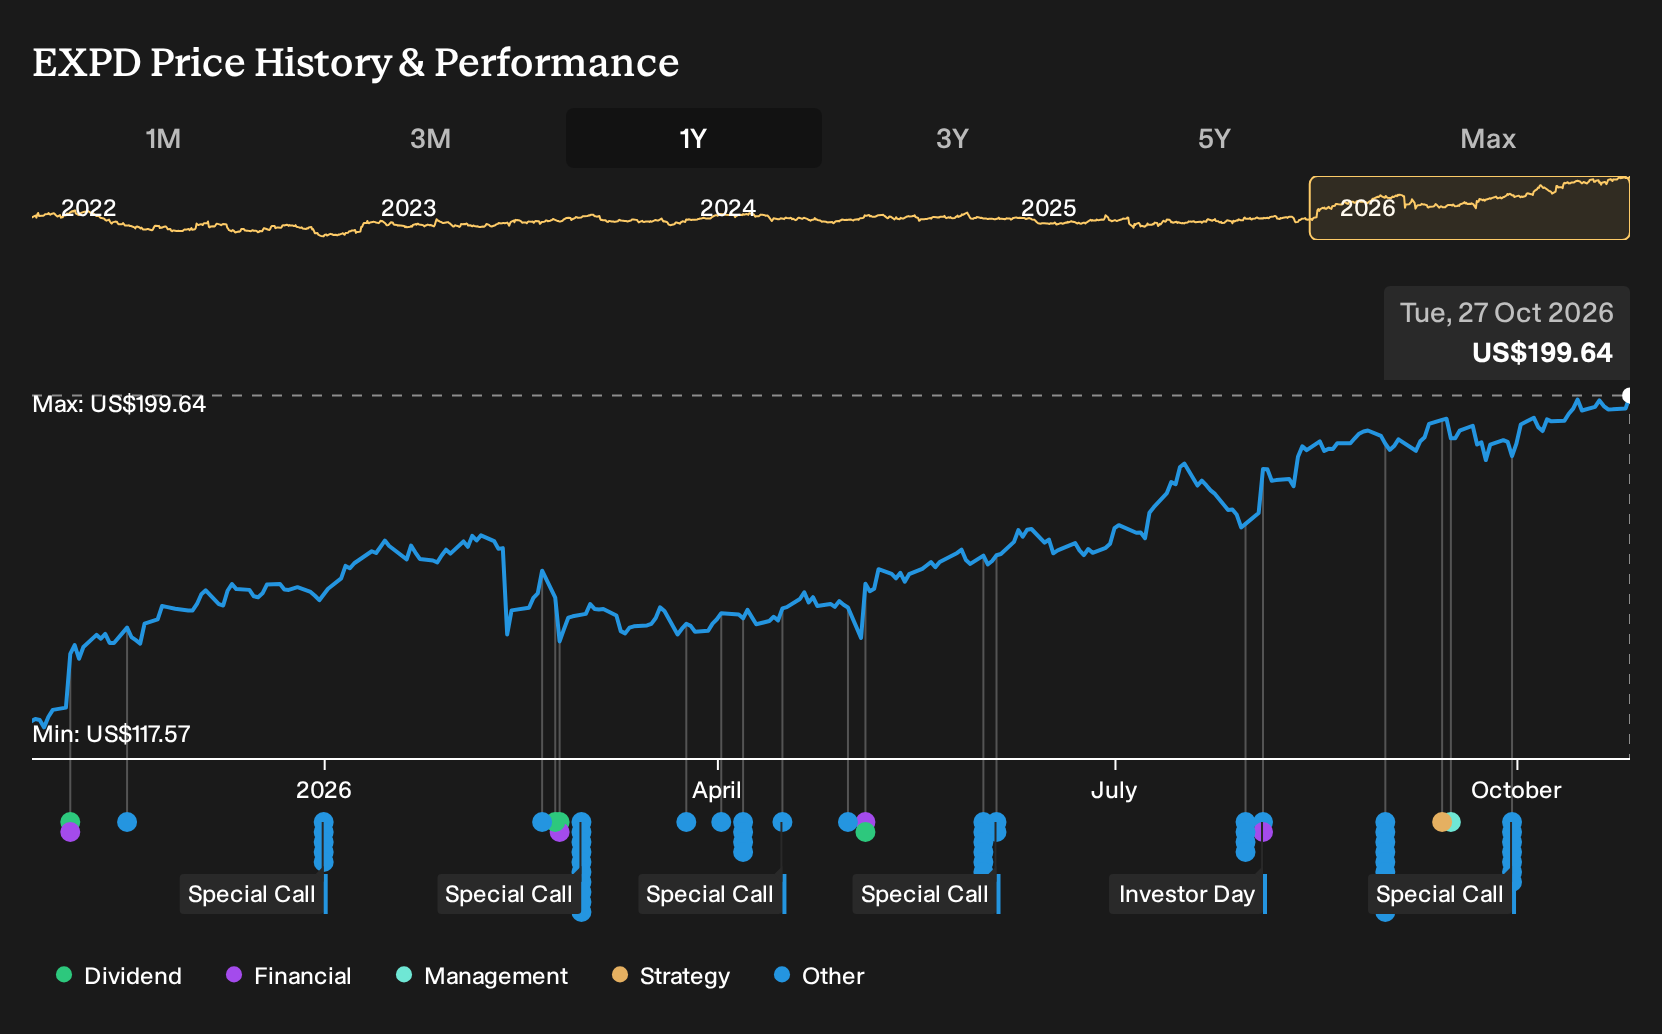
- Expeditors International of Washington has recorded a 34% year to date return while its consensus EPS estimate has shifted 15.4% higher over the past three months, drawing attention in a Transportation sector that has seen a 5.6% decline.
- The contrast between Expeditors International of Washington’s earnings momentum and the weaker Transportation Services industry suggests investors are rewarding the company’s execution in airfreight, customs brokerage and higher value logistics work.
- We will now explore how Expeditors International of Washington’s rising EPS outlook could shape the investment narrative that analysts outlined.
Scan how Expeditors International of Washington’s earnings momentum compares with peers by focusing on handpicked freight and logistics players in the 29 high quality undervalued stocks
Expeditors International of Washington Investment Narrative Recap
To own Expeditors International of Washington, you need to believe the logistics group can keep converting its freight network, customs brokerage and time critical services into steady earnings, even as the broader Transportation Services industry has been weaker. The recent share price strength and firmer EPS outlook point to confidence in that execution rather than a sudden shift in fundamentals.
In the near term, the key swing factor is whether airfreight, customs work and higher value logistics stay healthy enough to support current earnings expectations. The biggest operational risk is that freight volumes or pricing soften at the same time restructuring and automation projects add friction to technology delivery.
Recent commentary around a 14% airfreight volume rise and 32% revenue rise in Q2 2026, together with the YTD outperformance versus the sector, keeps attention on execution quality at Expeditors International of Washington. That kind of operational backdrop helps explain why EPS expectations have moved higher even as broader transportation services have declined 5.6%.
For you as an investor, the interest is in how far that operational strength can carry through while the stock is described as trading at a premium P/E to peers and above some intrinsic value estimates. Any sign that freight activity settles back or that AI and automation efforts fail to deliver productivity gains could test that premium and become the next catalyst, positive or negative, for sentiment around the shares.
Expeditors International of Washington's narrative projects US$13.5b revenue and US$1.1b earnings by 2029. This is based on 3.8% yearly revenue growth and an earnings increase of about US$181.2m from current earnings of US$918.8m.
Uncover why Expeditors International of Washington's fair value indicates a 9% potential downside to its current price, suggesting a premium that may not hold.
Exploring Other Perspectives
One alternate view on Expeditors International of Washington leans heavily on the risk that revenue stays close to US$12.04b with only 1.6% yearly growth and earnings nearer to US$1.0b by 2029. Those lowest analysts price in much slower progress, so the fresh EPS optimism and recent share move could eventually reshape their cautious storyline.
Explore 2 other Expeditors International of Washington fair value estimates, including one that suggests as much as 9% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Expeditors International of Washington research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Expeditors International of Washington. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Expeditors International of Washington's overall financial health at a glance.
Looking for more investment ideas beyond Expeditors International of Washington?
If Expeditors International of Washington has sharpened your focus on quality and execution, you can broaden your watchlist by scanning for other companies that fit clear financial filters using the Simply Wall St Screener.
- For investors who want strong cash generation and valuation support, filter for resilient companies with potential upside using the 29 high quality undervalued stocks.
- If balance sheet strength is your first line of defence, focus on businesses with low leverage and solid fundamentals by running a list of solid balance sheet and fundamentals (24 results).
- When income is the priority, target reliable payers with higher yields by reviewing the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com