


EN
Is Smurfit Westrock (SW) A Bargain As Guidance Cuts Cloud Its Earnings Recovery?
Smurfit Westrock (NYSE:SW) is back in focus after third quarter results came in below analyst forecasts and management cut full year adjusted EBITDA guidance, blaming unprecedented cost inflation and delayed benefits from planned paper price increases.
Recent trading shows that momentum in Smurfit Westrock has cooled, with the 30 day share price return down 8.34% and the 90 day move down 11.85%, even though the year to date share price return is up 7.42% and the three year total shareholder return is 49.19%.
See how Smurfit Westrock's recent guidance cut compares with other packaging and materials stocks by reviewing our curated list of solid balance sheet and fundamentals (24 results) for potential alternatives in the same space.
Smurfit Westrock looks like a solid global packaging platform on the surface. However, the recent guidance cut and share price pullback raise a sharper issue: Are investors now getting that scale at a sensible valuation, or still paying up for it?
Most Popular Narrative: 25% Undervalued
Smurfit Westrock last closed at $42.54, while the most followed narrative framework places fair value closer to $56.72 based on discounted future cash flows using an 8.16% discount rate. That gap sets the stage for a thesis that leans heavily on internal self help and tight paper supply rather than just broad packaging demand.
Systematic winding down of loss-making contracts and refilling North American capacity with more profitable business remains under way, with box operations now reporting small EBITDA profits and far fewer loss-maker plants. This points to further upside for earnings and net margins as this self help work progresses through the P&L.
See why 13 investors see Smurfit Westrock as 25% undervalued.
Result: Fair Value of $56.72 (UNDERVALUED)
Still, the story for Smurfit Westrock can change quickly if freight and energy costs stay elevated, or if buyers resist further containerboard price increases.
Find out about the key risks to this Smurfit Westrock narrative.
Another View: What Smurfit Westrock’s P/E Is Telling You
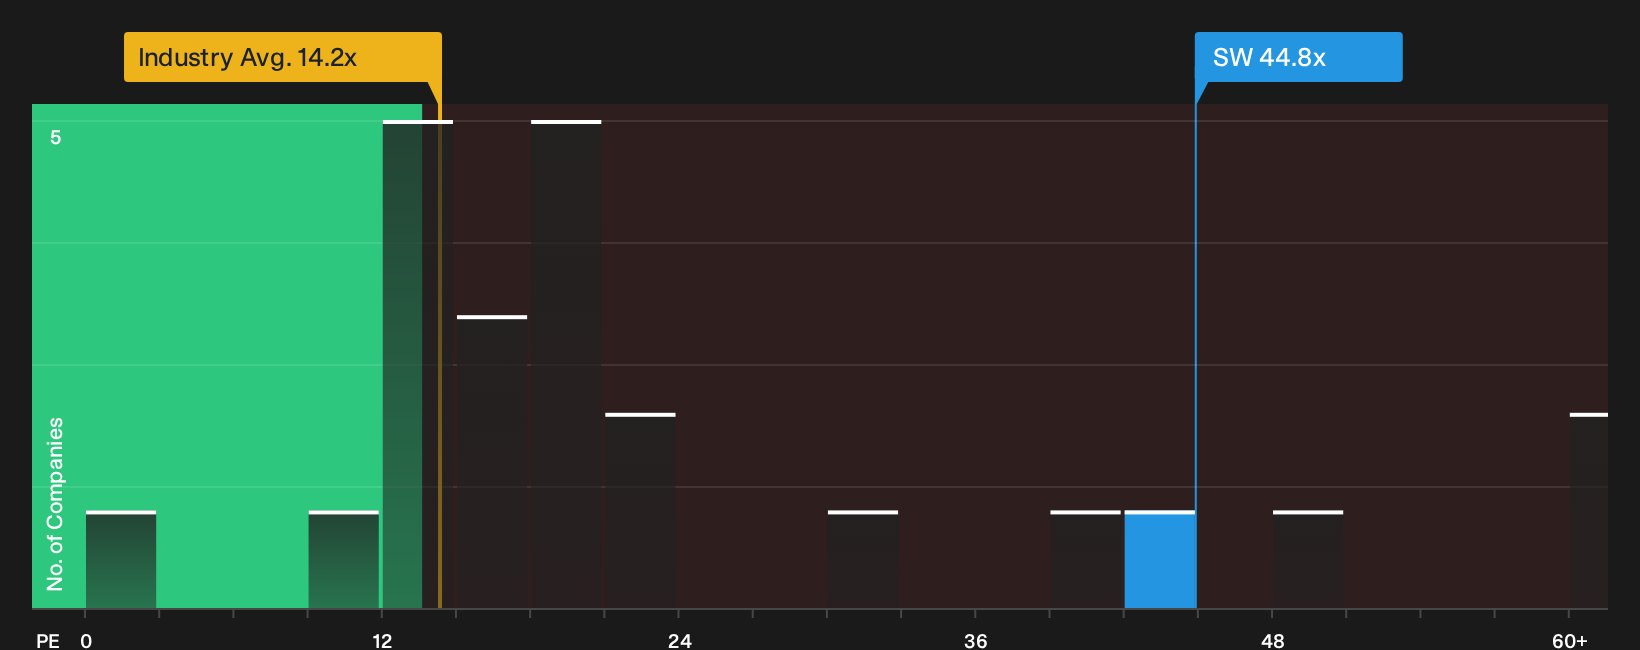
The discounted cash flow work suggests upside for Smurfit Westrock, yet the P/E ratio paints a tougher picture. The stock trades on 44.8x earnings compared with 20.7x for peers and 14.3x for the broader packaging group, while the fair ratio sits closer to 44.3x. That narrow gap between the current multiple and the fair ratio leaves less room for error if execution wobbles or sentiment cools. How comfortable are you paying a premium entry price for a value style thesis?
For a closer look at what this premium earnings multiple could mean in practice, and how the numbers stack up against peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Smurfit Westrock’s story today are exactly why it helps to move quickly, test the numbers yourself, and then decide how comfortable you are with the balance between upside and downside. To weigh those trade offs with a bit more structure, review the 4 key rewards and 3 important warning signs.
Looking for more Smurfit Westrock sized investment ideas?
If you want a broader watchlist and do not want to risk missing other opportunities, use the Simply Wall St screener to scan beyond Smurfit Westrock.
- Target resilient opportunities by filtering for companies with strong balance sheets and steady fundamentals through our curated list of solid balance sheet and fundamentals (24 results).
- Zero in on price tags that look more reasonable relative to fundamentals by working through a focused list of 29 high quality undervalued stocks.
- Prioritise consistent cash returns by reviewing a hand picked set of 5 dividend fortresses that may suit an income focused approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com