


EN
Stepan (SCL) Dividend Hike Keeps Turnaround Story Alive As Undervalued View Holds
Stepan (SCL) extended its dividend track record, with the board declaring a quarterly cash payout of $0.405 per share, up $0.010 and marking the 59th consecutive annual increase.
Recent trading has been supportive, with a 7 day share price return of 3.2% helping extend Stepan’s year to date share price gain to 38.27%. The 1 year total shareholder return of 51.57% contrasts with weaker total shareholder returns over the past 3 and 5 years, hinting that momentum has picked up only relatively recently.
Spot 5 dividend fortresses that pair resilient income streams with share price momentum similar to Stepan’s recent run.After a 38.27% year to date climb and a 51.57% 1 year total return, the key question for Stepan is straightforward: Do the current valuation markers still point to meaningful upside, or has the stock already captured the easier gains?
Most Popular Narrative: 23% Undervalued
Against a last close of $65.21, the most followed narrative for Stepan points to a fair value of $85. The gap between those two prices rests on whether the cost reset and mix shift actually feed through to earnings quality.
Ongoing Project Catalyst actions, including site closures such as Fieldsboro and asset decommissioning in Millsdale and Stalybridge, together with targeted salaried headcount and procurement efficiencies, are expected to support the approximately US$100 million pretax savings plan over two years and could reset Stepan’s cost base in a way that benefits earnings quality and margins.
See why 6 investors see Stepan as 23% undervalued.
Result: Fair Value of $85 (UNDERVALUED)
Still, the Stepan narrative can be knocked off course if high input costs again compress Surfactant profitability, or if Rigid Polyol demand in construction remains muted.
Find out about the key risks to this Stepan narrative.
Another View: What Multiples Say About Stepan
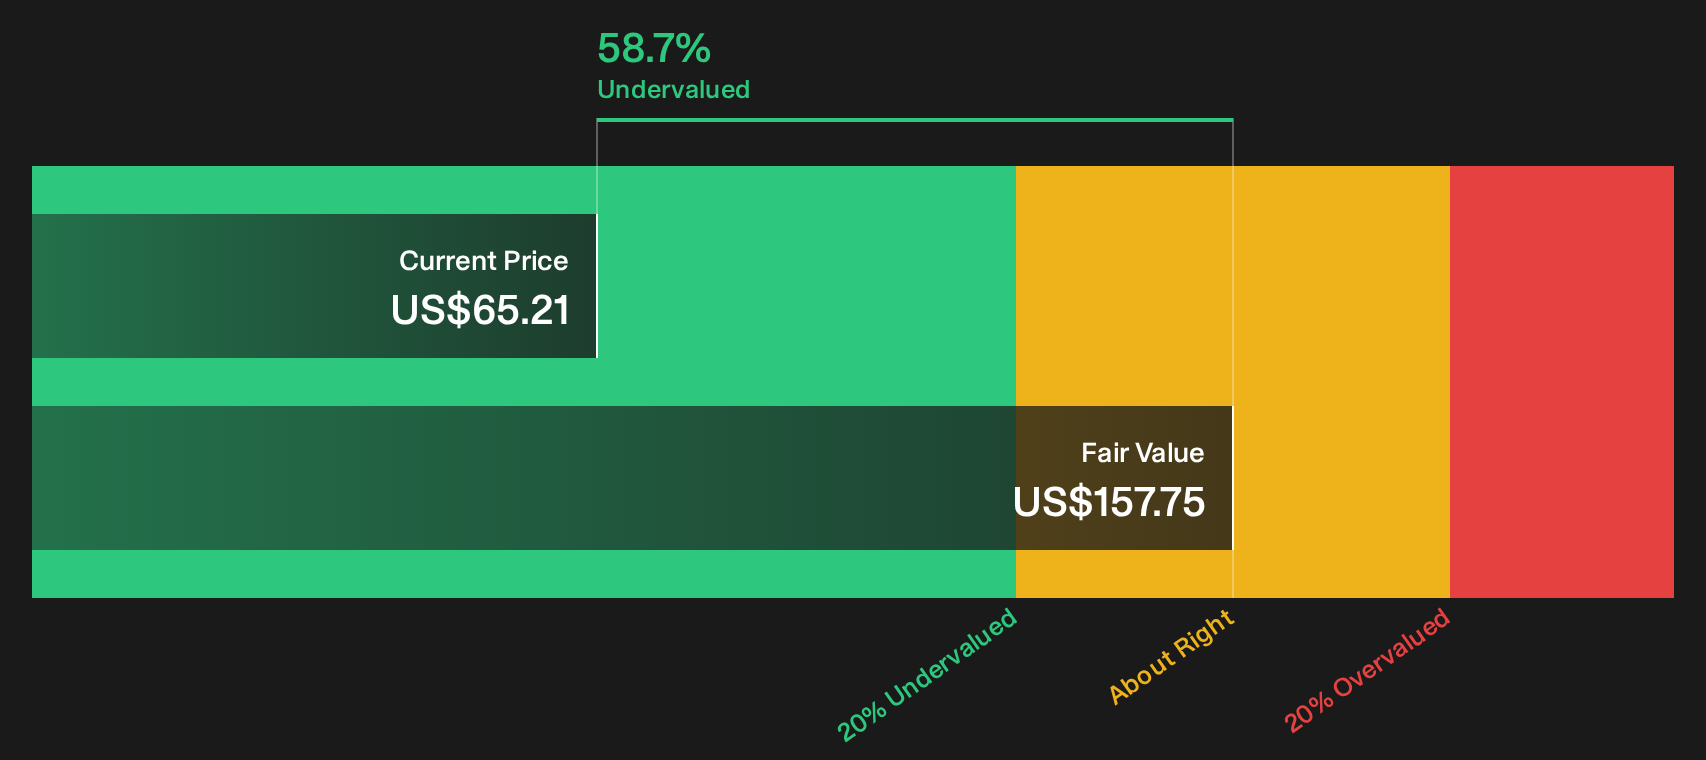
There is a catch. While the SWS DCF work suggests Stepan trades well below an intrinsic value of $157.75 per share, the current P/S of 0.6x already matches its fair ratio of 0.6x and sits below both peer and US Chemicals industry averages of around 1x and 1.1x. That mix of deep DCF upside and more fully valued sales multiple leaves investors weighing whether the bigger risk is overpaying for optimistic cash flow forecasts or underestimating how far sentiment can shift if execution on Pasadena and Project Catalyst disappoints.
Our DCF model is fully transparent, so you can stress test your own assumptions against it, not just accept the output at face value. Then decide which story you trust more, the cash flows or the current sales multiple, when sizing any position in Stepan. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Feeling mixed about Stepan after all of that, with both risks and rewards in play, it makes sense to move quickly and weigh the full picture for yourself. The most useful next step is to review the 2 key rewards and 2 important warning signs.
Looking for more Stepan-like investment ideas?
Stepan’s recent run is only one path. Broaden your watchlist now and give yourself more options before the next wave of opportunities moves without you.
- Target potential mispricings early by scanning a hand picked pool of quality opportunities using the 29 high quality undervalued stocks.
- Prioritise resilience by focusing on companies that pair disciplined balance sheets with solid fundamentals, starting with the list of solid balance sheet and fundamentals (24 results).
- Hunt for tomorrow’s stories today by filtering for fundamentally strong out of favor opportunities in the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com