


EN
Is Sino Biopharmaceutical (SEHK:1177) A Bargain On Its Phase III Trial Progress?
Sino Biopharmaceutical (SEHK:1177) has drawn attention after announcing full patient enrollment in a pivotal Phase III trial for TQC2731, a TSLP-targeting monoclonal antibody for chronic rhinosinusitis with nasal polyps.
Sino Biopharmaceutical’s latest trial update lands after a mixed price run, with the HK$4.855 share price sitting on a year to date share price return down 23.66% and a one year total shareholder return down 29.34%. This comes despite a 67.08% total shareholder return over three years that hints at longer term optimism now rubbing up against more cautious recent sentiment.
Capitalize on Sino Biopharmaceutical's trial momentum by scanning our hand-picked 610 high quality undiscovered gems in healthcare that are quietly building pipelines and clinical catalysts of their own.The recent slide in Sino Biopharmaceutical, despite steady reported revenue and net income growth, raises a simple tension: Are investors reassessing the business itself, or has sentiment just moved faster than the fundamentals?
Preferred P/E of 30.8x: Is it justified?
On valuation, the market currently prices Sino Biopharmaceutical at a P/E of 30.8x, which sits well above both its peers and the sector in Hong Kong. That multiple is being applied to a HK$4.855 share price that has retreated over the past year, so investors are still paying a premium despite weaker recent returns.
The P/E ratio compares the current share price to earnings per share and effectively tells you how much investors are willing to pay for each unit of profit. For a research driven pharmaceutical group with a broad oncology and specialty portfolio, P/E can often reflect expectations around future product launches, clinical milestones and the durability of existing cash flows.
In Sino Biopharmaceutical’s case, the 30.8x P/E sits against a track record where earnings declined by 39.1% per year over the past five years and fell 38.7% over the last year. That creates a clear mismatch between recent profit trends and the rich multiple, even with earnings forecast to grow 15.6% per year, which is faster than the Hong Kong market. The estimated fair P/E of 24.6x from the SWS work suggests a level the market could move toward if sentiment cools.
Set against the Hong Kong Pharmaceuticals industry average P/E of 13.3x and a peer average of 13.8x, Sino Biopharmaceutical trades on more than double those benchmarks. That gap implies investors are currently assigning a much higher value to its future profit stream than to that of comparable stocks, and the fair ratio estimate underlines how stretched the current pricing looks.
Explore the SWS fair ratio for Sino Biopharmaceutical.
Result: Price-to-earnings of 30.8x (OVERVALUED)
Still, Sino Biopharmaceutical faces key risks if clinical results disappoint or if investors start to question paying a premium P/E in light of recent earnings declines.
Find out about the key risks to this Sino Biopharmaceutical narrative.
Another view on Sino Biopharmaceutical’s value
The SWS DCF model paints a very different picture for Sino Biopharmaceutical. At a share price of HK$4.86, the stock is described as trading 70.6% below an estimated future cash flow value of HK$16.54. One model flags overvaluation on earnings, while the other points to a steep discount, so which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
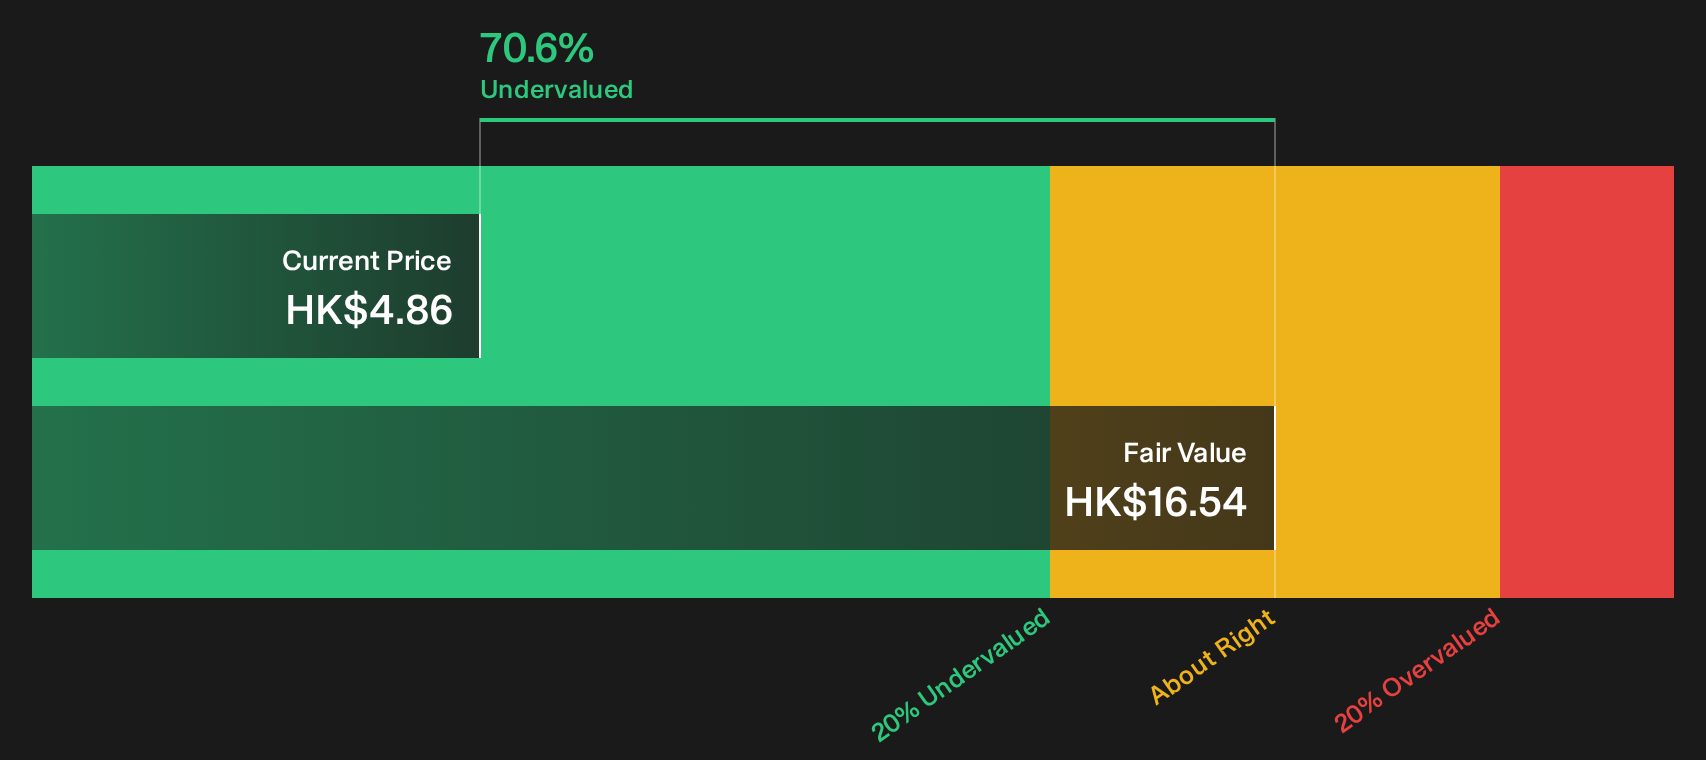
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sino Biopharmaceutical for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split between risks and rewards around Sino Biopharmaceutical feels finely balanced, consider acting quickly and testing the numbers yourself before sentiment shifts. To see both sides clearly, review the 2 key rewards and 1 important warning sign
Looking for more ideas beyond Sino Biopharmaceutical?
Do not stop with Sino Biopharmaceutical. Broaden your watchlist with a few focused stock ideas so you are not relying on a single clinical or valuation outcome.
- Target potential upside in smaller companies that already show financial strength by scanning 124 elite penny stocks with strong financials before the market catches on.
- Aim for a better balance between quality and price by reviewing the 195 high quality undervalued stocks that combine solid fundamentals with more modest expectations baked into their valuations.
- Anchor your portfolio with resilience in mind by assessing a 223 resilient stocks with low risk scores that score well on financial stability and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com