


EN
Palantir Could Crush Q3 Earnings, But 1 Risk Could Spoil the Rally
Palantir (PLTR) will announce its third-quarter earnings on Nov. 2. Demand for its Artificial Intelligence Platform (AIP) continues to grow across commercial and government markets, giving the company a strong base to deliver solid quarterly results again.
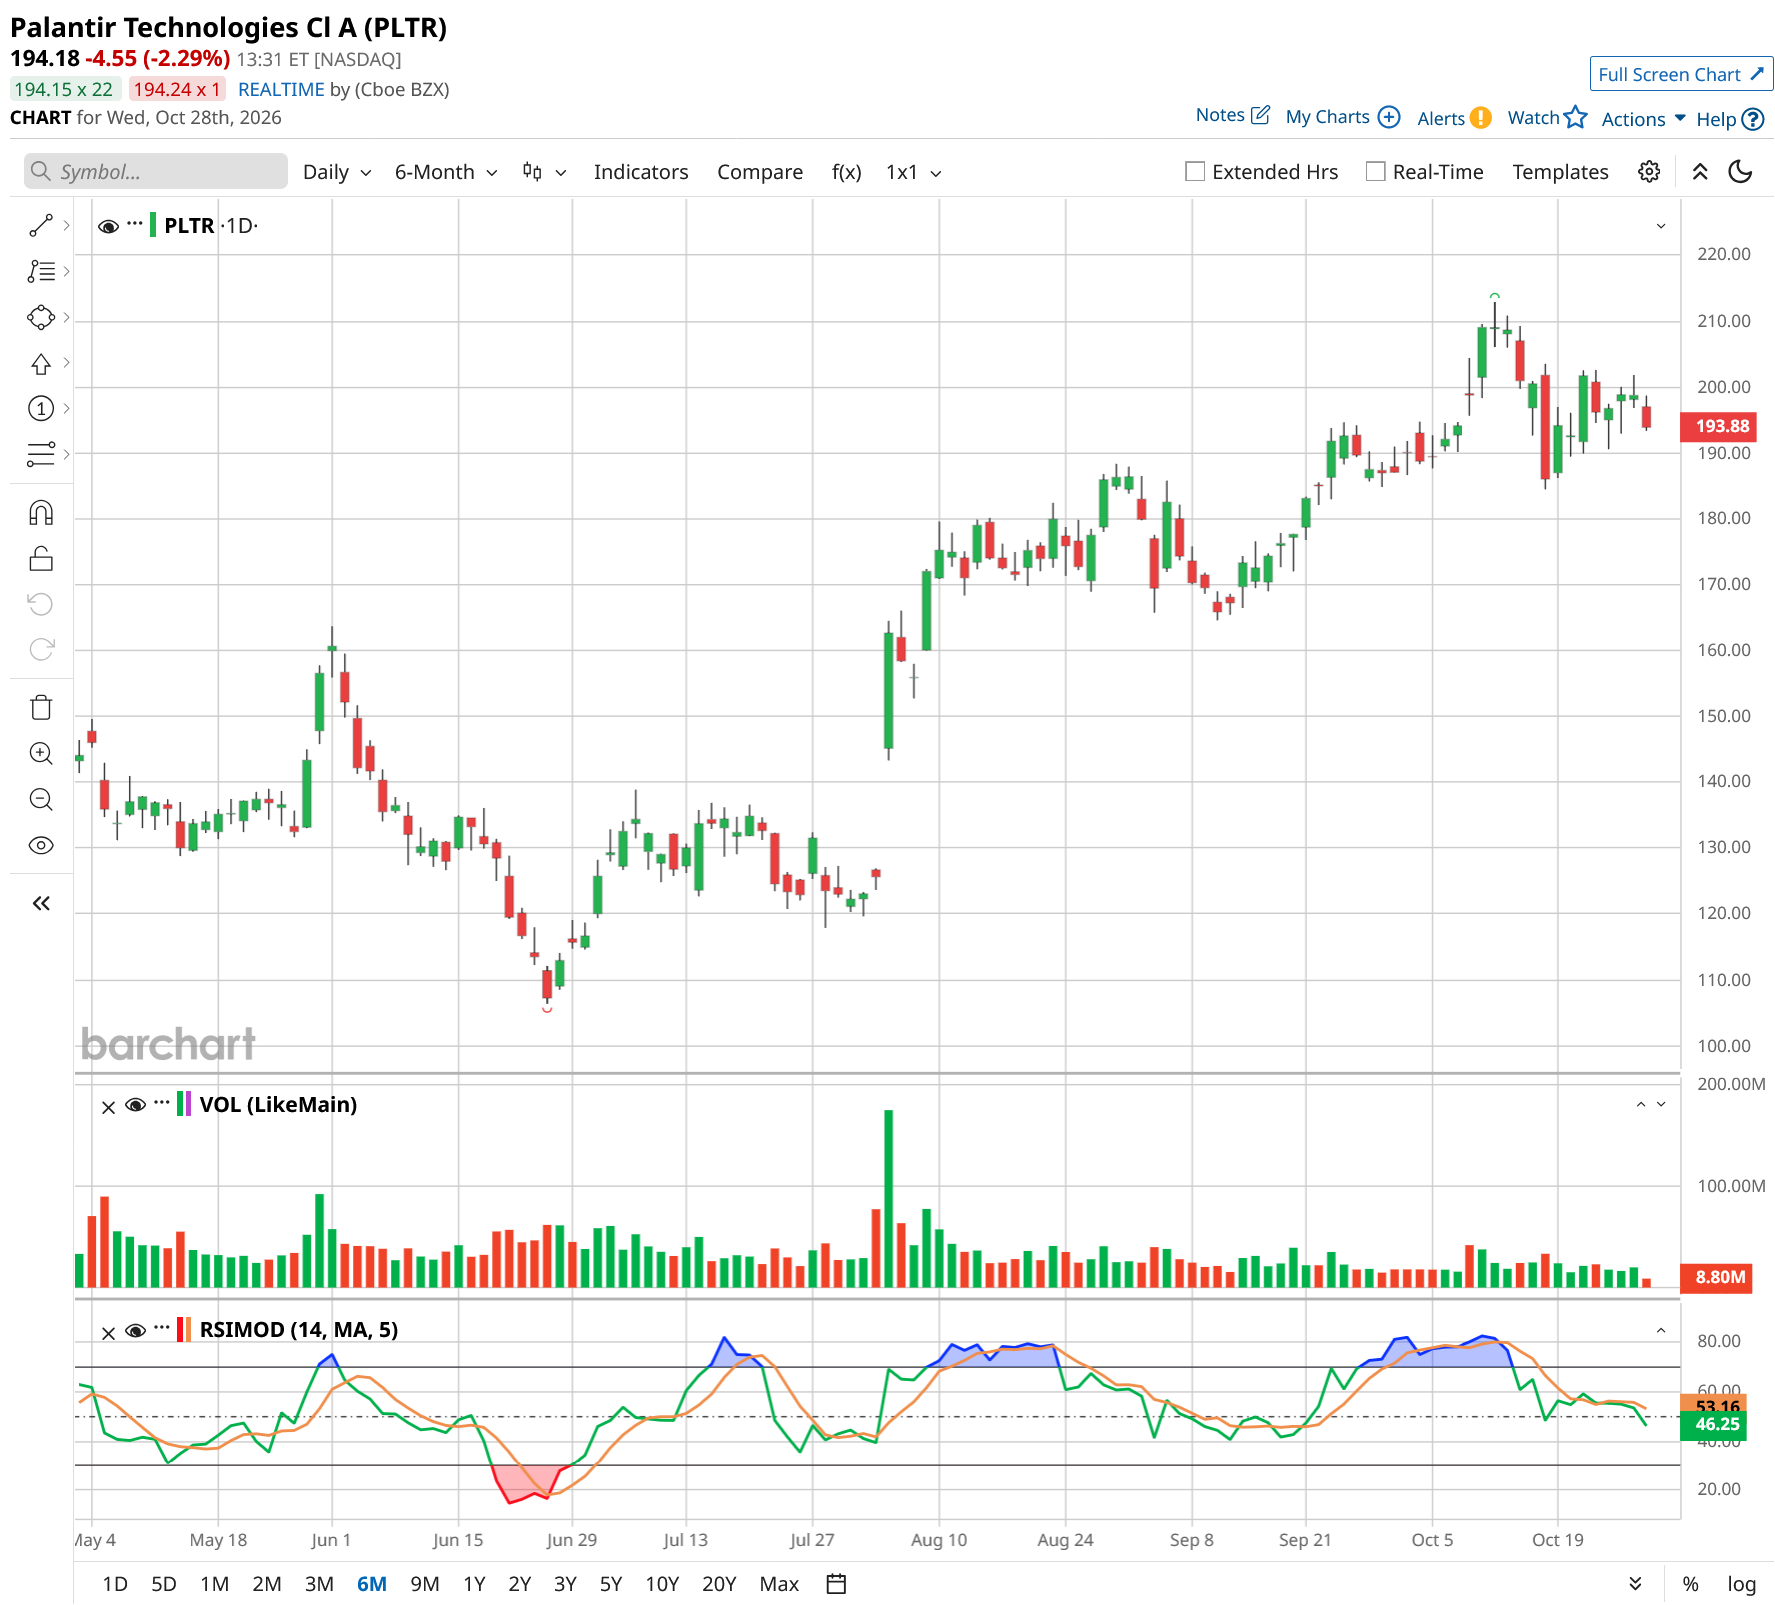
The optimism is already reflected in PLTR stock's price, which has climbed more than 57% over the past three months. Strong revenue growth and healthy profit margins have led to a solid rally, with Palantir's stock hitting a new high earlier this month.
However, even if Palantir delivers solid results and offers encouraging guidance, its high valuation remains a key risk.
Strength in the U.S. Business to Lift Q3 Higher
Palantir is set to deliver another strong quarterly performance, supported by accelerating demand across its U.S. commercial and government businesses. It reported 93% year-over-year (YOY) revenue growth in the second quarter, marking its strongest growth rate to date. Its domestic operations were the primary growth engine, accounting for more than 81% of total revenue and expanding 115% YOY.
The big data company's commercial segment stands out as a key driver of growth trajectory. U.S. commercial revenue surged 149% YoY in Q2, reflecting rising enterprise adoption of its AI solutions. Palantir secured a record $2.1 billion in U.S. commercial total contract value (TCV) bookings, up 153% from the previous year. Over the trailing 12 months, these bookings totaled $5.96 billion, up 117% from the prior 12-month period. This acceleration suggests that customer demand is translating into substantial contractual commitments, supporting revenue visibility over the coming quarters.
Palantir’s remaining deal value in its U.S. commercial business increased 124% YoY, while its U.S. commercial customer base expanded 35% to 653. These trends point to deeper domestic penetration and continued customer acquisition.
Its government business is also contributing meaningfully to its expansion. U.S. government revenue climbed 90% YoY and 18% sequentially in Q2 to $809 million. Execution of existing programs and new contract awards supported growth, highlighting continued demand for AI-enabled platforms across government agencies.
Deal activity remains solid. Palantir closed 220 contracts valued at $1 million or more in the second quarter, including 98 deals worth at least $5 million and 73 worth $10 million or more. The momentum is likely to continue in Q3.
Meanwhile, trailing 12-month revenue from its 20 largest customers rose 67% YoY, reaching an average of $124 million per customer.
For the third quarter, Palantir projects revenue of about $2.16 billion to $2.164 billion, implying about 83% YoY growth. Adjusted operating income is also expected to increase substantially.
Strong revenue and higher operating income will likely boost its bottom line. Wall Street analysts expect Palantir to report earnings of $0.33 per share, up 83.3% YoY.
Overall, accelerating U.S. commercial demand, robust government revenue growth, expanding contract commitments, and rising customer spending provide a solid foundation for the company’s Q3 performance.
Palantir’s High Valuation Remains a Risk
While Palantir is positioned to sustain strong growth in the third quarter and subsequent periods, its high valuation remains a key risk. The recent rally in PLTR stock suggests the market has already priced in the positives.
PLTR trades at about 150 times forward earnings and a price-to-sales (P/S) ratio of 105.6, both substantially higher than peers.
Notably, over the past four quarters, Palantir shares rose after two earnings announcements but fell after the other two, with the average post-earnings price move reaching 12.8%. This pattern suggests significant price swings around earnings releases, regardless of the company’s longer-term growth trajectory. Given its high valuation, even a modest earnings shortfall or a cautious forward outlook could hurt PLTR stock's price.
The Bottom Line: Investors Should Take Caution With PLTR Stock
Palantir’s accelerating U.S. commercial growth, strong government demand, and expanding contract pipeline position it for another robust Q3 performance. However, PLTR’s elevated valuation poses a significant risk, as much of the company’s anticipated growth may already be priced into its shares.
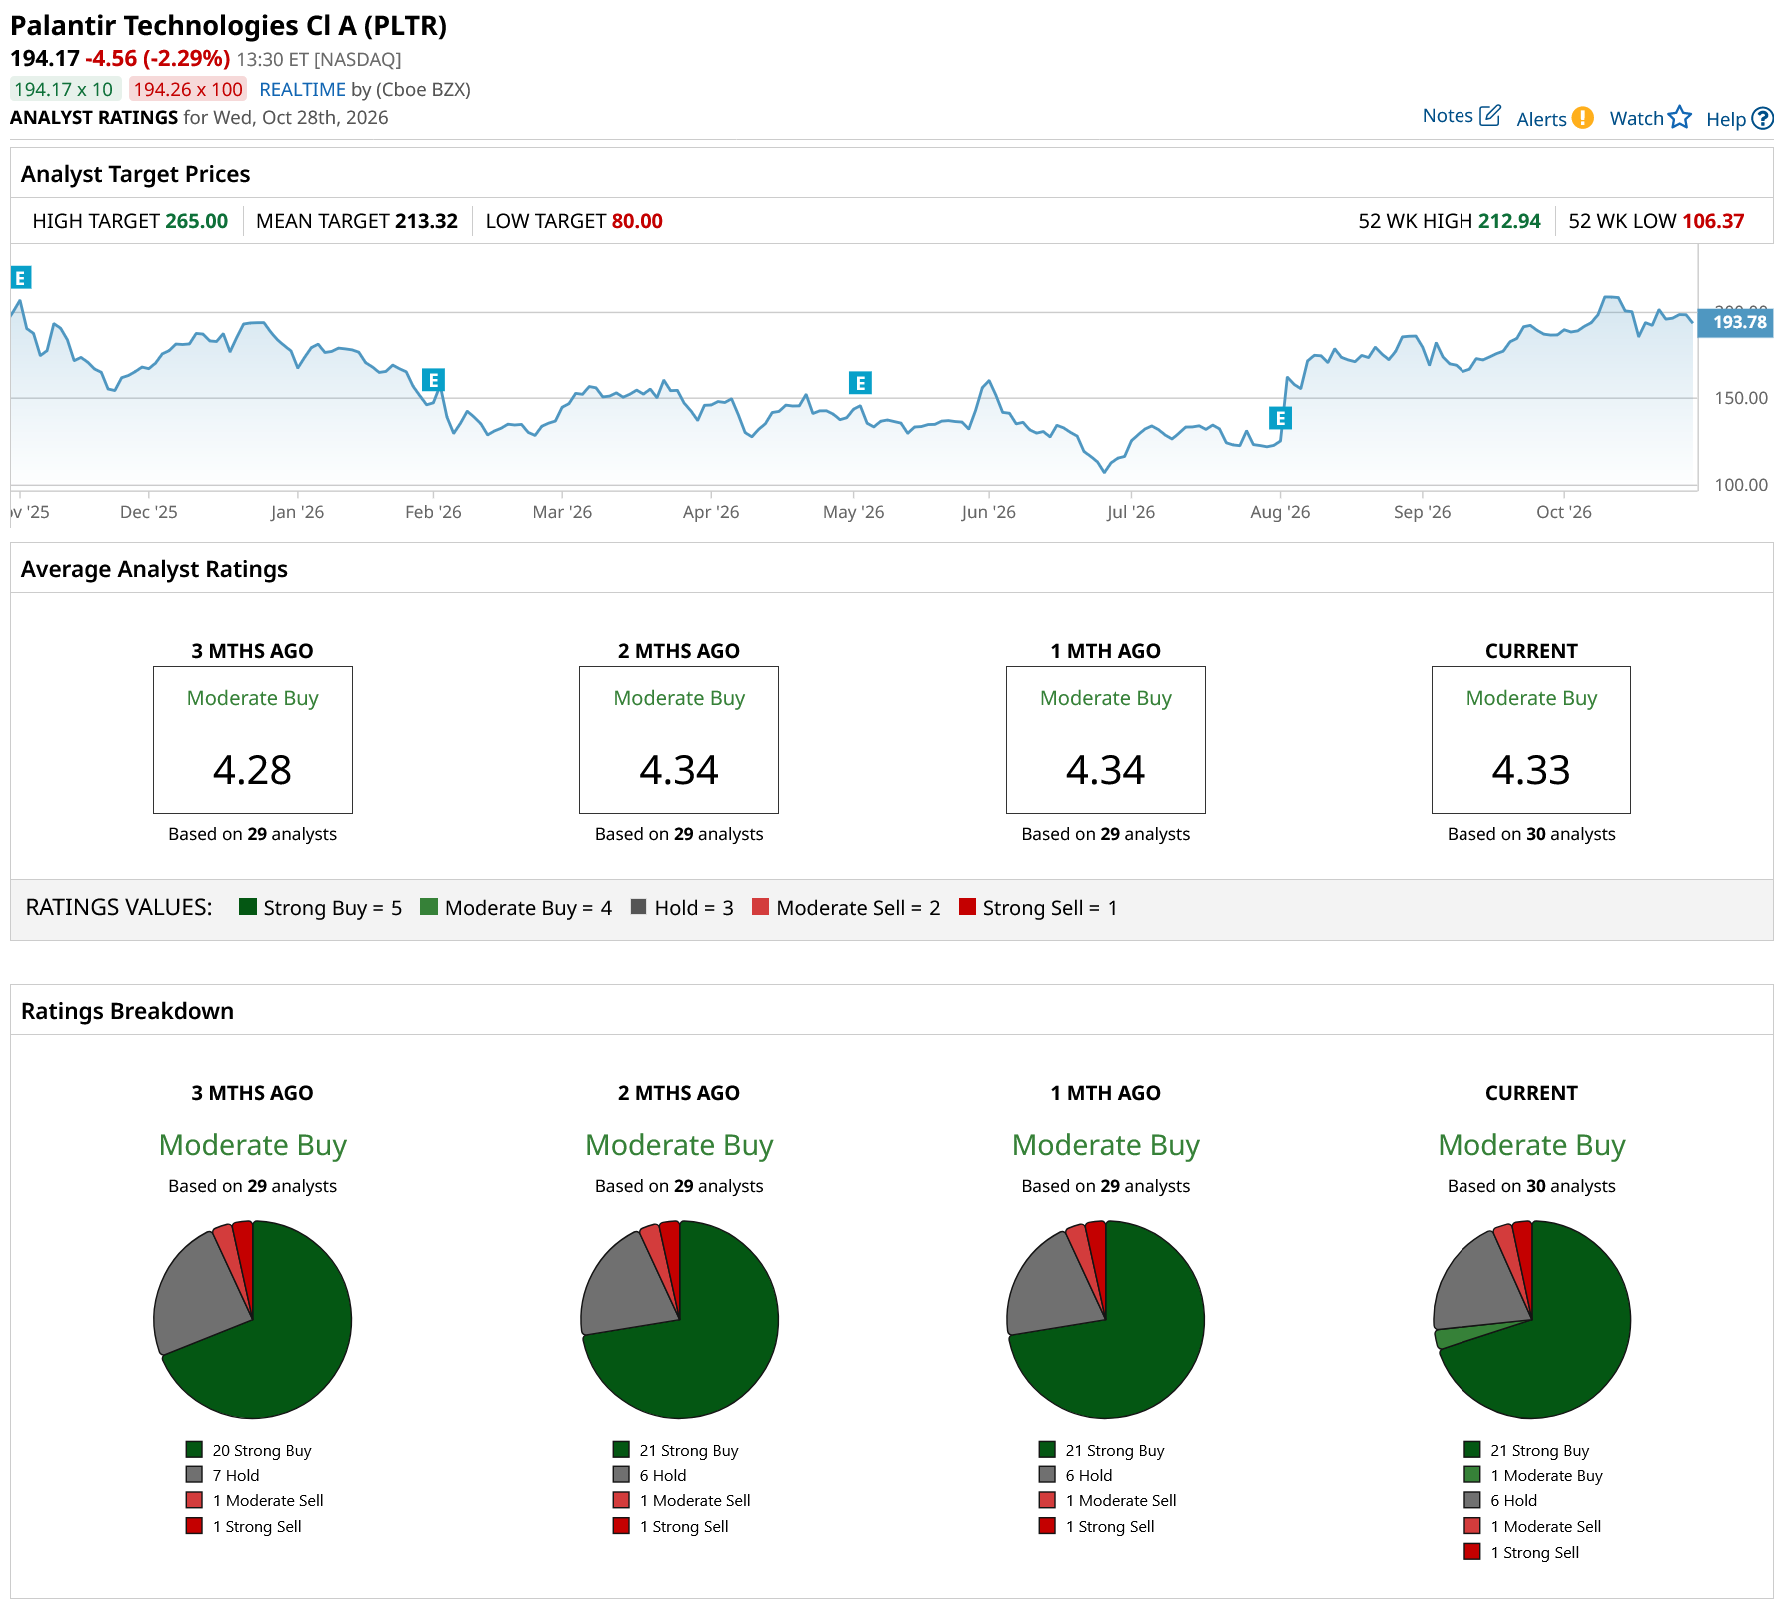
Wall Street analysts maintain a “Moderate Buy” consensus rating on PLTR stock.
On the date of publication, Sneha Nahata did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.