


EN
Ahead of Intel Earnings, Here's What Barchart Data Says Comes Next for INTC Stock
Options traders expect Intel (INTC) shares to push higher after the semiconductor giant reports its fiscal Q3 earnings after the market closes on Oct. 29. Consensus is for Intel to report $0.28 in earnings per share (EPS) for its third financial quarter, which would represent a whopping 154% growth on a year-over-year basis.
Heading into the quarterly print, Intel stock is trading at more than 2x its price at the start of 2026.
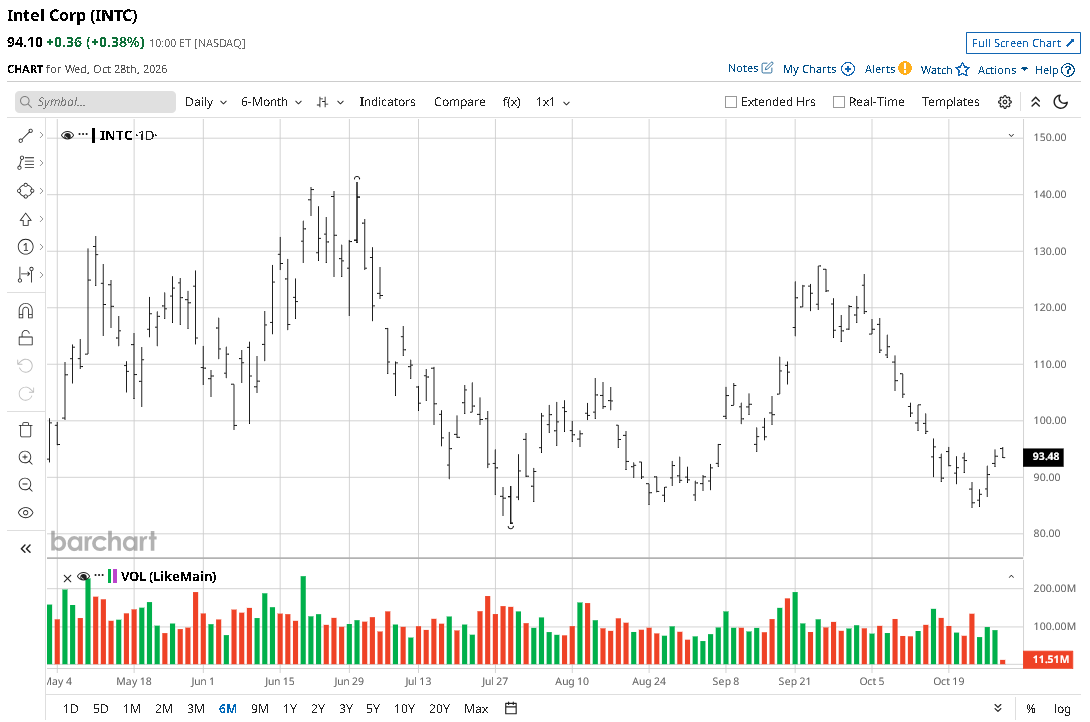
Options Data Signals a Post-Earnings Rally in INTC Stock
INTC shares are currently trading at a forward price-to-earnings (P/E) multiple of about 83x, which makes them expensive even as an artificial intelligence (AI) beneficiary. Still, the options market indicates that the near-term earnings upside is not fully baked into the current price.
The put-to-call ratio on contracts expiring Nov. 6 sits at 0.59x, indicating a bullish skew, with the upper price set at nearly $103 signaling potential for a 9.7% surge through the end of next week.
That said, the technical setup heading into Intel’s earnings event does not agree with the options data; based on 13 distinct technical indicators, Barchart’s opinion on the semiconductor stock is still an “8% SELL."
Needham Maintains Intel Shares at ‘Hold’
Earlier this week, Intel announced a $2.3 billion acquisition of Classiq, a quantum software firm, which Needham analysts dubbed the highest-profile quantum software deal to date in their latest research note. Still, the investment firm reiterated the company at “Hold,” citing caution on data-center CPU market-share losses, weak competitiveness in AI accelerators, and a rich valuation.
Classiq strengthens a different part of Intel’s business. Its software will complement INTC’s silicon spin-qubit hardware and manufacturing capabilities, helping create a complete quantum computing platform, he told clients.
How Analysts Expect Intel to Perform Moving Forward
Other Wall Street analysts are much more bullish on INTC stock heading into 2027, though.
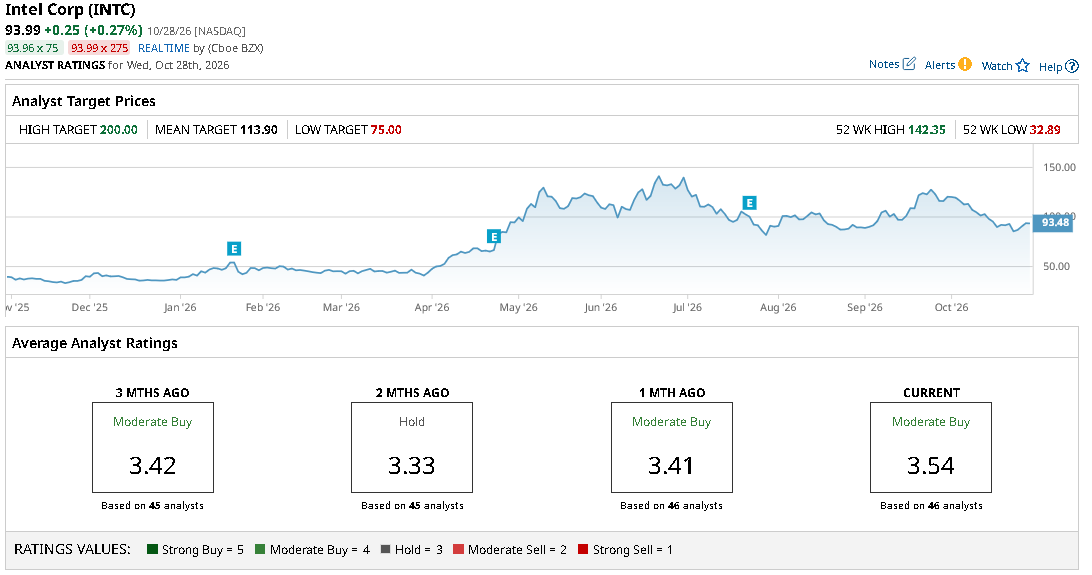
According to Barchart, the consensus rating on Intel remains at “Moderate Buy,” with the mean price target of about $114 indicating potential upside of about 20% from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.