


EN
Does BJ's Wholesale Club Holdings (BJ) Stock Look Fully Priced On Earnings?
BJ's Wholesale Club Holdings has delivered a solid run for shareholders in recent years, which naturally puts a spotlight on whether the current price around US$105 reflects what its earnings can support. With warehouse club peers expanding footprints and digital channels, the question now is whether BJ's Wholesale Club stock is pricing in the right earnings power.
- Over the past 5 years, BJ's Wholesale Club has returned 75.4%, which makes it important to check if that share price journey lines up with the earnings that underpin it.
- Recent coverage around new warehouse openings and digital investment at a key competitor highlights how store growth and online sales can affect membership income, margin mix, and ultimately the earnings base investors may be paying for at BJ's Wholesale Club.
- There is a second opinion on BJ's Wholesale Club Holdings worth weighing. See what analysts think BJ's Wholesale Club Holdings's shares could be worth.
The issue now is whether the earnings that BJ's Wholesale Club generates today, and what investors reasonably expect from them, are enough to justify where the stock currently trades.
If you want a wider lens on warehouse and retail earnings stories like BJ's Wholesale Club Holdings, compare it with companies in the 29 high quality undervalued stocks
Does BJ's Wholesale Club Holdings Look Fairly Valued on Earnings?
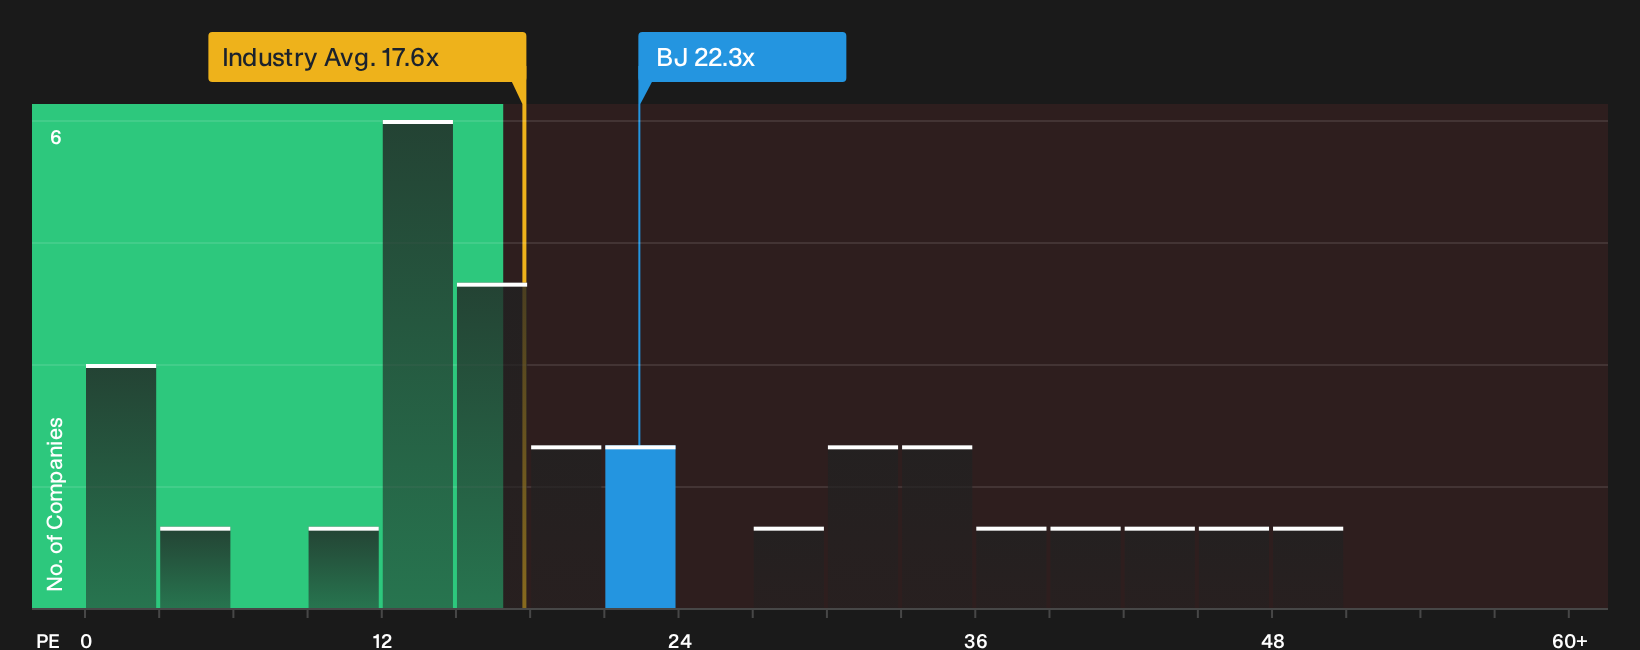
The P/E ratio suits BJ's Wholesale Club Holdings because you are ultimately paying for a stream of earnings from a mature warehouse retailer. BJ's trades on a P/E of about 22.3x, compared with a Consumer Retailing sector average near 17.6x and a peer group around 19.2x. This points to investors accepting a higher price per dollar of earnings than many warehouse and retail competitors.
Because a fair P/E level that factors in BJ's Wholesale Club Holdings specific margins, growth profile and risk sits close to the current ratio, the share price does not screen as either clearly cheap or clearly expensive on this metric alone. Despite attention on new warehouses and digital growth at a large rival lifting the whole warehouse club story, this P/E still implies that BJ's is valued roughly in line with what a tailored model suggests its earnings stream could justify. Explore the numbers behind BJ's Wholesale Club Holdings's P/E valuation.
The BJ's Wholesale Club Holdings Narrative: What Would Justify Today's Price?
Narratives on BJ's Wholesale Club Holdings' Community page pick up where the P/E puzzle leaves off by spelling out which specific paths for earnings, margins and growth would need to play out for the stock to be worth materially more or materially less than today. Each narrative ties its number to a clear view of how BJ's Wholesale Club Holdings' growth profile, profitability and risk mix could evolve, giving you something concrete to revisit as new information comes through.
Community writers looking at BJ's Wholesale Club are largely aligned on the earnings story, although one side thinks the recent execution justifies a bit more optimism than the other.
Bull case: roughly fairly valued
"The 2024 club class comping double digits extends the delivery chain from what Q1 established, 22 of 23 clubs opened from 2022 to 2024 comping above the chain average..."
Discover why this Narrative puts BJ's Wholesale Club Holdings at roughly fairly valued.
Bear case: 22% overvalued
"Although fuel volumes and profitability are currently ahead of plan and helping fund investments, reliance on fuel to subsidize merchandise pricing raises the risk that any normalization would remove a key earnings cushion..."
Explore why this Narrative puts BJ's Wholesale Club Holdings at 22% overvalued.
One more angle on BJ's Wholesale Club Holdings that could change the story
Price tags and P/E ratios only tell part of what you are signing up for with BJ's Wholesale Club Holdings, and recent research flags specific business risks that are worth weighing before you make your next move. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com