


EN
Dividend Payout May Change The Bull Case For Hercules Capital (HTGC)
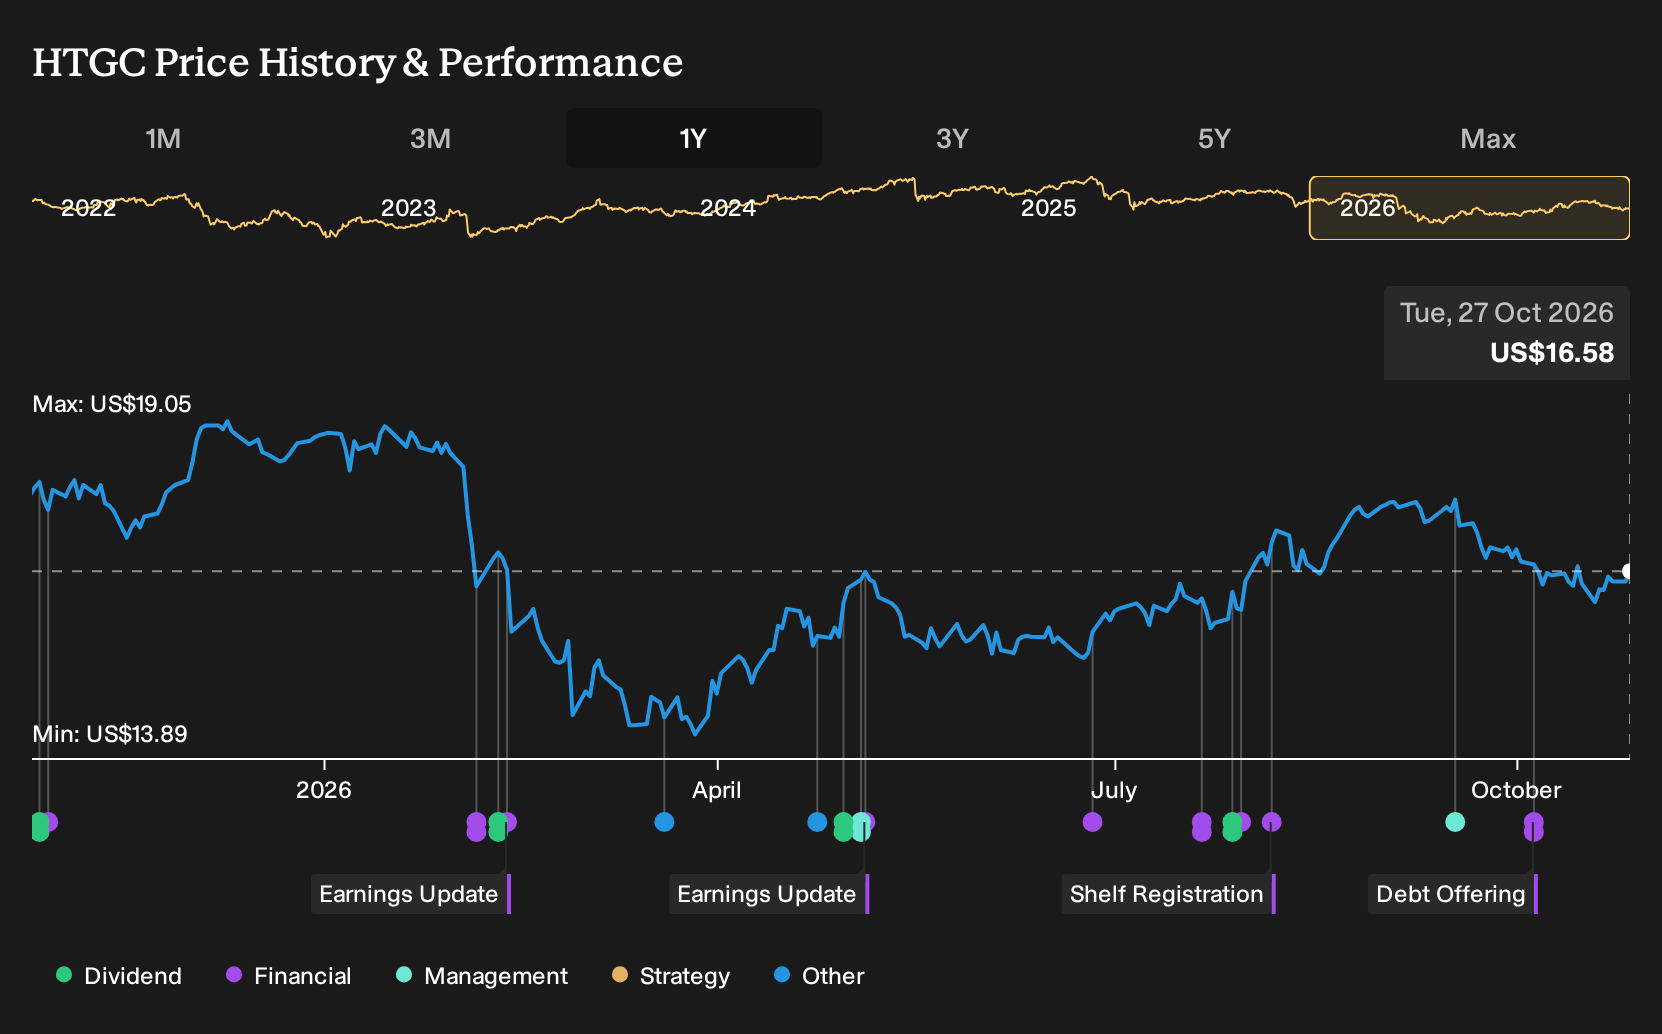
- Hercules Capital announced that its board approved a third quarter 2026 total cash distribution of $0.47 per share, combining a $0.40 base dividend with a $0.07 supplemental payment for shareholders of record on November 10, 2026, paid on November 17, 2026.
- This mix of regular and supplemental dividends indicates that Hercules Capital is aligning its payout with reported taxable income while maintaining flexibility through its variable distribution policy.
- We will now look at how Hercules Capital's investment narrative is affected by the new $0.47 per share total cash distribution.
Scan how Hercules Capital's fresh $0.47 payout compares with other income-focused stocks by checking out the 5 dividend fortresses in today's market.
Hercules Capital Investment Narrative Recap
To own Hercules Capital, you need to be comfortable with a lender that leans hard into venture backed technology and life sciences, where record first half 2026 originations of US$2.74b and fundings of US$1.35b are a key earnings driver. The immediate swing factor is whether this elevated activity and use of nonbank growth debt holds up in the near term.
The biggest near term risk sits on the other side of that same exposure. A reset in software, AI or biotech valuations could bump nonaccruals higher and pressure net asset value. That would matter far more for the thesis than this quarter's distribution tweak.
The most relevant update here is the third quarter 2026 total cash distribution of US$0.47 per share, split into a US$0.40 regular dividend and US$0.07 supplemental payout. Management says the variable policy targets 90% to 100% of taxable income over the year. This mix provides a rough read on current earnings power.
For catalysts, the key question is whether Hercules Capital can keep covering a high distribution level while competition in venture lending heats up and leverage remains elevated. If funding conditions tighten or portfolio repayments slow, the flexibility in that supplemental layer could become a pressure point rather than a boost for income focused holders.
Hercules Capital Analyst Expectations Behind The Dividend
Analysts are effectively anchoring Hercules Capital's current income appeal to a forecast revenue base of US$700.2 million and earnings of US$399.0 million by 2029. That outlook assumes yearly revenue expansion of 7.3%, with earnings moving from US$380.3 million today to US$399.0 million over the same horizon, an increase of about US$18.7 million in absolute terms.
Discover how Hercules Capital's fair value signals an 18% potential upside to its current price, which could close sooner than income investors expect.
Exploring Other Perspectives
You might read the new US$0.47 Hercules Capital payout as proof that dividend coverage still looks healthy, yet the most optimistic analysts focus on adviser fee potential instead. Their pre news view was based on revenue of about US$728.3 million and earnings of US$433.2 million by 2029, so this distribution could still reshape those assumptions.
Explore 3 other Hercules Capital fair value estimates, including one that suggests as much as 54% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own analysis.
- A great starting point for your Hercules Capital research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Hercules Capital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hercules Capital's overall financial health at a glance.
Looking For More Hercules Capital Style Ideas?
If this Hercules Capital dividend update has sharpened your focus on income and quality, use that same framework to scan the wider market with the Simply Wall St Screener.
- For investors who want income without stretching their risk tolerance, consider a shortlist of resilient companies through the 30 resilient stocks with low risk scores that may better align with a steadier approach.
- If value is your main filter, run a quick pass across the market using the 29 high quality undervalued stocks and see which businesses currently combine compressed P/E levels with solid fundamentals.
- Those who care most about balance sheet strength can anchor their search around conservatively financed companies by starting with the list of solid balance sheet and fundamentals (24 results) and then drilling into the details that matter to you.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com