


EN
Adecoagro (AGRO) Approves Its Second Dividend Installment, Is The Stock Still Below Fair Value?
Adecoagro (NYSE:AGRO) is back in focus after its Board of Directors approved the second installment of a previously announced two-part cash dividend, following the first payment made in May 2026.
Adecoagro’s share price has slipped around 6% over the past month but remains ahead for 2026, with a year-to-date share price return of 26.42%. The 1-year total shareholder return of 20.86% points to momentum that income-focused investors often watch closely around dividend events.
Scan other income-focused opportunities responding to dividend news with our hand-picked 5 dividend fortresses alongside Adecoagro.
Adecoagro has climbed strongly in 2026, yet just slipped on the eve of this second dividend installment. After that run and pullback, does the current valuation still leave the balance of risk and reward leaning toward buyers?
Most Popular Narrative: 46% Undervalued
Adecoagro’s most followed valuation story points to a fair value of $18.28 per share, compared with a last close of $9.81, which is a wide gap that income investors watching this latest dividend installment will likely notice.
AGRO’s sugar mills are uniquely designed with high optionality, allowing management to pivot processing dynamically between sugar and ethanol based on real-time market profitability. In the first quarter of 2026, as global sugar prices softened, AGRO seamlessly diverted 96% of its record 2.2 million-ton cane crush into ethanol, capitalizing on Brazil's highly inelastic domestic biofuel demand. This structural flexibility creates a hard floor under their margins during commodity downturns and provides maximum operational leverage during upswings.
See why 6 investors see Adecoagro as 46% undervalued.
Result: Fair Value of $18.28 (UNDERVALUED)
Still, this Adecoagro narrative can unravel if expected climate patterns fail to materialize or if integration risks around Profertil disrupt cash generation.
Find out about the key risks to this Adecoagro narrative.
Another View: Multiples Paint a Different Picture
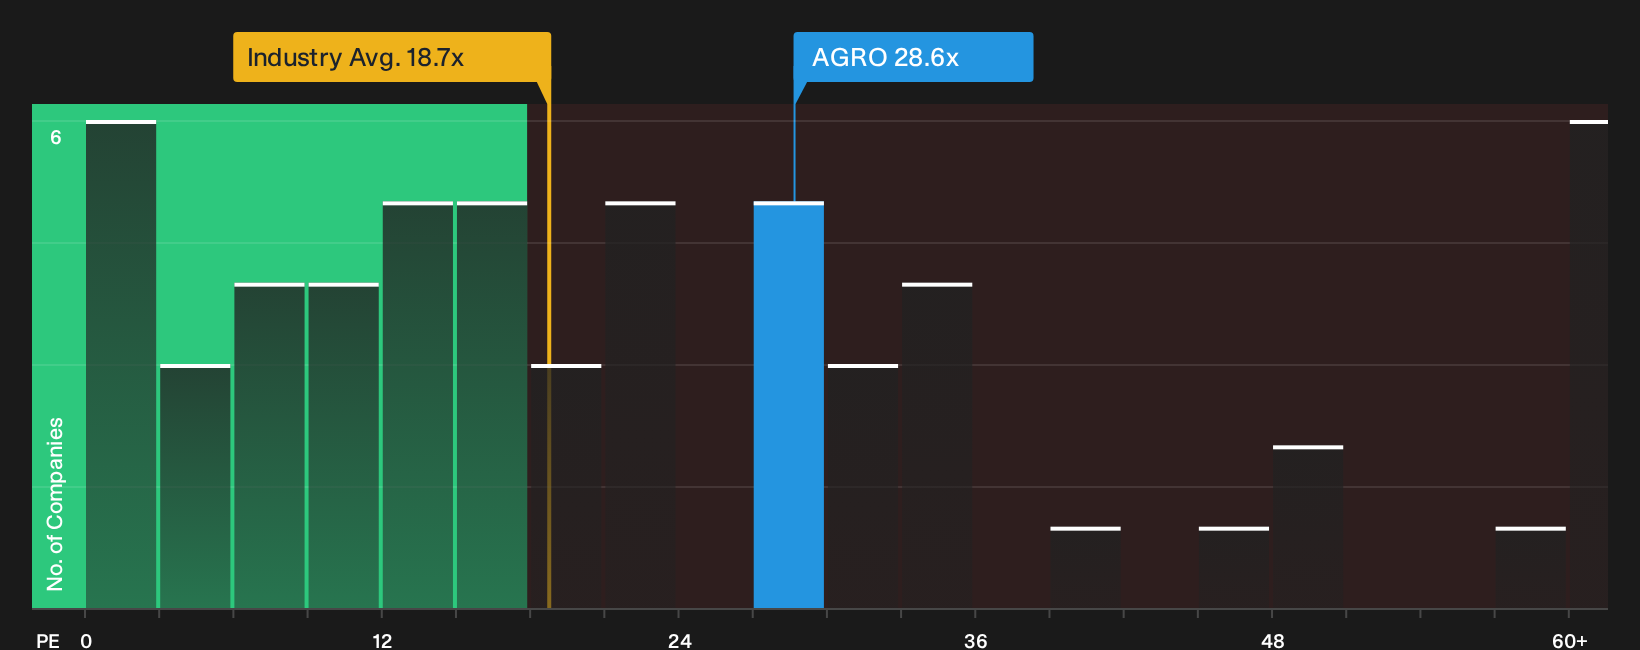
On simple earnings multiples, Adecoagro appears much less cheap than that $18.28 fair value suggests. The stock trades on a P/E of 28.6x, compared with 18.6x for the US Food industry and a fair ratio of 21.2x. That is a wide premium. Is it compensation for future growth, or a valuation risk if expectations cool?
To see how this earnings multiple could evolve as the story develops, investors can review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed signals around Adecoagro leave you on the fence, move quickly from headline impressions to hard evidence and shape your own stance using the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Adecoagro?
Do not stop with Adecoagro. Broaden your opportunity set using targeted stock lists that filter for quality, income, and resilience so you are not relying on a single story.
- Chase reliable income potential by scanning a curated pool of high-yield plays through the 5 dividend fortresses.
- Zero in on quality at a discount by using the 29 high quality undervalued stocks to focus on financially strong companies priced below their estimated worth.
- Protect your capital first by filtering for sturdier balance sheets and fundamentals across the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com