


EN
Is Curtiss Wright (CW) A Bargain As TerraPower Progress And Earnings Optimism Build?
Curtiss-Wright (CW) has landed in focus after completing installation of its Stage 1 Training Simulator at TerraPower’s Natrium project in Wyoming, while investors also eye the upcoming third quarter earnings report.
Against that backdrop, Curtiss-Wright’s share price has softened in recent months, with a 30-day share price return of down 11.63% and a 90-day share price return of down 29.80%. At the same time, the 3-year total shareholder return of 141.57% and 5-year total shareholder return of 277.49% point to a much stronger longer-term record. As a result, some investors may view the current pullback and upcoming earnings report as a test of whether earlier enthusiasm is fading or simply pausing after a strong multi-year run.
Scan other nuclear and power-infrastructure players showing similar momentum to Curtiss-Wright’s TerraPower work and earnings setup by starting with the 16 nuclear energy infrastructure stocks.
Bulls point to Curtiss-Wright’s TerraPower role and earnings momentum, while bears focus on the sharp pullback. Which side does the current valuation evidence lean toward as you weigh the next move?
Most Popular Narrative: 36% Undervalued
Curtiss-Wright last closed at $476.94, while the most followed narrative puts fair value at $743.38. The recent share price slide therefore sits against a model that still treats the stock as materially underpriced based on its long-term cash flow potential.
Backlog and order visibility remain central to the thesis, with total orders up 12% year to date against 9% sales growth, a book to bill above 1.2x, and backlog at US$4.3b. Taken together with raised 2026 sales, margin, and EPS guidance, these factors can support the idea that current pricing undervalues the potential operating leverage into revenue and net margin over the next few years.
See why 17 investors see Curtiss-Wright as 36% undervalued.
Result: Fair Value of $743.38 (UNDERVALUED)
Still, the narrative could wobble if large defense or nuclear contracts are delayed, or if leadership changes at Curtiss-Wright unsettle confidence in execution.
Find out about the key risks to this Curtiss-Wright narrative.
Another View: Curtiss-Wright Through The P/E Lens
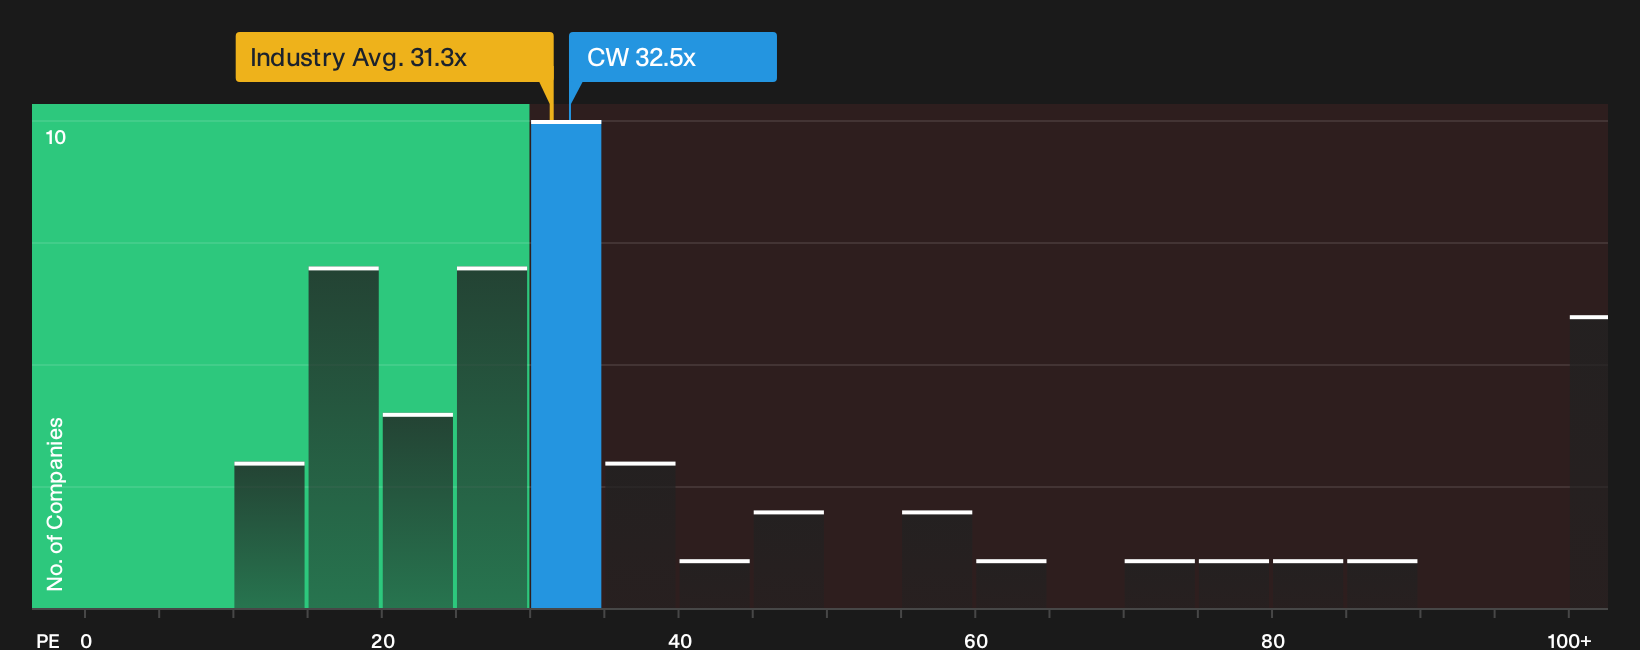
There is a twist when Curtiss-Wright is viewed through its P/E ratio. The shares trade at 32.5x earnings, above the US Aerospace & Defense industry on 31.3x and above a fair ratio of 23.8x. That gap points to valuation risk if sentiment or growth assumptions cool.
For investors who prefer to ground Curtiss-Wright in simple earnings multiples rather than detailed cash flow models, the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment in this Curtiss-Wright story feels split, that is the signal to move quickly. Pull up the underlying data and pressure test the bullish and cautious angles for yourself with the 3 key rewards.
Looking for more investment ideas beyond Curtiss-Wright?
If Curtiss-Wright has sharpened your focus on quality and timing, do not stop here. Use targeted screeners to spot other opportunities before they move.
- Target stability and income potential by reviewing companies in the 5 dividend fortresses.
- Zero in on quality at a discount with the 29 high quality undervalued stocks.
- Prioritize resilience by scanning the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com