


EN
How Investors May Respond To Jacobs Solutions (J) Major Wastewater Contract
- Jacobs Solutions was selected by the San Francisco Public Utilities Commission as the progressive design build contractor, in joint venture with PCL Construction, for the Southeast Treatment Plant Nutrient Reduction Project, a SFPUC estimated US$1b wastewater upgrade that targets lower nitrogen discharges and supports San Francisco Bay protection.
- The contract ties Jacobs Solutions to a long duration environmental infrastructure project that combines advanced treatment design, large scale construction work, and SFPUC linked commitments to local jobs, workforce training, and community programs.
- We will look at how Jacobs Solutions' long term investment narrative is influenced by this US$1b nutrient reduction contract award.
Scan beyond Jacobs Solutions and this SFPUC project to find other environmental infrastructure contractors positioned for long term wastewater, energy and grid upgrade work with the curated 42 power grid technology and infrastructure stocks
Jacobs Solutions Investment Narrative Recap
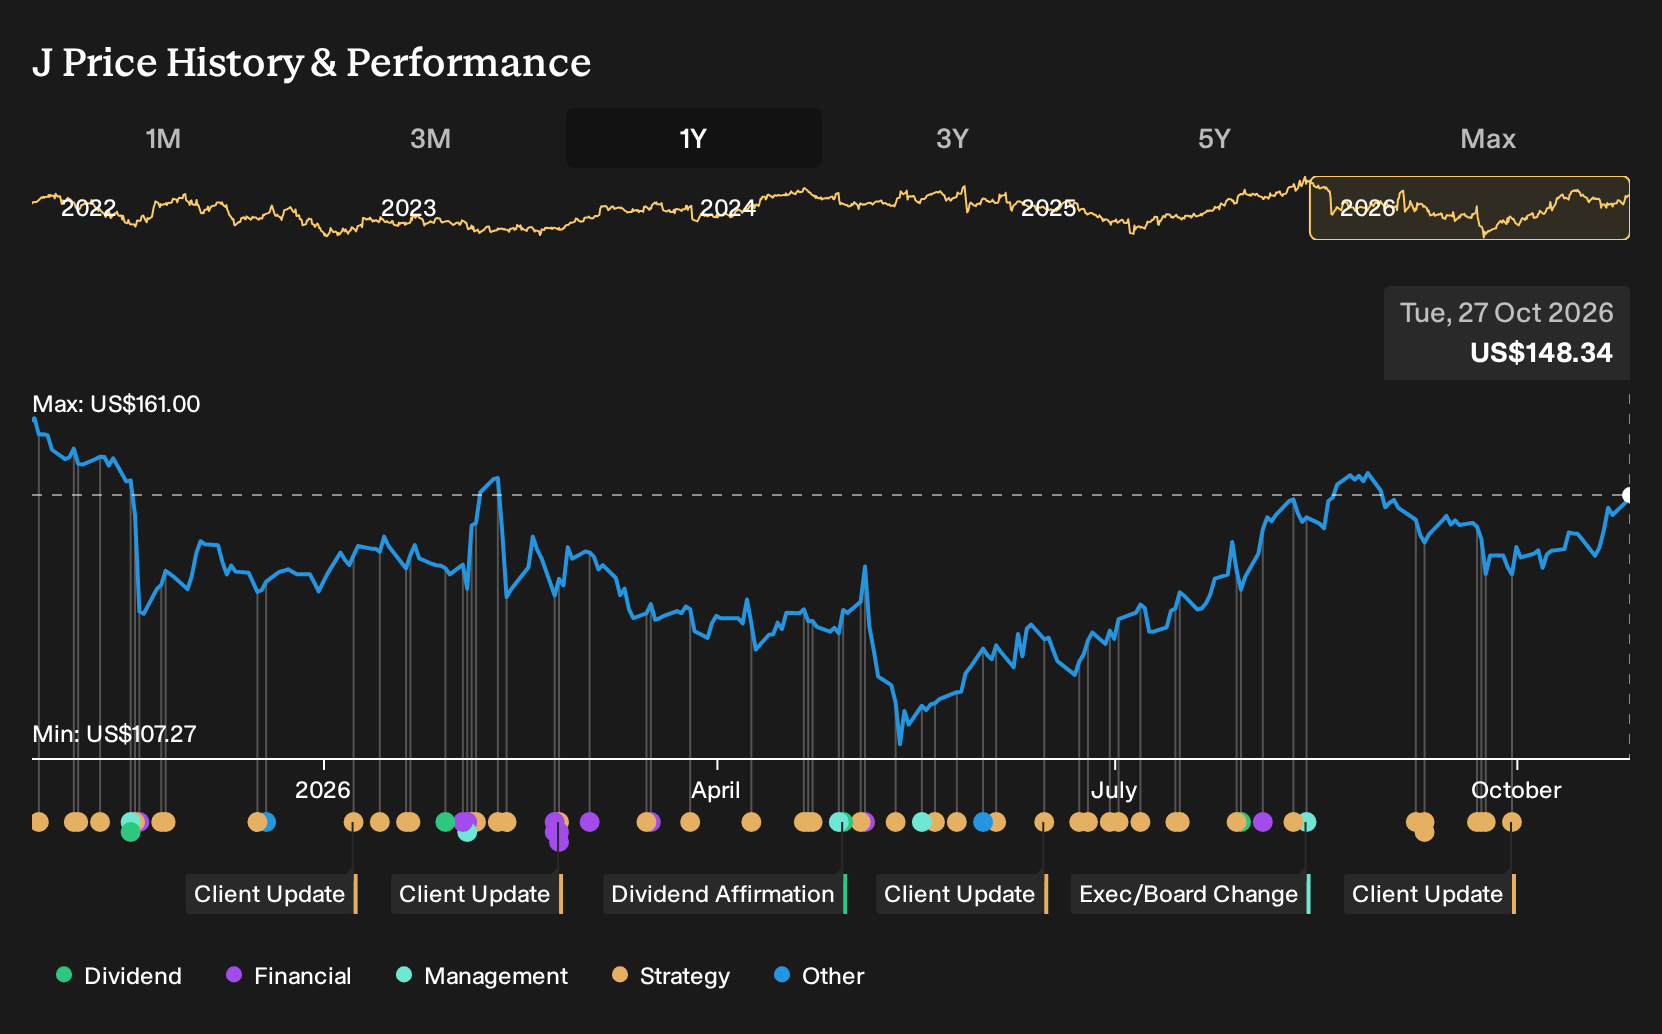
To own Jacobs Solutions, you need to believe the firm can keep turning a record US$29b backlog, plus newer wins in water and energy, into steadier earnings and better margins over time. The San Francisco nutrient reduction award fits that long duration project profile but is not likely to change the near term earnings story on its own.
The bigger swing factor still sits in execution on AI data centers and critical infrastructure work, where management already sees a large project pipeline. The key near term risk remains heavy exposure to public sector budgets and higher debt, which could pressure backlog conversion and cash returns if funding or sentiment toward large projects weakens.
The energy infrastructure survey Jacobs released in late October feels highly relevant here. Management is hearing from customers that capital is available, but many projects get stuck on permitting, regulation, and interdependent grid and water assets. That feedback lines up with the long dated, complex profile of the San Francisco wastewater upgrade.
If those bottlenecks persist, the risk is slower conversion of Jacobs Solutions awarded work into revenue, regardless of contract size. If owners accelerate project approvals instead, the existing backlog and large frameworks in transportation, power, and water could act as a practical catalyst by feeding higher utilisation and supporting the margin programs already in place.
Jacobs Solutions' narrative projects US$17.5b revenue and US$1.2b earnings by 2029. This assumes 7.1% yearly revenue growth and an earnings increase of about US$840.7m from US$359.3m today.
Uncover why Jacobs Solutions' fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$110 at the low end to about US$291 at the high end. This shows just how far apart retail views on Jacobs Solutions can be. You see that spread before the San Francisco contract and upcoming earnings call, so treat it as a starting point to explore several alternative viewpoints rather than a verdict.
Explore 2 other Jacobs Solutions fair value estimates, including one that suggests potential upside of up to 96% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jacobs Solutions research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Jacobs Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jacobs Solutions' overall financial health at a glance.
Looking for more investment ideas beyond Jacobs Solutions?
Once you have a view on Jacobs Solutions, it can help to compare it with other opportunities that match different risk, income, and balance sheet profiles using the Simply Wall St Screener.
- If capital protection comes first for you, start by reviewing 30 resilient stocks with low risk scores which score well on resilience and downside control.
- For investors who want stronger balance sheets behind their theses, check out the list of solid balance sheet and fundamentals (24 results) to see companies with healthier financial footing.
- If you are hunting for lesser known opportunities with quality fundamentals, scan through the 21 high quality undiscovered gems that might not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com