


EN
Aflac (AFL), Why Is It Getting Fresh Attention Now?
Aflac’s upcoming analyst briefing puts focus on long term strategy
Aflac (AFL) has set December 3, 2026 for its Financial Analysts Briefing webcast, where executives plan to cover operations in the U.S. and Japan, reinsurance plans, and the medium term outlook.
Aflac’s share price has climbed 7.3% over the past month and is up 10.7% year to date, while the 1 year total shareholder return of 16.7% and 5 year figure of 147.8% point to momentum that has built steadily over time.
Scan 30 resilient stocks with low risk scores that, like Aflac, combine established operations with an emphasis on resilience and capital discipline ahead of their next big update.
Bulls see Aflac’s recent climb and planned briefing as proof the market still underestimates its cash generation. Bears point to flat revenue and lower net income growth. Which side does today’s valuation lean toward?
Most Popular Narrative: 2.9% Overvalued
Aflac last closed at $121.99, a touch above the most followed fair value estimate of $118.53 that is built using a 7.24% discount rate. That small gap leaves the briefing as a test of whether management can convince investors its capital and investment moves justify paying up.
The repositioning of about 5% of Aflac’s global investment portfolio, using foreign exchange gains on dollar assets to support moves out of older bonds, is expected to add over US$50 million of annual net investment income on a run rate basis. This directly supports earnings even if premium growth stays modest.
See why 44 investors see Aflac as 3% overvalued.
Result: Fair Value of $118.53 (OVERVALUED)
Still, pressure on Japan premiums and a higher benefit ratio, along with the fallout from the recent cybersecurity breach, could quickly challenge this Aflac narrative.
Find out about the key risks to this Aflac narrative.
Another View: Aflac Through A Cash Flow Lens
The earlier fair value of $118.53, based on earnings and analyst targets, suggests Aflac is 2.9% overvalued. A different lens tells a very different story. Our DCF model puts future cash flow value at $173.05, which implies the current $121.99 price sits well below that estimate. Which signal do you treat as more important: the earnings multiple view, or the long term cash flow math?
For a closer look at how this cash flow view is built, and how sensitive it is to the inputs you care about, Look into how the SWS DCF model arrives at its fair value.
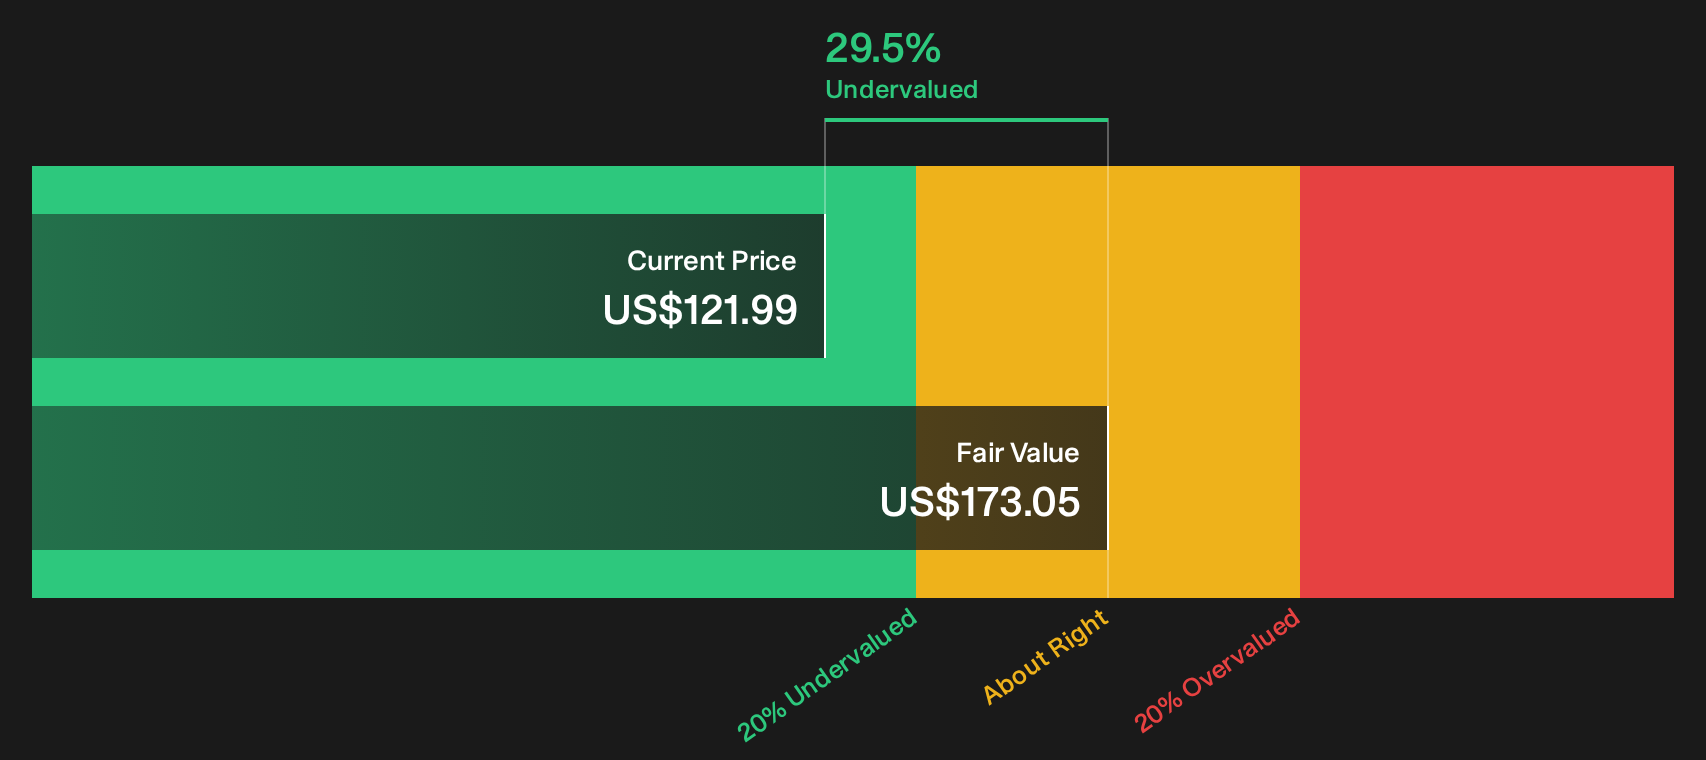
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aflac for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Aflac’s value can cut both ways, so consider acting promptly, review the numbers for yourself, and weigh 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Aflac?
If you want to round out your watchlist before Aflac’s analyst briefing, use the Simply Wall Street Screener to spot other opportunities you do not want to miss.
- Target resilient opportunities with strong balance sheets and consistent fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) so your shortlist is built on financial strength.
- Hunt for potential value candidates by running the 29 high quality undervalued stocks and compare their pricing against the cash flows and balance sheets you are most comfortable backing.
- Lock in potential income ideas by reviewing the 5 dividend fortresses and see which businesses offer higher yields while still prioritizing financial robustness.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com