


EN
Antitrust Trial Could Be A Game Changer For Keurig Dr Pepper Stock (KDP)
- Keurig Dr Pepper faces an antitrust lawsuit that is now set to proceed to trial, putting the company’s business practices under closer regulatory scrutiny.
- The move toward trial arrives as Keurig Dr Pepper prepares to report quarterly results, increasing attention on how legal risk intersects with operating performance in coffee and beverages.
- We now examine how Keurig Dr Pepper’s investment narrative could be affected by the advancing antitrust case against the business.
Scan beyond Keurig Dr Pepper’s legal and earnings uncertainty, and line up other consumer names facing their own pressure points with our hand picked 30 resilient stocks with low risk scores.
Keurig Dr Pepper Investment Narrative Recap
For Keurig Dr Pepper, the big picture you need to buy into is a beverage engine that can keep offsetting a pressured U.S. Coffee unit while management works toward the planned split into a Beverage Co and a Global Coffee Co by early 2027. The headline antitrust trial raises questions about business practices, but based on what is known today it does not directly alter that operational roadmap.
The key near term swing factor is the upcoming quarterly report, especially any signs of relief on higher input costs, pod volume pressure and weak coffee profitability. The largest current risk sits in that same coffee segment, where category volume softness, private label share gains and green coffee or tariff volatility could keep margins under strain.
The most relevant near term reference point for this legal overhang is the upcoming earnings release that is expected on 3 November, with analysts looking for higher revenue and earnings versus last year. A negative Earnings ESP and a Zacks Rank of #4 suggest those forecasts are cautious, so the print could quickly reshape sentiment around how much flexibility Keurig Dr Pepper has to absorb legal expenses or potential remedies.
If U.S. Refreshment Beverages and the growing energy portfolio again show solid top line contribution, that would support the idea that the beverage side can help fund integration work and preparation for the separation, even while the court case advances. If the coffee unit instead shows further profit compression, investors will likely focus more on execution risk around integrating JDE Peet’s, achieving the targeted US$400m of cost synergies and supporting debt and dividend commitments while carrying additional regulatory scrutiny.
Keurig Dr Pepper's current analyst script points to revenues of US$31.8b and earnings of US$3.3b by 2029. These figures are built on assumed yearly top line growth of 16.5% and an earnings increase of about US$2b from US$1.3b today.
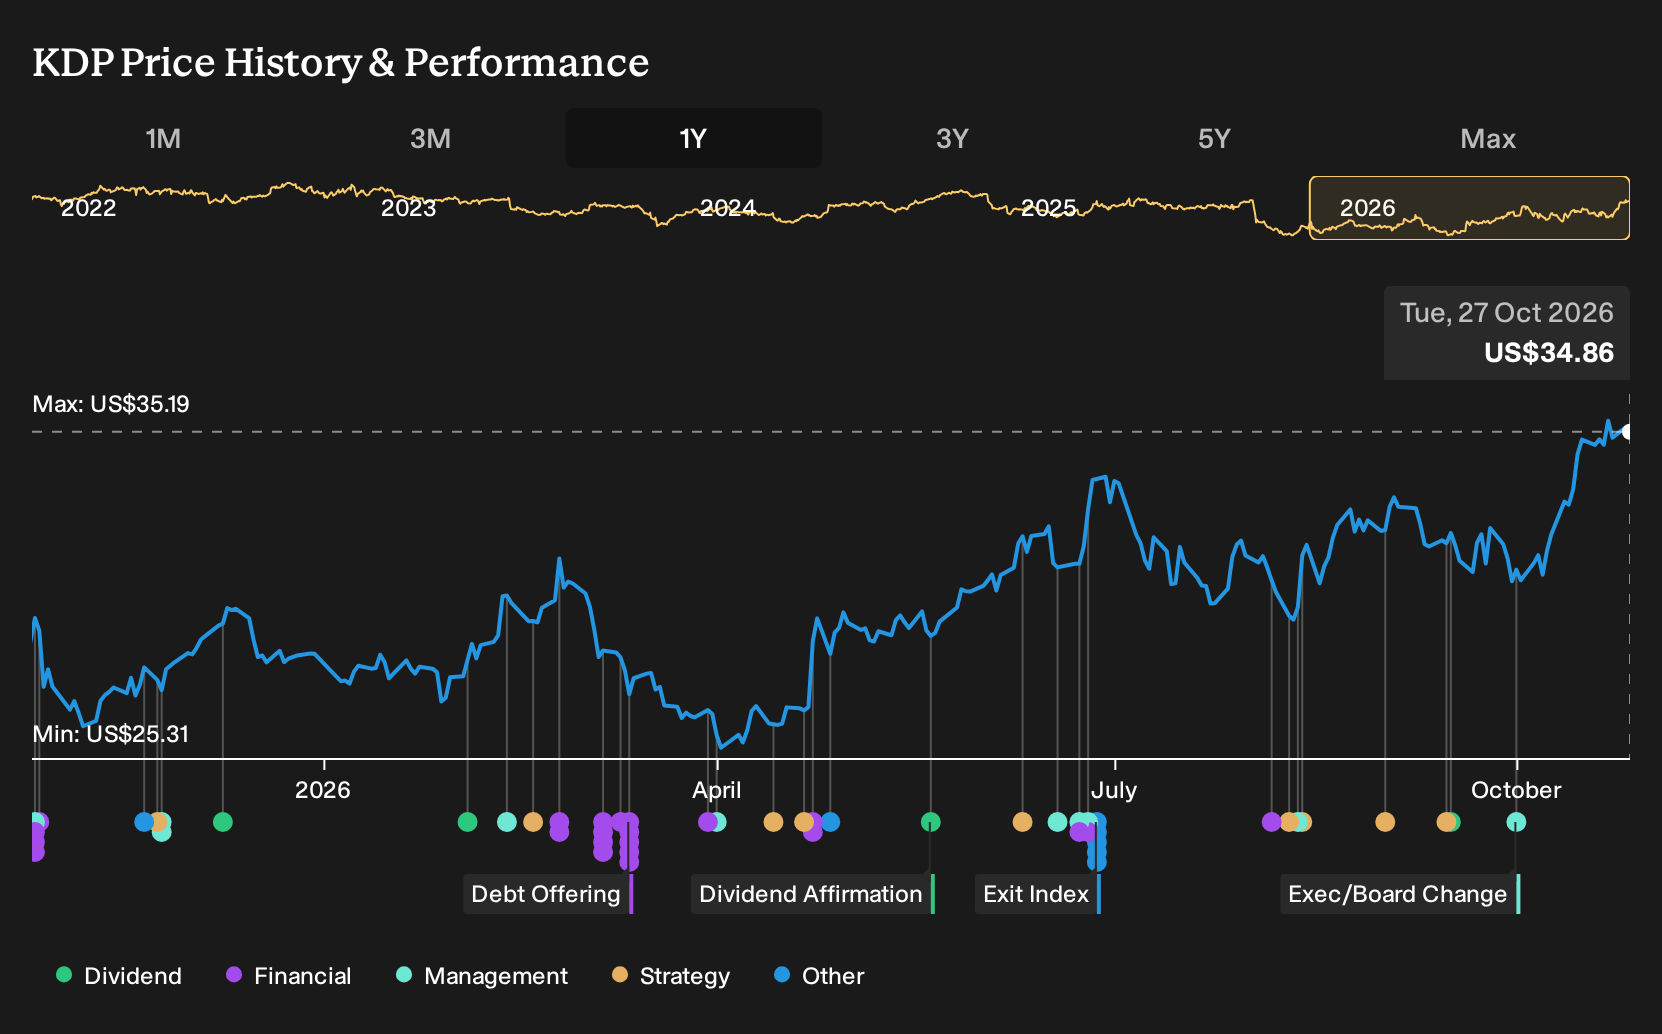
Uncover how Keurig Dr Pepper's fair value indicates a 4% potential upside to its current price, which could narrow quickly as legal and earnings clarity improves.
Exploring Other Perspectives
Five fair value views from the Simply Wall St Community span roughly US$21 to almost US$108, which shows how far opinions on Keurig Dr Pepper can stretch. Those estimates were set before the antitrust trial news and coffee segment pressure, so treat them as one input and explore several alternative viewpoints before forming your own stance.
Explore 4 other Keurig Dr Pepper fair value estimates, including one that suggests as much as 39% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Keurig Dr Pepper research is our analysis highlighting 2 key rewards and 5 important warning signs that could impact your investment decision.
- See our latest analysis for Keurig Dr Pepper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Keurig Dr Pepper's overall financial health at a glance.
Looking For More Investment Ideas Beyond Keurig Dr Pepper?
If you want to balance Keurig Dr Pepper with other opportunities, the Simply Wall St Screener can help you filter the market quickly using fundamentals that match your own risk and return preferences.
- For investors who care most about stability and capital preservation, start with a shortlist of companies that screen as resilient using our 30 resilient stocks with low risk scores.
- If value is your focus, sharpen your watchlist by reviewing a curated 29 high quality undervalued stocks that pairs quality fundamentals with prices that may look appealing on the numbers.
- Income focused investors can scan for yield potential and balance sheet support through a hand picked set of 5 dividend fortresses that merit a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com