


EN
Tate And Lyle (LSE:TATE) Stock May Be Overvalued Despite Its 54% Run
Tate & Lyle shares have delivered a strong year so far, which puts fresh focus on whether the current valuation is adequately supported by the company's earnings power. With the price moving ahead of much of the recent history, the question now is what you are really paying for in terms of profit generation.
- The stock is up 53.7% year to date, which puts more pressure on the underlying earnings profile to justify the higher entry point.
- The business leans heavily on converting its ingredient portfolio into steady profit and cash flow, so the durability and quality of those earnings can shape how comfortable investors feel with the current multiple.
- The analysts covering Tate & Lyle have run their own numbers. See what analysts think Tate & Lyle's shares could be worth.
The issue now is whether Tate & Lyle's current share price is appropriately aligned with what its earnings suggest it should be worth.
If you are weighing whether Tate & Lyle's recent 53.7% year to date rise feels stretched, it can help to compare it with other companies screened for 10 high quality undervalued stocks
Has Tate & Lyle Run Too Far on Earnings?
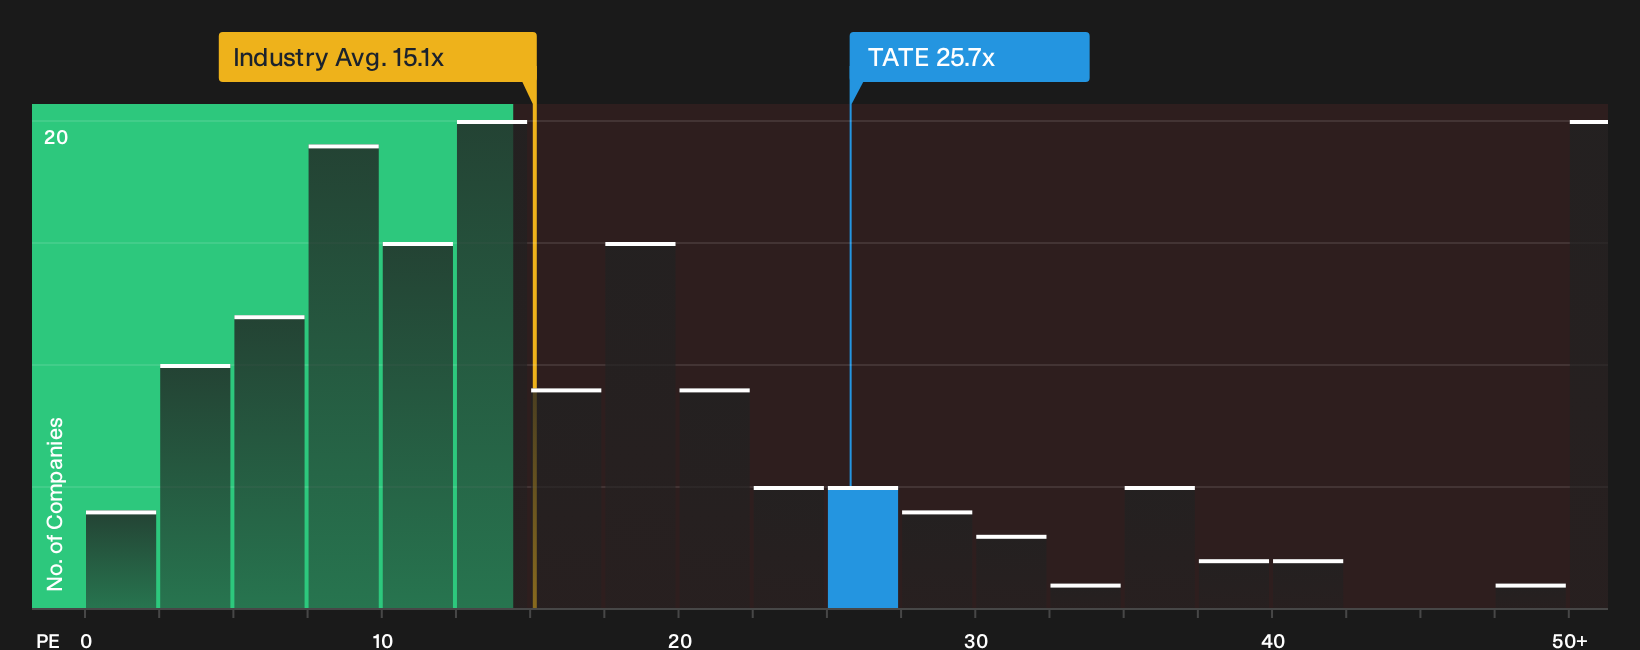
The P/E ratio suits Tate & Lyle because earnings sit at the centre of how you judge a mature ingredients producer. The current P/E of 25.7x sits well above the wider food industry on 14.6x and also above the peer group average of 18.4x, so you are paying a steeper price for each pound of profit than for many similar businesses.
The valuation model that blends Tate & Lyle's growth, margins, size and risk suggests a lower P/E would be more in line with its profile. As a result, the shares screen as overvalued on this yardstick. For any investor, the key question is whether Tate & Lyle's earnings quality, cash conversion and product mix feel strong enough to justify that premium or whether expectations have moved ahead of what the profit stream can reasonably support. Explore the numbers behind Tate & Lyle's P/E valuation.
The Tate & Lyle Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Tate & Lyle's valuation question leaves off by spelling out which future paths for growth, profitability and earnings would need to play out for the current share price to look either too low or too demanding, and they sit within the platform's Community page. Rather than relying on a single multiple or one model output, each framework lays out its own set of fair value assumptions so you can compare them with the figures Tate & Lyle reports over time.
Community views on Tate & Lyle are split between those who see more upside from integration and productivity work and those who think the current price already bakes most of that in.
Bull case: 8% undervalued
"The productivity programme has already produced $144 million of savings over 3 years and the 5 year target was raised from $150 million to $200 million by the end of the 2028 financial year..."
Discover why this Narrative puts Tate & Lyle at 8% undervalued.
Bear case: roughly fairly valued
"The current valuation and the recommended Ingredion all-cash offer at about 8.8x FY2026 adjusted EBITDA together imply that the share price already reflects a fair value for Tate & Lyle..."
Explore why this Narrative puts Tate & Lyle at roughly fairly valued.
Tate & Lyle's price is only one piece of the puzzle
Valuation tells you what the market pays today, while the analyst view on where Tate & Lyle might be a few years from now can change how that price looks on your screen. Explore where analysts expect Tate & Lyle to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com