


EN
Dear Altria Stock Fans, Mark Your Calendars for October 29
Tobacco giant Altria Group (MO) may seem like an unlikely investment favorite in an era of steadily declining adult smoking rates over the past few decades. Yet, investors aren’t ready to give up on the stock just yet. Altria has demonstrated remarkable resilience this year, outperforming many broader market benchmarks as investors gravitate toward its defensive cash flows, attractive dividend yield, and enduring pricing power.
The company continues to lean on a familiar playbook to drive shareholder returns, including raising cigarette prices, cutting costs, and repurchasing shares to boost earnings per share (EPS) and sustain dividend payouts. At the same time, Altria is broadening its portfolio of smoke-free alternatives, including NJOY e-cigarettes and On nicotine pouches, to fuel top-line growth and gradually reduce its long-term dependence on cigarettes and cigars.
Now, another potential catalyst is on the horizon. Altria is set to unveil its fiscal 2026 third-quarter earnings before the market opens on Thursday, Oct. 29. The upcoming report could offer fresh insights into the tobacco industry's outlook, its evolving growth prospects, and the company's progress in expanding its smoke-free product portfolio. With investors weighing Altria's defensive strengths against the challenges facing the traditional tobacco business, here's a closer look at the stock.
About Altria Stock
Altria Group is a leading U.S. tobacco and nicotine company headquartered in Richmond, Virginia, with a business heritage spanning more than 200 years. The company operates through a portfolio of established businesses, including Philip Morris USA, the maker of Marlboro cigarettes, and John Middleton, known for Black & Mild cigars. Its other prominent brands include Copenhagen and Skoal, which offer smokeless tobacco products, and on!, a range of oral nicotine pouches.
Through these businesses, Altria maintains a strong presence across traditional tobacco products while expanding its offerings to meet evolving adult nicotine consumer preferences. As part of its strategy to move beyond traditional smoking, Altria is investing in smoke-free product platforms, including NJOY e-vapor products and on! nicotine pouches. The company also has a majority-owned joint venture, Horizon Innovations, with Japan Tobacco Group for the U.S. marketing and commercialization of heated tobacco stick products.
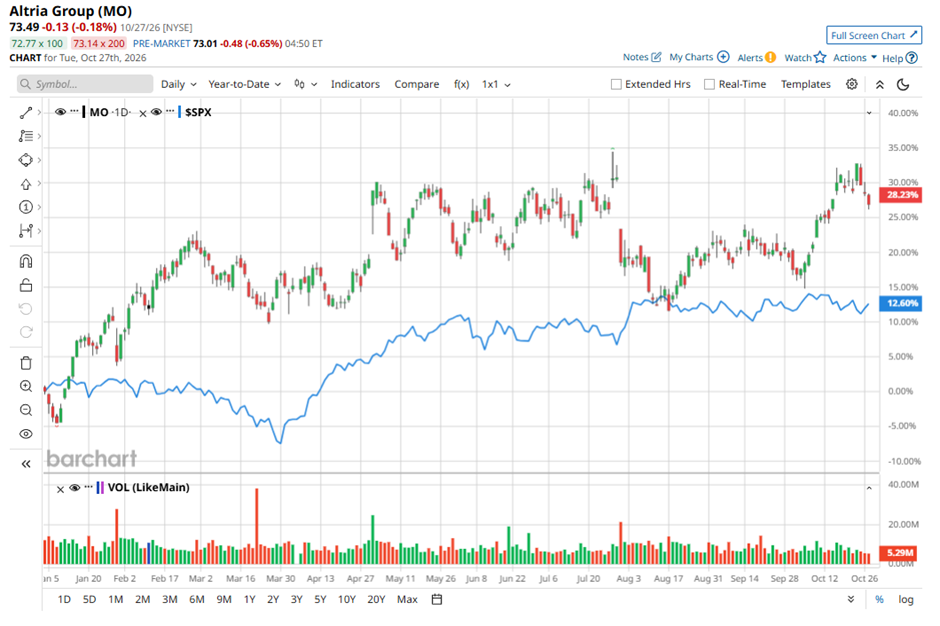
With a market capitalization of $122.71 billion, Altria Group is proving that traditional tobacco stocks can still pack a punch. Despite growing health consciousness and shifting consumer habits, MO has rallied 27.5% in 2026 and gained 15.3% over the past year. By comparison, the S&P 500 Index ($SPX) has advanced 12.9% this year and gained 12.2% over the past year. Altria’s outperformance highlights the enduring appeal of its cash-generating business, pricing power, and dividend-driven investment story.
Altria continues to sweeten its appeal for income-focused investors. On Oct. 9, the company paid a quarterly dividend of $1.11 per share, up 4.7% from its previous payout of $1.06. This brings its forward annualized dividend to $4.44 per share, translating into an attractive 5.97% yield.
The latest hike also aligns with management’s progressive dividend policy, which targets mid-single-digit annual growth in dividends per share through 2028. Even more impressive, this marks Altria’s 61st dividend increase in the past 57 years, cementing its status as a Dividend King, a company that has raised its dividend for at least 50 consecutive years.
Inside Altria’s Q2 Earnings Report
Altria delivered a mixed second-quarter performance in July, with pricing power in its core smokeable products business helping offset declining cigarette volumes and weakness in its oral tobacco segment. Net revenues were essentially flat at $6.11 billion, while revenues excluding excise taxes edged up 1.2% to $5.36 billion, meeting Wall Street expectations. Adjusted diluted earnings per share rose 2.8% year-over-year (YoY) to $1.48 but fell short of analysts’ consensus estimate of $1.50.
The company’s smokeable products segment remained its primary profit engine. Net revenues excluding excise taxes increased 2%, as strategic price hikes helped counter persistent declines in cigarette shipments. Domestic cigarette shipment volumes fell approximately 3.2%, reflecting the industry’s long-term consumption challenges. After adjusting for trade inventory movements, the decline was steeper at an estimated 4.5%.
Meanwhile, flagship brand Marlboro continued to anchor Altria’s premium cigarette portfolio, although mounting economic pressures encouraged some consumers to switch to lower-priced alternatives. Altria’s oral tobacco business faced greater headwinds, with net revenues declining 5.3% as lower shipment volumes and increased promotional spending outweighed the benefits of higher pricing.
Revenues excluding excise taxes fell 5.2%, while domestic shipment volumes dropped 8.5%, primarily due to retail share losses and trade inventory movements, alongside other industry-related factors. On the smoke-free front, Altria continued to expand its growth initiatives. Helix extended the distribution of its on! PLUS nicotine pouches to 120,000 stores nationwide, supported by consumer trial initiatives and plans for additional product line extensions later in the year.
Despite mixed segment results, the company returned nearly $3.9 billion to shareholders through dividends and share repurchases in the first half of 2026. Building on its first-half performance, Altria raised the lower end of its full-year 2026 earnings guidance. The company now expects adjusted diluted EPS of $5.61 to $5.72, representing growth of 3.5% to 5.5% from its 2025 base of $5.42.
The revised outlook underscores management’s confidence in its ability to sustain earnings growth through pricing discipline and cost management, even as declining cigarette volumes and competitive pressures continue to challenge parts of its business.
What Do Analysts Think About MO Stock?
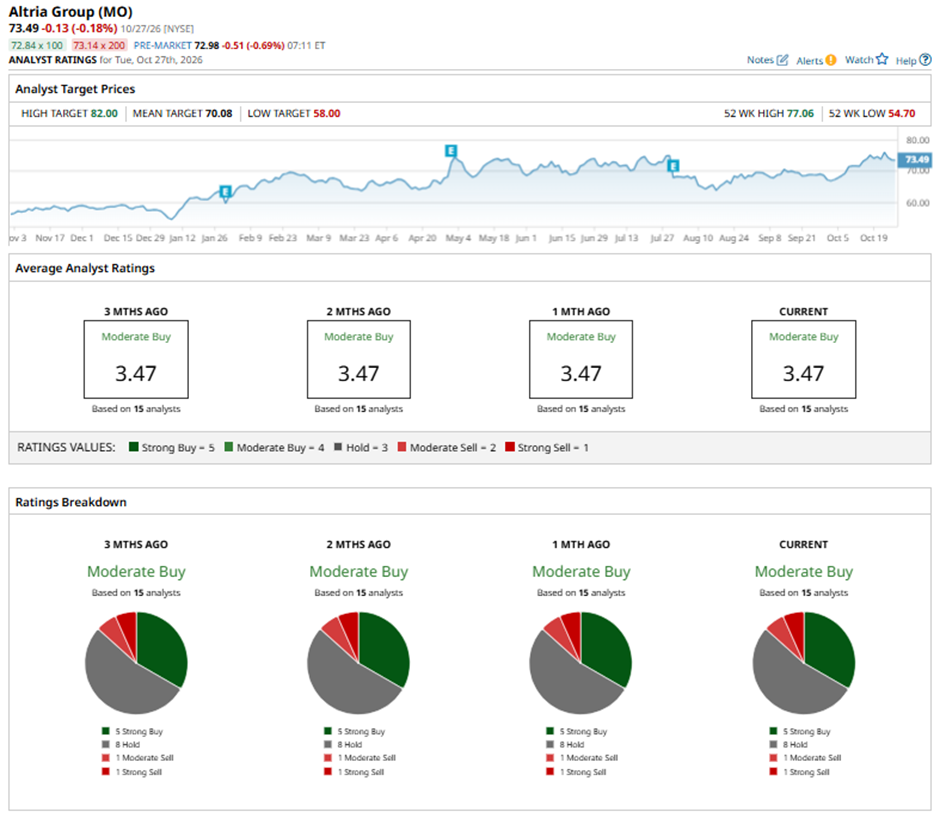
With Altria’s third-quarter earnings report approaching, Wall Street remains cautiously optimistic, assigning MO stock a consensus “Moderate Buy” rating. Of the 15 analysts covering MO, five recommend a “Strong Buy,” eight rate it “Hold,” while one each recommends “Moderate Sell” and “Strong Sell.” Although the stock is already trading above its average price target of $70.08, the Street-high target of $82 suggests a potential upside of 11.3%, leaving room for further gains if the upcoming results impress investors.
On the date of publication, Anushka Mukherji did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.