


EN
Adobe (ADBE) Stock May Be Undervalued On Its New AI Fan Deal
Adobe has been under pressure for several years while still investing heavily in AI partnerships and new products. That combination of share price weakness and business activity raises a clear question for investors who care about valuation: does the current stock price line up with what its earnings can support?
- Over the past 5 years, Adobe shares have fallen 61.2%, which makes the link between today’s lower price and the strength of its earnings more important than during a simple short term pullback.
- Recent AI focused deals, from Formula One fan experiences to deeper work with NVIDIA, can influence how quickly revenue and profit from Adobe’s creative and data platforms grow relative to what its current P/E suggests.
- There is a second opinion on Adobe worth weighing. See what analysts think Adobe's shares could be worth.
For investors, the debate is whether Adobe’s recent share price level is justified by the earnings power the business is generating today.
If you want to test the same earnings based valuation question you are asking of Adobe across a broader AI focused set of businesses, run the numbers on 38 AI small caps.
Is Adobe Still Cheap on Earnings?
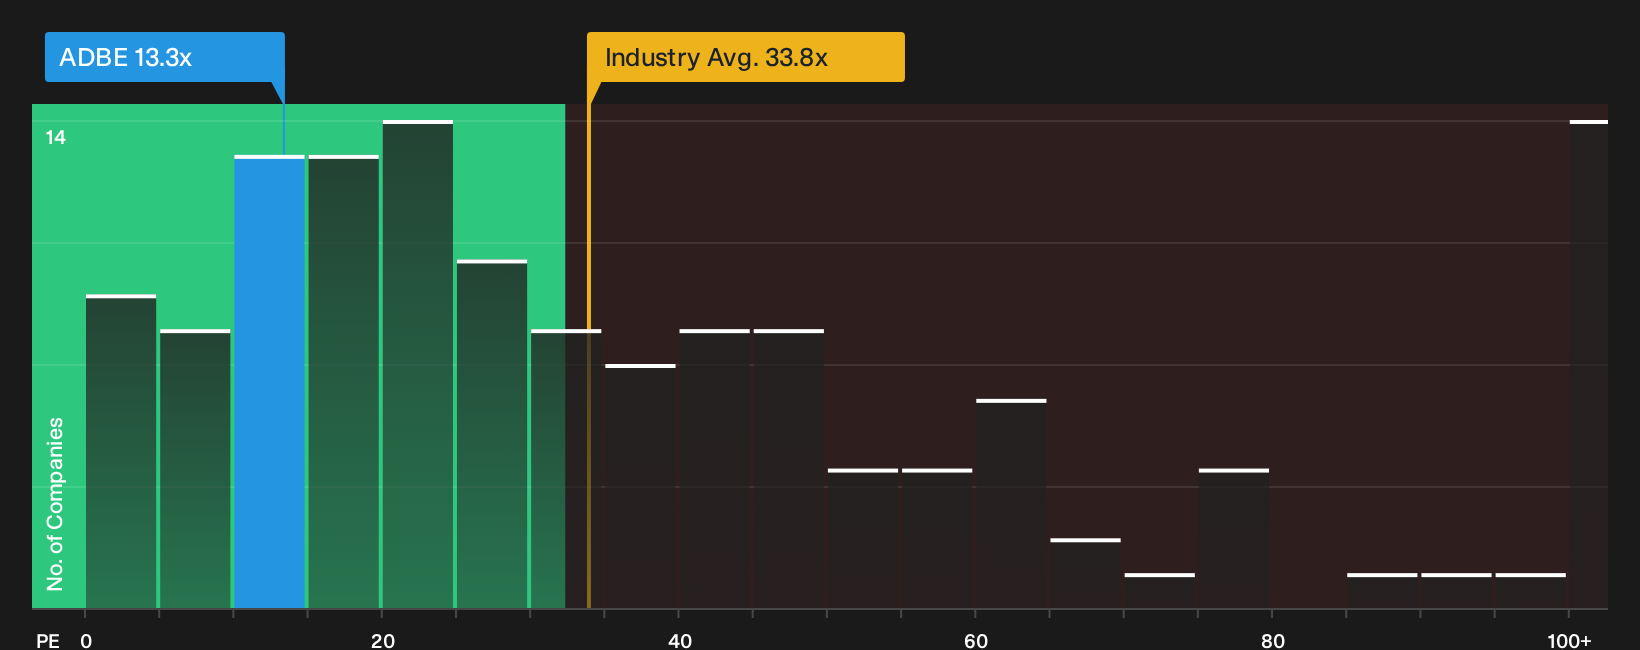
The P/E lens suits Adobe because earnings still drive how investors frame the value of its software franchises. On this measure, the stock trades on a P/E of 13.3x, which sits far below the broader software industry average of 33.8x and the peer group average of 48.2x. Against the Fair Ratio, which is the multiple you might expect given Adobe’s mix of growth prospects, margins, size and risk, the current P/E points to the shares looking undervalued on earnings.
Because the expanded NVIDIA partnership and the Formula One AI fan experience deal both speak directly to Adobe’s AI ambitions, the gap between the current 13.3x earnings multiple and richer peer valuations suggests investors are not paying up for those AI projects to the same degree yet. For anyone weighing whether the recent share price pressure already reflects the concerns highlighted in recent sector commentary, this discount on P/E is the starting point that needs testing with your own assumptions about Adobe’s future earnings power. Explore the numbers behind Adobe's P/E valuation.
The Adobe Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that P/E puzzle on Adobe and spell out which paths for revenue, margins and earnings would need to play out for the stock to be worth much more or meaningfully less than it trades for today, and sit on the Community page. Each version sets out a fair value as a specific thesis on Adobe's business that you can revisit over time, rather than a one off snapshot.
Adobe brings out sharply different readings in the community, with one group arguing the stock is heavily discounted and another seeing a classic value trap.
Bull case: 46% undervalued
"The current valuation of Adobe reflects a market that is pricing in a structural obsolescence that is not supported by the company’s underlying financial performance or its aggressive technological pivots…"
Discover why this Narrative puts Adobe at 46% undervalued.
Bear case: 52% overvalued
"Adobe's investment in Firefly has caused great harm in the user community…"
Explore why this Narrative puts Adobe at 52% overvalued.
Adobe's price is only one side of the decision
Valuation tells you what Adobe is priced for today, but the next piece is how professional analysts map out its earnings and revenue a few years from now, and how that compares with your own view. Explore where analysts expect Adobe to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com