


EN
Costamare (CMRE) Q3 Earnings Put Its Undervalued Narrative Back In Focus
Costamare earnings trigger fresh look at the stock
Costamare (CMRE) has put fresh numbers on the table, with Q3 2026 results showing lower revenue and net income than a year earlier. Those headline figures are now steering investor attention.
Costamare’s share price has reacted in stages, with a 3.02% 1 day share price return and 4.14% 7 day gain offset by a 6.45% decline over 90 days and an 8.48% drop year to date, while the 1 year total shareholder return of 24.88% and 3 year total shareholder return of about 1.4x suggest longer term holders have still seen strong value creation.
Compare Costamare’s post earnings reaction with other transport and shipping plays by scanning our hand picked 29 high quality undervalued stocks that currently combine discounted pricing with stronger fundamental profiles.
Recent trading now leaves Costamare down over the past quarter despite solid multi year shareholder gains and Q3 figures that softened rather than collapsed. Is this mainly a repricing of the business, or a swing in sentiment that valuation can clarify next?
Most Popular Narrative: 28% Undervalued
Costamare’s most followed valuation story puts fair value at $20, above the last close of $14.35. This frames the recent earnings reaction against a longer pipeline of contracted cash flows and capital commitments.
The earlier view that long term charters and forward fixtures could support elevated expectations is now reinforced by contracted revenues of about US$6.2b with a remaining TEU weighted charter duration of 6.1 years and revenue days fixed 97% for 2026 and 94% for 2027, which can underpin visibility for revenue and earnings.
See why 8 investors see Costamare as 28% undervalued.
Result: Fair Value of $20 (UNDERVALUED)
Still, the narrative can crack if Costamare’s softer recent revenue and net income trends persist, or if its US$0.7b capital commitments squeeze future cash generation.
Find out about the key risks to this Costamare narrative.
Another View: Costamare through a cash flow lens
The popular story has Costamare looking undervalued at a fair value of $20, yet the Simply Wall St DCF model paints a different picture. On that cash flow view, the stock at $14.35 sits above an estimated future cash flow value of $12.95, which reads as overvalued instead.
Two methods, two signals. Earnings based narratives lean on long charter coverage and contracted revenue, while the DCF output focuses on forecast declines in revenue and profit. Which lens do you trust more when the next set of numbers drops? The income statement or the cash flow model? And what does that mean for the price you are willing to pay?
Look into how the SWS DCF model arrives at its fair value.
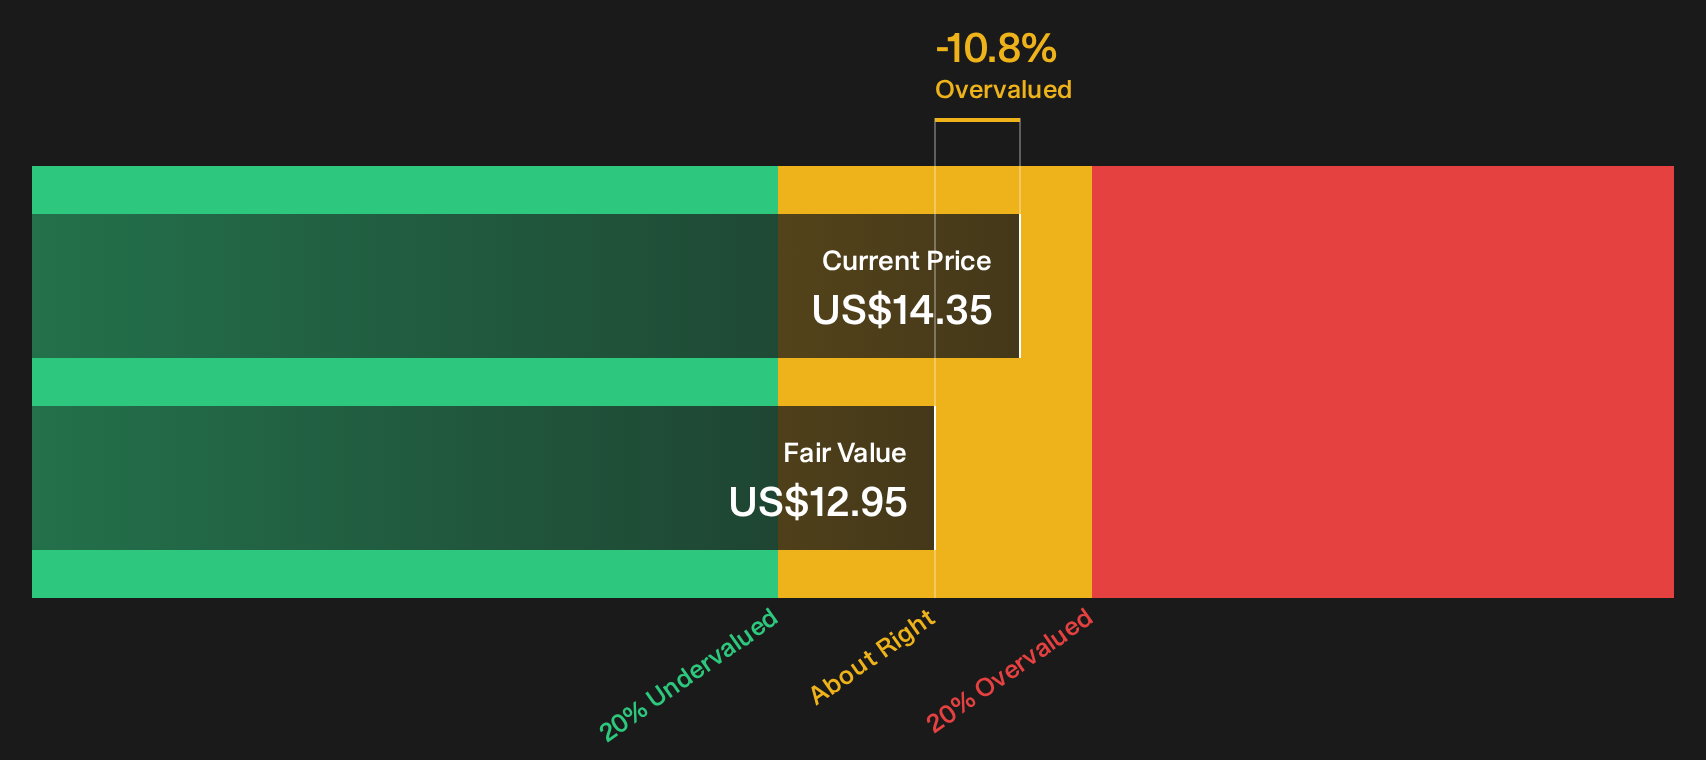
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Costamare for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between Costamare’s earnings wobble and its longer term shareholder gains is natural. Move fast, interrogate the data, and then weigh the 2 key rewards and 4 important warning signs.
Hunting for more ideas beyond Costamare?
Do not stop at Costamare. Use fresh data, clear filters, and side by side comparisons to spot other opportunities that might suit your risk and income goals.
- Target steadier potential by running through a 30 resilient stocks with low risk scores that focuses on businesses with more resilient profiles and fewer red flags.
- Chase stronger balance sheets by working through a list of solid balance sheet and fundamentals (24 results) that highlights companies with healthier leverage and fundamentals.
- Spot lesser known opportunities by scanning a 21 high quality undiscovered gems that surfaces under followed stocks with stronger financial underpinnings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com